


Castle Biosciences has seen its share price move around over the past few years, and that kind of track record naturally raises a question for you as an investor. Is the current US$35.75 price properly anchored to what the company is generating in sales today?
- Over the past 3 years the stock has delivered a 108.7% gain, which puts real weight on whether the revenue base is strong enough to back up that kind of share price journey.
- The business model is tightly linked to diagnostics for skin and other conditions, so factors such as future sales growth and the path to stronger operating leverage can play a big role in how much investors are willing to pay for each dollar of revenue.
- The analysts covering Castle Biosciences have run their own numbers. See what analysts think Castle Biosciences's shares could be worth.
The issue now is whether Castle Biosciences' current valuation is justified by its sales profile and what the market is paying for those revenues.
If you want more context on how a US$35.75 Castle Biosciences share price compares with its sales, you can compare it with other companies screened as 35 high quality undervalued stocks
Is Castle Biosciences a Bargain on Sales?
P/S fits Castle Biosciences because revenue is a key reference point while earnings are still shaped by investment in the business.
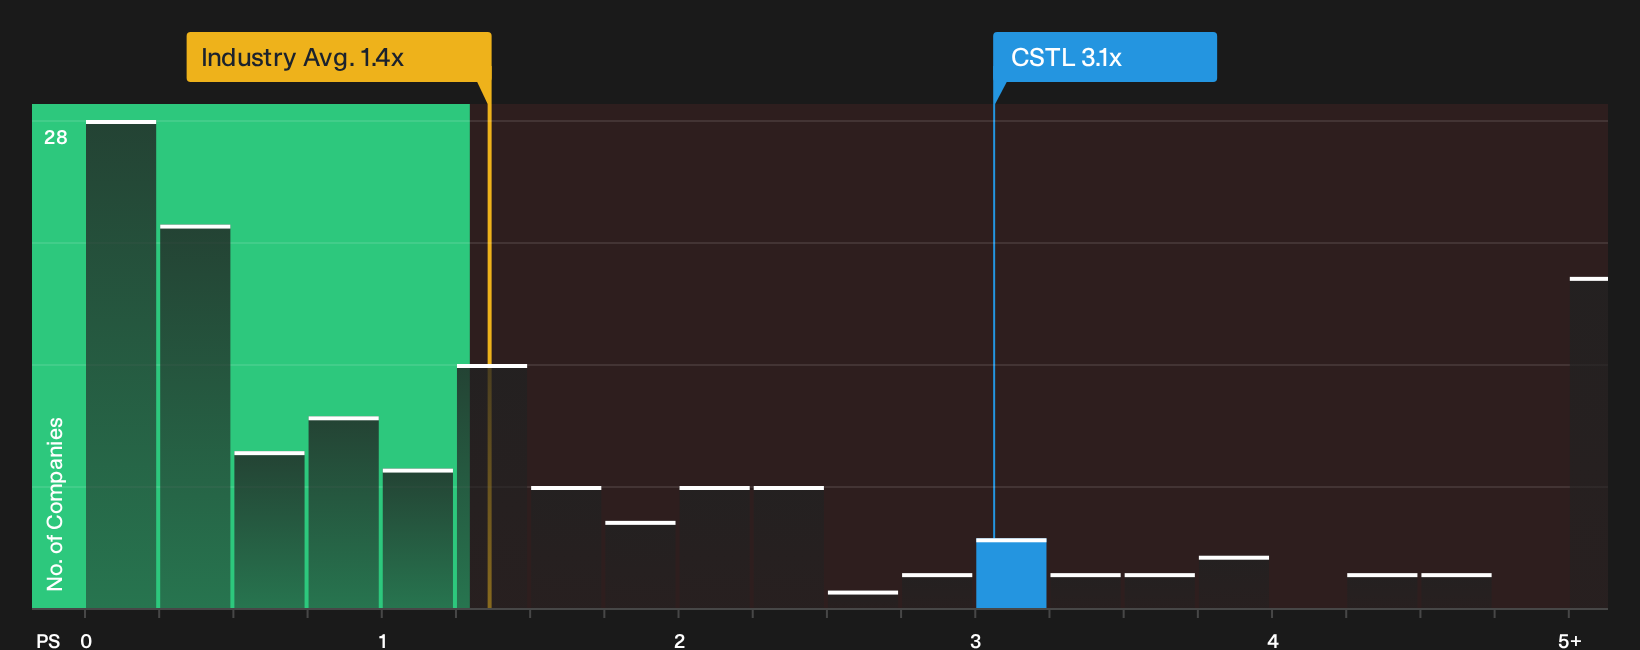
From this perspective, the stock trades on a P/S of about 3.1x, compared with a Healthcare sector average of roughly 1.4x and a peer group closer to 1.0x. The tailored fair multiple for Castle Biosciences, which reflects its own growth profile, margins, size and risk, sits above where a simple sector screen would place it. The current P/S stands below that custom yardstick, so the market is valuing each dollar of sales at a lower level than this framework suggests might be justified for the company’s fundamentals. For you as a shareholder or potential buyer, the key question is whether the revenues and business quality you see today support that implied gap in expectations. Explore the numbers behind Castle Biosciences's P/S valuation.
The Castle Biosciences Narrative: What Would Justify Today's Price?
Narratives for Castle Biosciences pick up where the valuation question leaves off and outline which paths for revenue growth, profitability and earnings would need to occur for the stock to be worth materially more or less than today’s price. All of these are hosted on Simply Wall St’s Community page.
Each scenario links its headline number to a clear view of how Castle Biosciences' growth, margins and risks might evolve, so you can revisit those assumptions as fresh results and clinical data emerge.
Community views on Castle Biosciences split between seeing more upside in the test portfolio and worrying that costs and reimbursement risks already cap the opportunity.
Bull case: 21% undervalued
"Castle Biosciences is expanding its test menu into underpenetrated indications such as Barrett’s esophagus and atopic dermatitis, with TissueCypher volumes rising 63% to 14,988 reports in Q2 2026..."
Discover why this Narrative puts Castle Biosciences at 21% undervalued.
Bear case: roughly fairly valued
"While Castle Biosciences is lifting revenue and test volumes across its portfolio, operating expenses including cost of sales moved from US$90.4 million in Q2 2025 to US$106.6 million in Q2 2026..."
Explore why this Narrative puts Castle Biosciences at roughly fairly valued.
One more angle on Castle Biosciences that investors often overlook
Everything here has focused on what Castle Biosciences looks like today, but professional coverage also sketches where the business might be a few years from now. This gives you a different yardstick to compare with the current share price. Explore where analysts expect Castle Biosciences to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com