


NCR Atleos (NATL) just put profit efficiency in the spotlight, reporting third quarter net income of US$97 million and earnings of US$1.27 per diluted share on relatively steady revenue of US$1,099 million.
NCR Atleos shares have been building momentum, with a 1-day share price return of 1.57% and a 7-day move of 4.59%. This has contributed to a 27.24% year-to-date share price gain and a 3-year total shareholder return close to 2x.
Scan for other profit driven stories like NCR Atleos by reviewing our curated 35 high quality undervalued stocks, which pairs earnings power with balance sheet strength.
NCR Atleos just turned flat revenue into materially higher earnings, and the share price has followed that profit story. Are you paying for better fundamentals here, or mostly a change in mood around the stock?
Most Popular Narrative: 6% Undervalued
Against a last close of $47.37, the most followed narrative pegs NCR Atleos at a fair value of about $50.27, implying the market is pricing in a discount that assumes some of the current earnings strength may be hard to sustain.
High recurring revenue mix (over 70% in Q2), significant productivity gains through AI-driven service optimization, and a rapidly scaling backlog are driving strong margin expansion and robust free cash flow. This is underpinning announced share buybacks and sustained EPS growth, suggesting current valuation does not reflect enhanced long-term earnings power.
See why 6 investors see NCR Atleos as 6% undervalued.
Result: Fair Value of $50.27 (UNDERVALUED)
Still, the narrative around NCR Atleos can flip if ATM usage erodes faster than expected, or if fintech and digital banking rivals squeeze pricing power and contract wins.
Find out about the key risks to this NCR Atleos narrative.
Another View On NCR Atleos Valuation
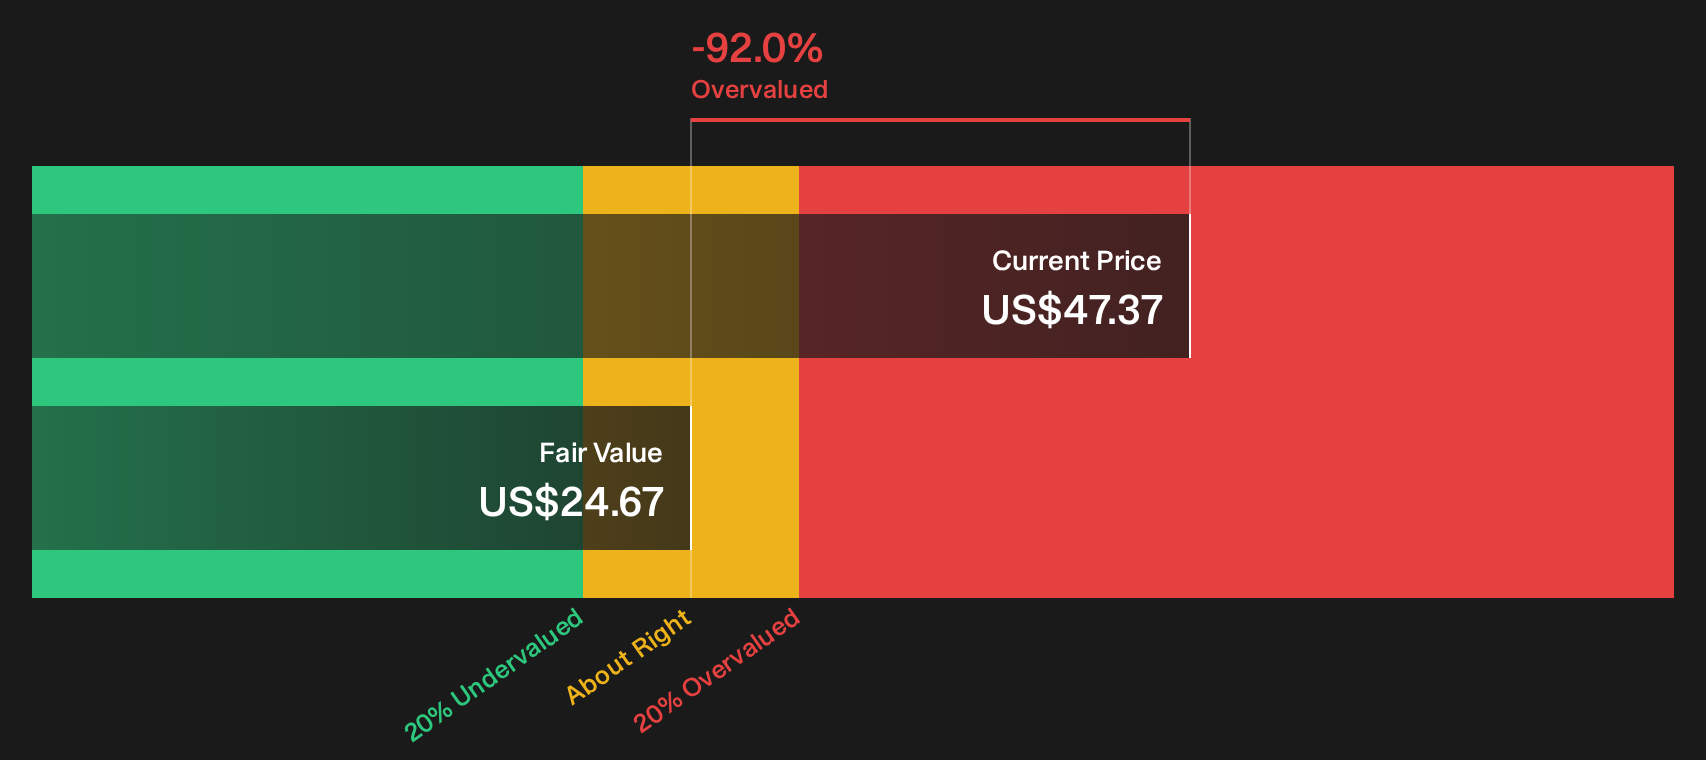
The first narrative leans on analyst targets and earnings power to argue NCR Atleos looks about 6% undervalued. A different lens, the SWS DCF model, presents a sharper contrast. On that approach, NATL at $47.37 trades well above an estimated future cash flow value of $24.67, which suggests a possible valuation stretch rather than a cushion.
That kind of gap can indicate expectations for future cash generation are higher than the model’s cash flow assumptions, even as the P/E appears reasonable versus peers. It leaves a straightforward question for investors: Do you place more weight on the earnings narrative or on the cash flow analysis?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NCR Atleos for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With NCR Atleos framed as both promising and contested, you do not need to pick a side right away. Move quickly, review the data, and weigh both the 4 key rewards and 1 important warning sign.
Looking for more NCR Atleos-sized opportunities?
If NCR Atleos has sharpened your focus on valuation and quality, do not stop here. Use targeted screeners to quickly surface fresh, differentiated ideas.
- Target dependable cash generators by reviewing our curated 35 high quality undervalued stocks that pair earnings power with resilient balance sheets.
- Lock in income potential with the 5 dividend fortresses and zero in on companies offering substantial yields with support from underlying fundamentals.
- Spot tomorrow's leaders early by scanning the 19 high quality undiscovered gems that combine strong financial profiles with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com