


Philip Morris International has delivered a powerful run over the past few years, which puts a spotlight on whether today's valuation still lines up with the earnings underpinning that share price. With the stock now carrying a long track record of gains and a clear income story, the key issue is how much of its earnings strength is already reflected in what you would pay today.
- Over the past 5 years, Philip Morris International has returned 181.7%, which raises the question of how much future earnings power the current price is already assuming.
- The latest dividend increase, backed by expectations for about US$13.5b in operating cash flow and a higher share of revenue from smoke free products, can support a case that earnings quality and cash coverage matter more than ever for this valuation.
- The analysts covering Philip Morris International have run their own numbers. See what analysts think Philip Morris International's shares could be worth.
The issue now is whether Philip Morris International's current share price is adequately supported by the earnings the business generates today.
If you are weighing Philip Morris International against other income plays, a focused stock screen is another starting point for research, especially one that highlights 5 dividend fortresses.
Does Philip Morris International Look Fairly Valued on Earnings?
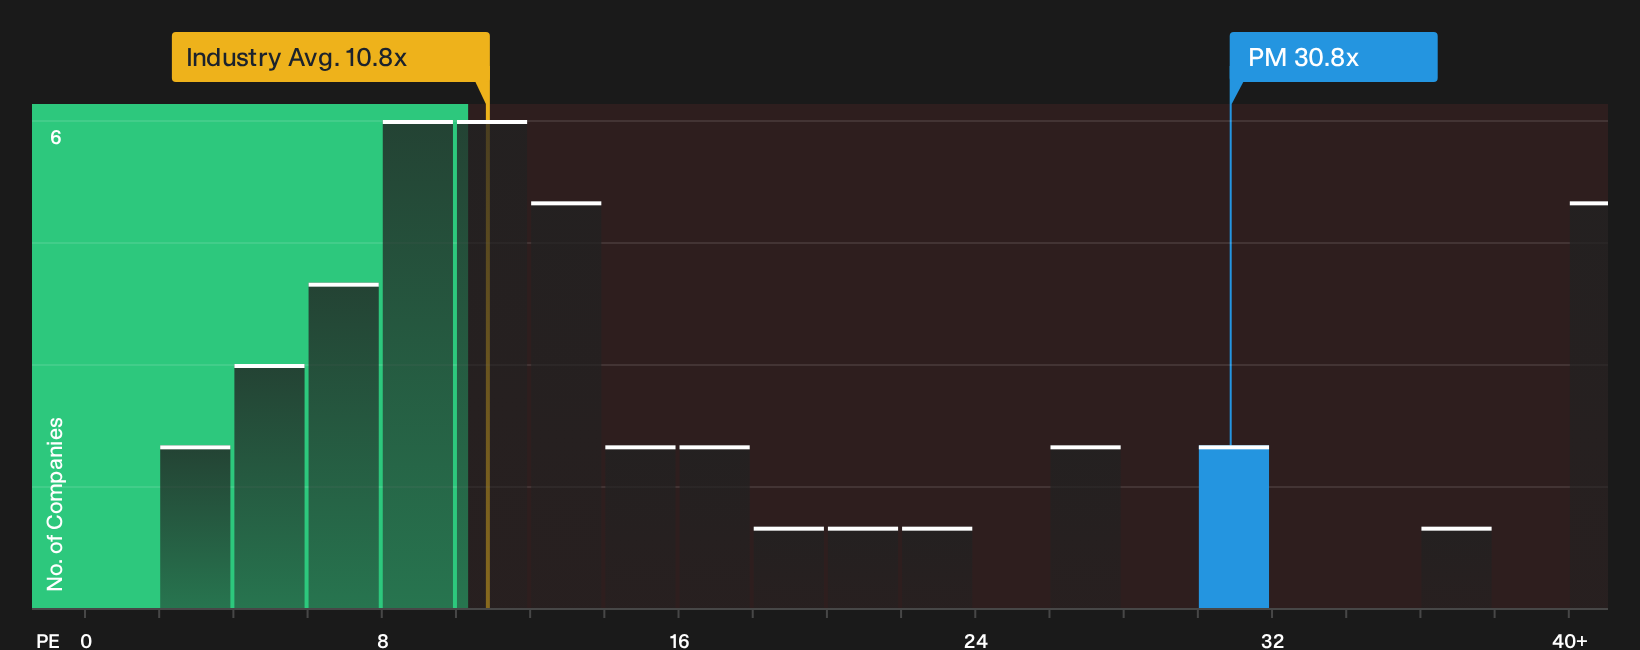
The P/E ratio suits Philip Morris International because earnings remain a central lens for a mature, cash generative consumer business. On this measure, the stock trades on roughly 30.8x earnings compared with an industry average near 10.8x and a peer group around 23.4x, so you are paying a clear premium for each dollar of profit relative to the wider tobacco space.
Because the current P/E sits close to the level suggested by a more tailored fair multiple that blends the firm’s size, margins and risk profile, the valuation looks about right on this framework rather than sharply cheap or stretched. The 2026 dividend increase and the shift toward smoke free products help explain why investors may be comfortable with that richer earnings tag, since the market is not only pricing today’s cash flows but also the perceived quality and durability behind them. Explore the numbers behind Philip Morris International's P/E valuation.
The Philip Morris International Narrative: What Would Justify Today's Price?
Narratives for Philip Morris International pick up where the P/E debate leaves off by spelling out which future paths for growth, margins and earnings would need to unfold for today’s valuation to look either conservative or demanding, using the Community page as the home for those scenarios. Where a single ratio or model gives one neat figure, Narratives unpack the future that figure relies on so you can watch in real time whether reality tracks the script.
Community views on Philip Morris International split cleanly between a smoke free driven upside story and a more cautious reading of recent guidance and execution.
Bull case: 12% undervalued
"The large excise driven price increase on heated tobacco units in Japan in April 2026, combined with IQOS keeping heat not burn category share in the high 60s and SENTIA attracting more price sensitive users, points to pricing resilience that could support higher revenue per unit and protect gross margins..."
Discover why this Narrative puts Philip Morris International at 12% undervalued.
Bear case: 12% overvalued
"Full-year guidance moved from a maintained range with an implied upside bias to an explicit “mid or lower half” framing, for both operating income and EPS..."
Explore why this Narrative puts Philip Morris International at 12% overvalued.
One more Philip Morris International question that could change your view
Price tags and earnings only tell part of the story, because the people setting priorities and the way their pay is structured can pull the whole business in different directions. See who runs Philip Morris International and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com