


Why Green Brick Partners Stock Is Back In Focus
Green Brick Partners (GRBK) reentered the spotlight after third quarter results showed lower revenue and profit versus last year, along with fresh updates on buybacks, preferred dividends, and a boardroom appointment.
Recent trading tells a mixed story. Green Brick Partners shares jumped 7.81% on the day of the update and logged a 5.71% 7 day share price return, yet the 90 day share price return is down 6.90%, while the 5 year total shareholder return of 163.51% keeps the long term picture firmly positive. This suggests that short term momentum has cooled even as longer term holders still sit on sizeable gains.
Compare Green Brick Partners' cooling momentum with other homebuilders and related plays by scanning our hand picked list of solid balance sheet and fundamentals (24 results) that might better match your risk and return preferences.
Green Brick Partners now trades above the average analyst target after a long run. Yet the recent earnings wobble and buyback activity raise a simple point: Is meaningful upside still ahead, or was most of it already captured?
Most Popular Narrative: 7% Overvalued
Green Brick Partners last closed at $66.51, while the most followed narrative pegs fair value at $62.00 using an 8.46% discount rate. That gap frames the stock as modestly overpriced, with much of the expected return profile already reflected in today’s quotation.
The main thing that has to go right is that Green Brick Partners converts its land heavy, self development model and growing mortgage capture into sustainably strong margins and returns, despite weaker backlog and higher discounting.
The numbers imply the share price already reflects a fairly valued, bearish view that balances industry leading profitability and institutional support against earnings declines, backlog pressure and mixed valuation signals.
See why 19 investors see Green Brick Partners as 7% overvalued.
Result: Fair Value of $62 (OVERVALUED)
Still, if backlog weakens further or internal control remediation drags, the narrative around Green Brick Partners’ earnings resilience could crack faster than the consensus implies.
Find out about the key risks to this Green Brick Partners narrative.
Another View: Green Brick Partners On Earnings And Multiples
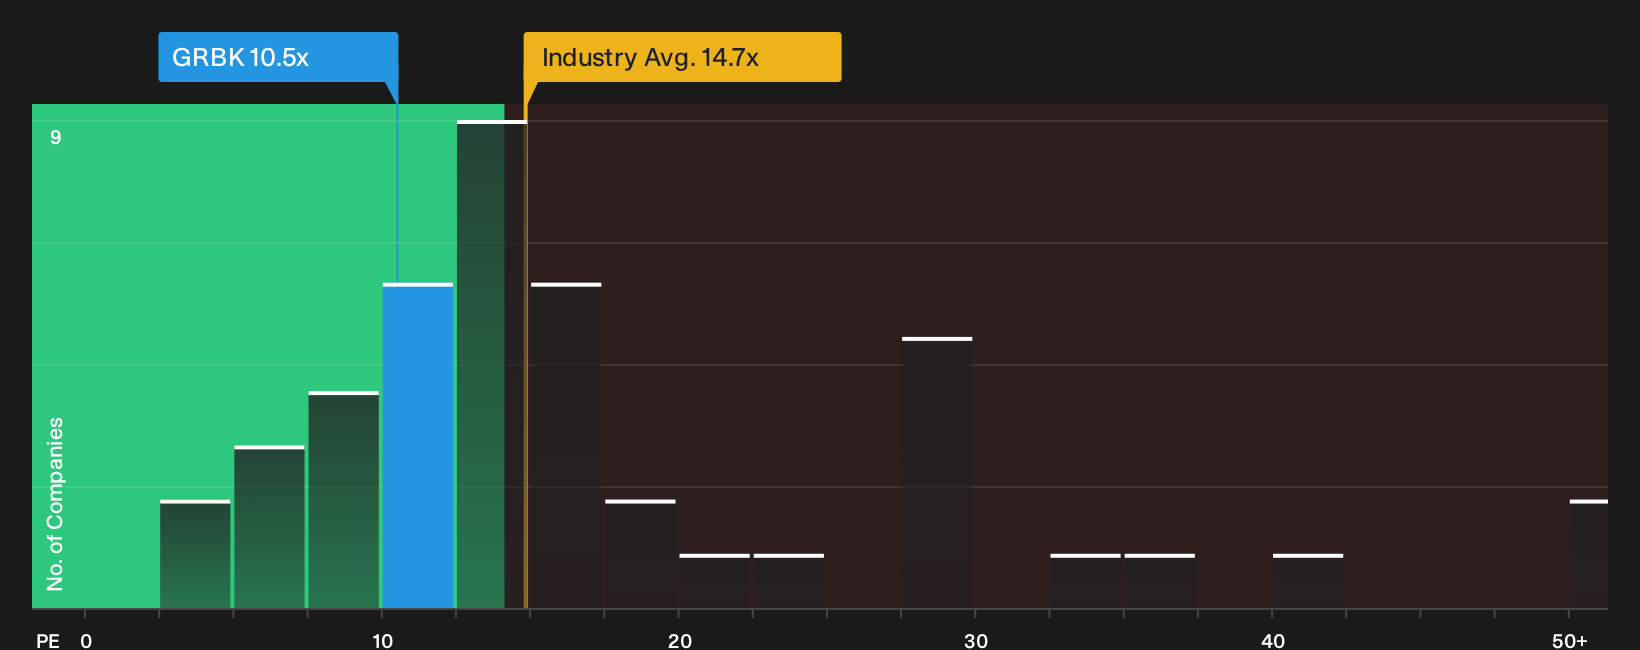
Analysts looking at Green Brick Partners through its current P/E of 10.5x see a different picture to the $62 fair value narrative. That ratio sits well below the peer average of 17.4x, the Consumer Durables sector at 13.6x, and even a 12.2x fair ratio the market could move toward. This points to more valuation risk if earnings keep slipping or an opportunity if profitability stabilises.
Numbers alone do not settle the argument. It helps to pressure test this pricing gap against a fuller valuation breakdown before deciding which story feels more realistic for your own expectations See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split mood around Green Brick Partners leaves you undecided, consider acting while the data is fresh and weighing both sides yourself with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Green Brick Partners?
Consider looking beyond Green Brick Partners to explore other opportunities that might fit your goals across quality, price, and resilience.
- Target stability first and review a curated range of resilient businesses with lower risk profiles through the 31 resilient stocks with low risk scores.
- Explore potential value opportunities by checking companies that combine quality fundamentals with appealing prices using the 35 high quality undervalued stocks.
- Build your watchlist around staying power and balance sheet strength by reviewing the list of solid balance sheet and fundamentals (24 results) while those ideas are still under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com