


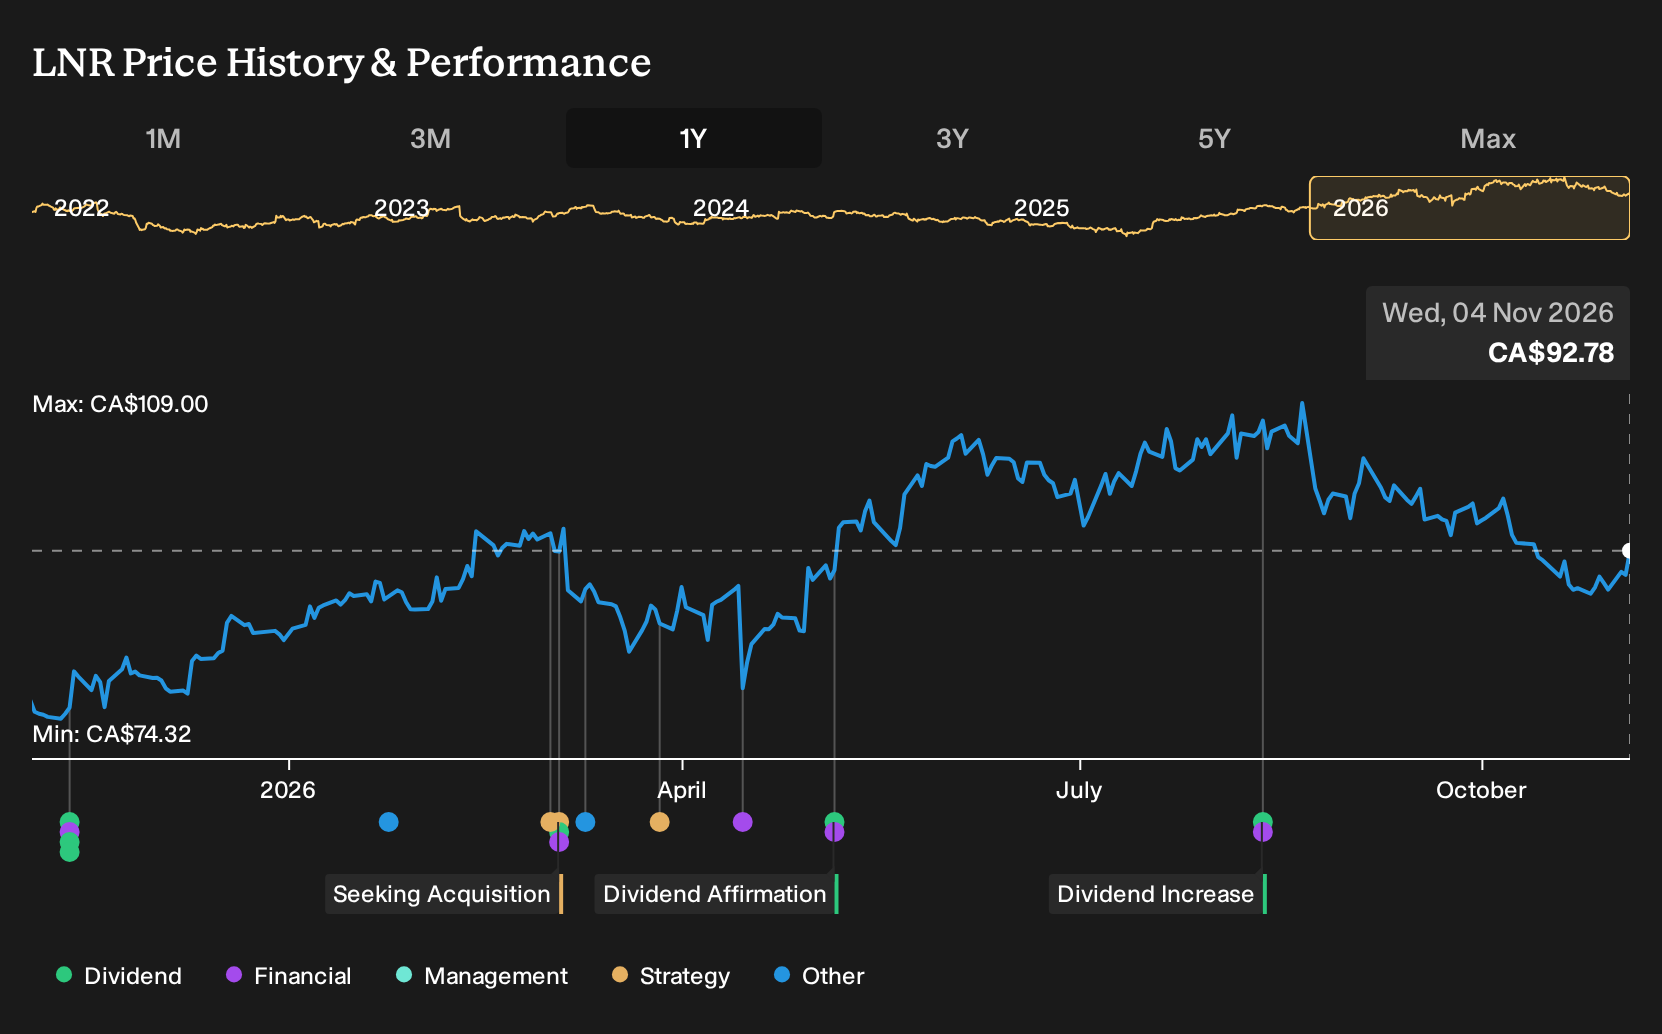
- Linamar reported third quarter 2026 sales of C$3,076.2 million compared with C$2,541.72 million a year earlier, alongside continued free cash flow generation and a renewed normal course issuer bid to repurchase up to 3,723,719 shares by November 2027.
- Record new business wins in North America and China, coupled with growth in both Mobility and Industrial segments despite customer shutdown pressures, show that Linamar is adding volume while still returning capital through ongoing buybacks.
- The focus now turns to how Linamar's record new business pipeline could influence the investment narrative, assuming current execution trends continue.
Scan how Linamar's mix of free cash flow, buybacks, and earnings trends compares to other quality industrials by reviewing our curated list of solid balance sheet and fundamentals (6 results).
What Is Linamar's Investment Narrative?
To be comfortable owning Linamar, you need to buy into a fairly straightforward idea. This is a capital intensive manufacturer that lives or dies on execution, pricing discipline and how well it fills its plants. The latest quarter fits that story. Sales reached CA$3,076.2m, yet quarterly net income and EPS were lower than a year earlier, so near term, the key question is whether record North American and China program wins can offset customer shutdowns and softer demand in parts of Mobility.
On the other side of the ledger, Linamar is still generating free cash flow and using it to repurchase shares under a renewed bid funded from existing cash. That combination of reinvestment in operations and capital returns is central to the bull case. In the short term, the main swing factors remain order stability in Industrial, customer production schedules in Mobility and how aggressively management leans into future tooling and capacity spending.
Even so, there is one operational pressure building in the background that could matter far more than the buyback story if it breaks the wrong way.
There's only one way to know the right time to buy, sell or hold Linamar. Head to Simply Wall St's company report for the latest analysis of Linamar's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly CA$111 to about CA$193, so community views on Linamar vary widely. That gap meets fresh information today as you weigh stronger year to date earnings, record program wins and an extended buyback, against the risk that customer shutdowns keep pressuring reported profitability. Explore those contrasting viewpoints.
Explore another Linamar fair value estimate, including one that suggests it could be worth just CA$111.00.
Reach Your Own Conclusion
Disagree with this assessment? Exceptional investment outcomes do not typically come from following the herd, so rely on your own judgment.
- A great starting point for your Linamar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Linamar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which is designed to make it easier to review Linamar's overall financial position at a glance.
Looking For More Investment Ideas Beyond Linamar?
If Linamar has sharpened your focus on balance sheets, cash generation and capital returns, you might consider broadening that search with a few targeted stock lists that apply similar discipline to a wider opportunity set.
- For investors who want potential upside paired with healthier fundamentals than typical micro caps, review a curated group of 19 elite penny stocks with strong financials that already show stronger financial underpinnings.
- If value and quality matter equally to you, look at businesses combining solid balance sheets with attractive fundamentals through this focused list of solid balance sheet and fundamentals (6 results).
- Income focused readers can concentrate on companies offering higher yields with an emphasis on resilience by reviewing a dedicated 3 dividend fortresses built around dividend durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com