


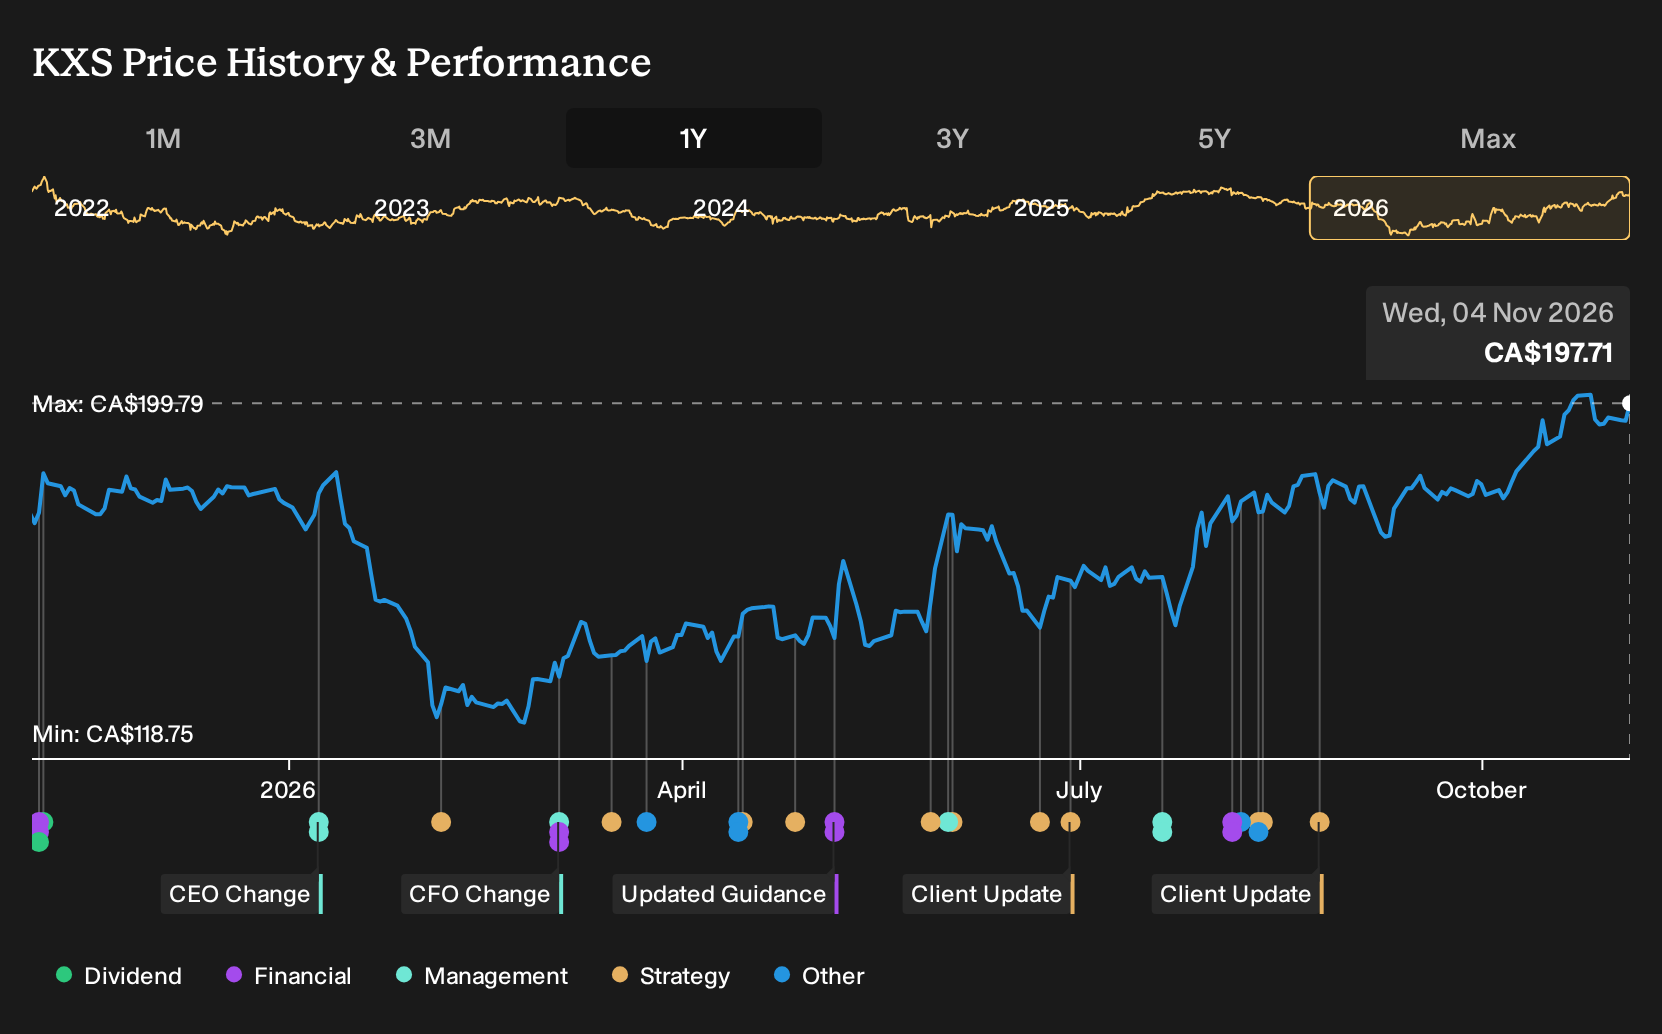
- Kinaxis reported third quarter 2026 sales of US$160.26 million and net income of US$20.1 million, with both basic and diluted earnings per share from continuing operations higher than the same period in 2025.
- The company paired these stronger earnings with raised full year 2026 guidance and new Agentic AI and optimization features on its Maestro platform, which signaled management confidence in demand for its supply chain planning software.
- We will now look at how Kinaxis's stronger earnings and higher 2026 guidance could reshape the broader investment narrative around the business.
Scan Kinaxis alongside a curated set of AI-focused peers by checking out the 40 profitable AI stocks that aren't just burning cash that pair recurring revenue with real earnings power.
Kinaxis Investment Narrative Recap
For a shareholder, the big idea with Kinaxis is belief that Maestro and its AI agents stay relevant as supply chains get more complex and more automated. The latest quarter shows Kinaxis producing higher sales and net income compared with 2025, which supports that narrative. The short term swing factor still looks like SaaS demand and deal timing, rather than one quarter of stronger earnings on its own.
The raised 2026 guidance suggests management currently sees enough contracted work and pipeline to support that outlook. The key operational risk is that heavy investment in AI, Forward Deployed Engineering and partner delivery does not translate into the recurring usage needed to justify that spend. Any wobble in win rates or expansion deals could expose that tension quickly.
The most relevant update here is the launch of new Agentic AI and optimization capabilities on the Kinaxis Maestro platform, paired with record remaining performance obligations above US$1b. That combination ties product depth directly to long term revenue visibility, since RPO gives a view on contracted work still to be recognized.
For catalysts, the question is whether these AI features help Kinaxis convert more customers from pilots and limited use cases into broad orchestration deployments. That would matter for sustaining SaaS growth, supporting margins as partner led delivery scales, and reducing the risk that high R&D spend outpaces the monetization of Maestro Agents and related services.
What The Kinaxis Consensus Is Pricing In
Kinaxis' narrative projects revenues of $861.0 million and earnings of $109.8 million by 2029. That path assumes revenue expands by 12.6% each year and earnings rise by about $22.8 million from $87.0 million today.
Uncover why Kinaxis' fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Kinaxis watchers focus on FedRAMP as the swing factor. Before this earnings release, the bullish cohort was modeling about US$897.8 million in revenue and US$130.2 million in earnings by 2029. That is a much richer AI orchestration story than consensus. These fresh results may prompt both narratives to adjust, so consider a range of views before forming your own.
Explore 4 other Kinaxis fair value estimates, including one that suggests as much as 60% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kinaxis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kinaxis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kinaxis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kinaxis?
Once you have a view on Kinaxis, it can help to compare the opportunity set with other businesses that share some of the qualities you care about, whether that is value, resilience, or growth supported by solid fundamentals.
- If you want potential value combined with quality fundamentals, scan the 5 high quality undervalued stocks that could offer a more appealing balance between price and business strength.
- For readers who care most about stability, stress test your downside with a 9 resilient stocks with low risk scores that screens for companies with more resilient profiles.
- If balance sheet strength is your first filter, start with a list of solid balance sheet and fundamentals (6 results) to focus on businesses that pair financial robustness with fundamental support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com