


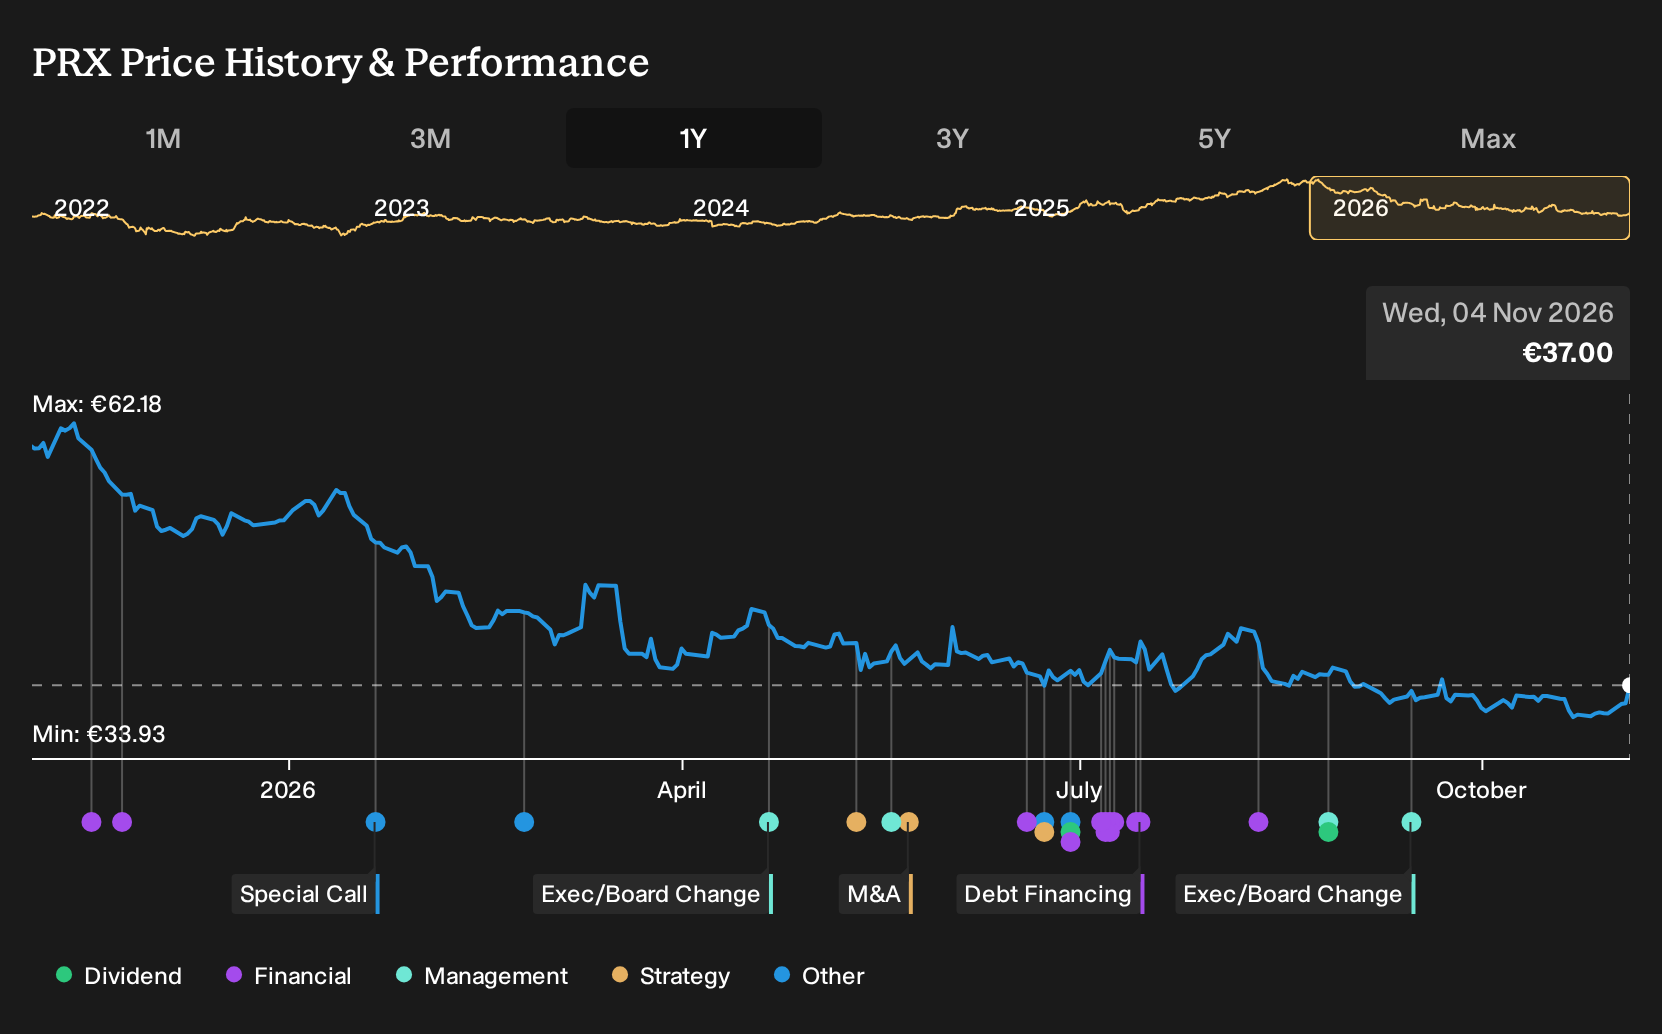
If you bought Prosus on the belief that smartphone adoption, AI and digital payments in emerging markets would reward patience, the result has been painful. For Prosus shareholders, the loss over the past year was 38.1%, including dividends. If that outcome is forcing you to rethink the original logic, the key question is this: which parts of the bullish and bearish 2025 assumptions were simply stretched, and which were never realistic given Prosus’s Tencent exposure and regulatory overhang?
This theme extends beyond Prosus. See which of 53 AI infrastructure stocks may still merit a closer look.
The Two Prosus Stories Investors Had To Weigh
The shares cost €59.75 at the start of the period, and investors in Prosus were basically choosing between two very different but credible stories.
On the bullish side, the narrative argued that smartphone adoption, AI tools and digital payments in emerging markets would compound together. That camp pointed to a Fair Value of €70.72, a notional target price based on assumptions that Prosus could use AI and ecosystem synergies to lift margins and cash generation while building multi billion euro digital finance streams.
The bearish view focused on Tencent reliance and regulation in China and the EU. Supporters of this scenario saw a Fair Value of €37, reflecting worries that tighter rules, digital nationalism and uncertain profitability at non Tencent platforms could continue to compress margins and limit the benefit from any revenue growth.
What The Prosus Evidence Put To The Test
Prosus rolling out its ToqanClaw no code AI platform and Zapia assistant to millions of partners supported the bullish idea that AI tools could deepen its ecosystem. At the same time, Goldman Sachs highlighting valuation questions, pressure at iFood from a Brazil price war, and potential Tencent sell downs kept the cautious case alive. Overall, the evidence cut both ways.
The lesson is simple. When a thesis leans on ecosystem AI and asset recycling, you track segment EBITDA, cash flow and any required asset sales rather than just headline revenue.
What You Are Paying For In Prosus Today
Prosus now trades at €36.99. The selected Narrative sees a Fair Value above that price, rooted in the idea that the operating portfolio can speak more loudly in the numbers than the Tencent stake alone.
The crux is whether Prosus can turn its AI tools and cross sell playbooks into sustained, higher margin ecosystem revenue without letting competitive spending hold EBITDA flat for too long.
"Some analysts expect Prosus to keep scaling its AI-first ecosystems in food delivery, classifieds and travel so that the group’s reported profitability and cash generation reflect the size of its operating platforms rather than just its Tencent stake. The main thing that would need to go right is that Prosus continues to use its AI tools and cross-sell playbooks to grow high-margin ecosystem revenue in Latin America, Europe and India while keeping competition-driven investment from diluting group EBITDA for too long."
One Narrative disagrees with today's price. → See where this Narrative says Prosus should trade
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 25% below our estimate - uses expanded high value capacity and backlog to absorb outsourced development mandates.
- Company 2 - 50% below our estimate - scales an asset light lodging network while directing guests into a retail marketplace.
- Company 3 - 22% below our estimate - sells liquid cooling and power systems that data centre builders adopt for dense AI workloads.
That is three of the list. See every one of the 194 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com