


Plug Power trades at US$1.46 after a long stretch of weak returns, which raises a straightforward question for anyone still watching the stock: Is the current share price sensibly tied to the revenue the hydrogen fuel cell specialist is generating today and is expected to produce over time?
- Over the past 5 years the share price has fallen 96.4%, which puts the entire valuation story under pressure and makes the link between sales and market value especially important.
- Recent trading has been highly sensitive to policy signals and sector news, with clean energy optimism and concern around hydrogen demand both flowing quickly into expectations for Plug Power's future sales and the timing of any path toward stronger cash generation.
- Your read on Plug Power is one view; the desks covering it have another. See what analysts think Plug Power's shares could be worth.
For investors, the debate is whether Plug Power's current market value is appropriately anchored to its sales profile or whether the stock price has drifted away from what its revenue base can reasonably support.
If you want more context around Plug Power and the recent sector swings, it can help to compare it with 41 power grid technology and infrastructure stocks.
Does Plug Power Look Pricey on Sales?
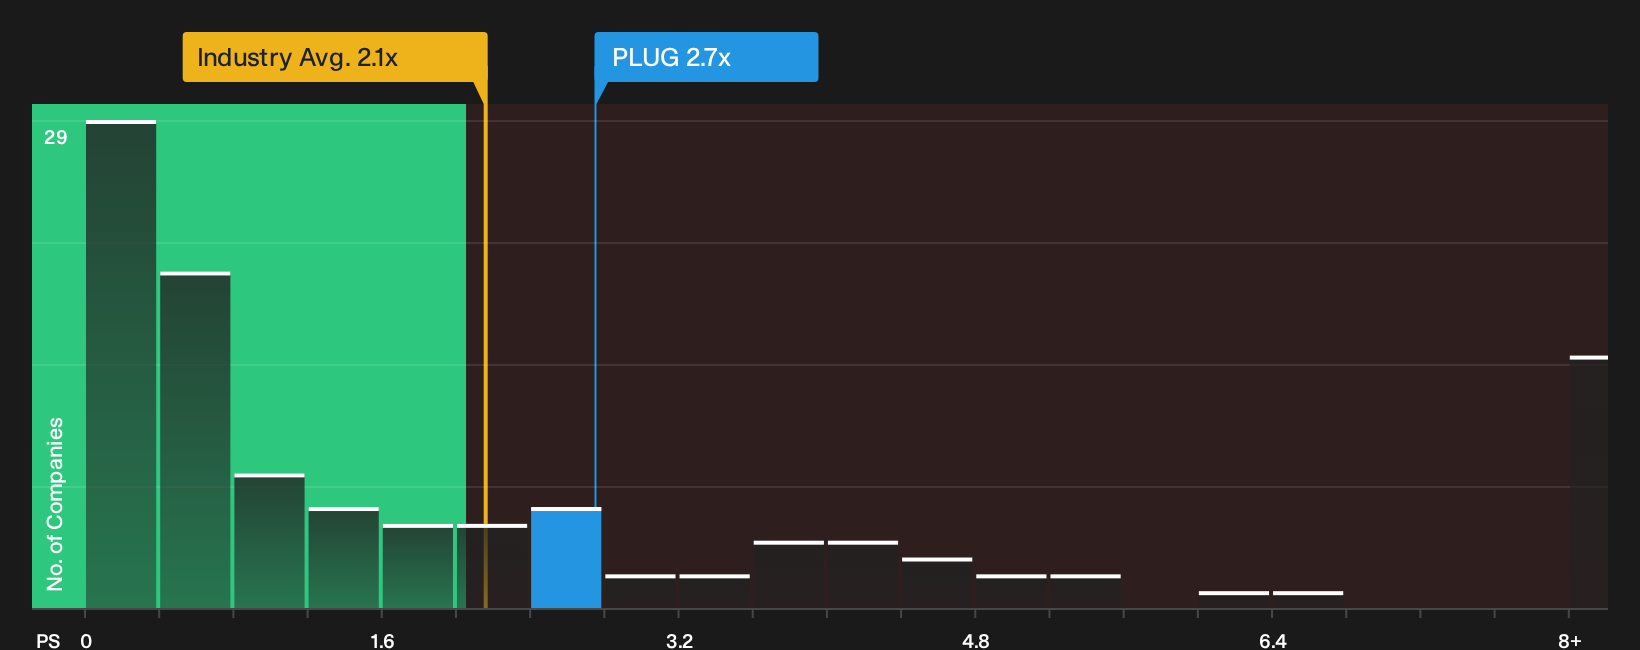
For Plug Power, the P/S ratio matters more than P/E because the business is still loss making and investors tend to anchor expectations to revenue rather than earnings. The stock trades on a P/S of about 2.7x, which sits above both the Electrical industry average of roughly 2.1x and the peer group around 1.7x. That means each dollar of Plug Power's sales is carrying a richer price tag than the typical company in its space.
Recent swings around election outcomes and clean energy sentiment have helped lift interest in Plug Power. Yet the current P/S still screens as overvalued relative to the fair multiple implied by its risk profile and cash flow track record. The internal fair ratio model heavily penalises the depth of recent free cash flow losses. As a result, the gap is better read as a warning that the shares look very expensive on this framework rather than a precise pricing target. Investors weighing the stock against other Electrical names may want to think hard about how much optimism they are willing to pay for on a sales basis. Explore the numbers behind Plug Power's P/S valuation.
The Plug Power Narrative: What Would Justify Today's Price?
Plug Power Narratives on Simply Wall St pick up where this pricing puzzle leaves off and explain what kind of revenue growth, margin path, and earnings profile would need to occur for the stock to trade materially above or below today's level. These narratives are available on the Community page so you can see different viewpoints side by side. Each narrative treats fair value as a thesis about Plug Power's business that you can track over time rather than a one off snapshot.
Bullish and bearish Plug Power holders are reading the same cost reset and project pipeline, then reaching sharply different conclusions on value.
Bull case: 57% undervalued
"Company wide cost actions under Project Quantum Leap, including the shift from very negative to roughly breakeven gross margin in recent quarters, OpEx reductions of about 50% and lower cash usage, point to a structural reset in Plug Power’s cost base..."
Discover why this Narrative puts Plug Power at 57% undervalued.
Bear case: 95% overvalued
"The cancellation of the 100 MW green hydrogen plant at the Port of Antwerp after the loss of a US$1.66b loan guarantee, together with the related €13.6 million write off, shows that large European projects can still fail at a late stage..."
Explore why this Narrative puts Plug Power at 95% overvalued.
Plug Power's share price is only one piece of the decision
Before making any call on Plug Power, it is worth asking who is steering the business, how their incentives are structured, and whether that pay design truly lines up with your interests. See who runs Plug Power and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com