


Rigetti Computing (RGTI) is back in focus after investors latched on to two catalysts at once: an approaching November 10 earnings release and fresh quantum performance results from partner FirstQFM.
Rigetti Computing’s recent share price tells a mixed story. The stock has retreated about 26% over the past 30 days and roughly 53% year to date on a share price basis, yet the three year total shareholder return is close to 10x. This keeps long term holders focused on whether the latest earnings and quantum milestones signal renewed momentum or a reset in risk expectations.
Scan quantum computing peers that are moving on similar catalysts and see how Rigetti Computing compares with 25 quantum computing stocks in terms of momentum, contracts, and commercialization progress.
Rigetti Computing now trades at a steep discount to analyst targets after a sharp pullback. Is this a discounted opportunity, or a market warning that near term enthusiasm has run ahead of fundamentals?
Most Popular Narrative: 30% Undervalued
Rigetti Computing last closed at $11.21, while the most followed narrative assigns a fair value of $16.00. This points to a sizable valuation gap that hinges on execution in both hardware performance and commercial traction.
Rigetti wins only if it proves that its architecture can scale and that customers care enough to buy into that path early. The most important technical-commercial update is that Cepheus-1-108Q is now generally available, including through Rigetti QCS and Amazon Braket, and management is targeting 99.5% median two-qubit gate fidelity by the end of 2026.
See why 43 investors see Rigetti Computing as 30% undervalued.
According to HedgeY, the narrative treats Rigetti Computing as a high-risk quantum hardware option where current revenue is still small. However, the fair value estimate leans on the potential of systems like Cepheus-1-108Q, existing cash of $569 million with no debt, and the early evidence of demand from contracts such as Novera shipments and the $8.4 million C-DAC order.
The same thesis flags the disconnect between the business scale and earlier market values. It points out that full-year 2025 revenue of $7.1 million sat against a multi billion dollar market cap, so the 29.9% discount to the $16.00 narrative fair value reflects both optimism about technical milestones and awareness that Rigetti is still unprofitable, with losses widening over the past five years and forecasts indicating it may remain loss making over the next three years.
Result: Fair Value of $16.00 (UNDERVALUED)
Still, the Rigetti Computing story is fragile, as heavy ongoing losses and a valuation tied to ambitious hardware milestones both leave little room for disappointment.
Find out about the key risks to this Rigetti Computing narrative.
Another View on Rigetti Computing’s Valuation
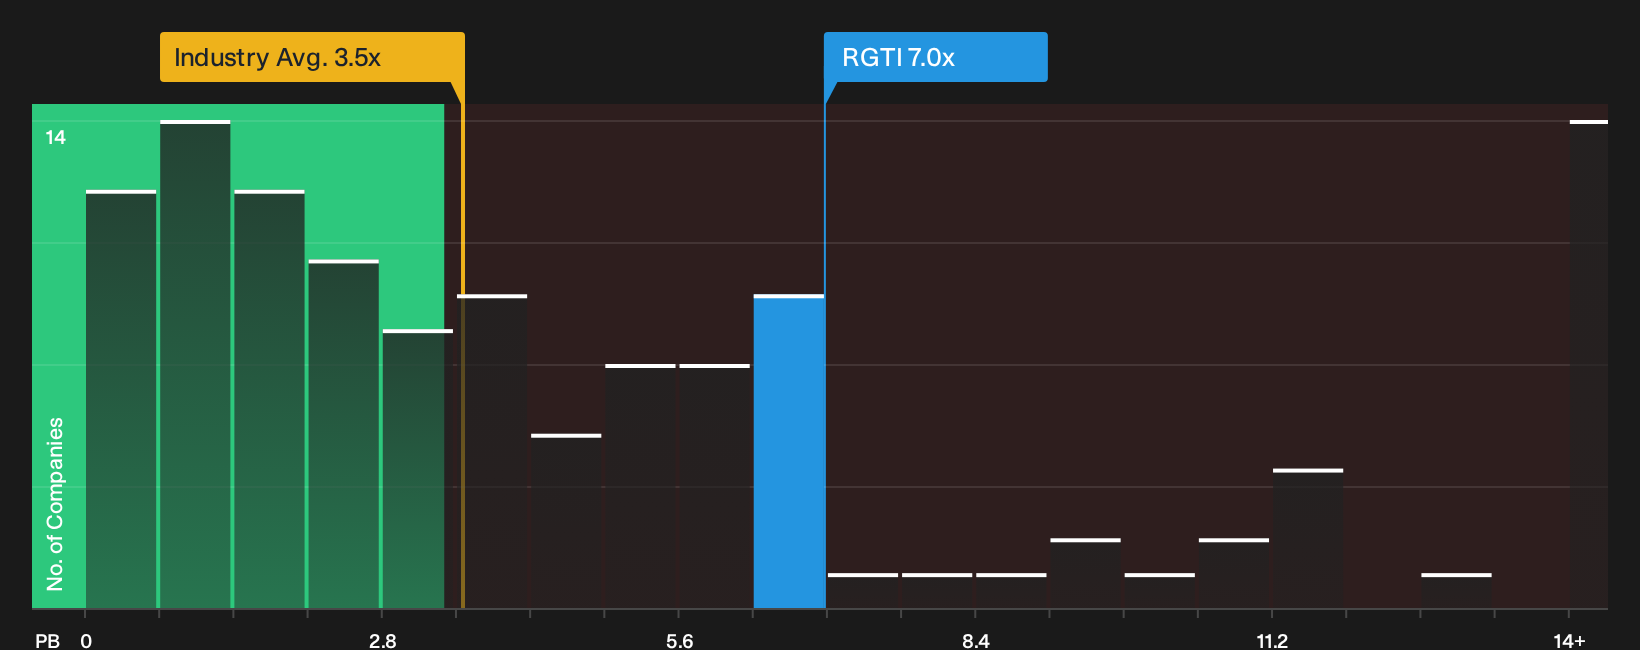
The first narrative framed Rigetti Computing as trading below a $16.00 fair value, yet the current market snapshot tells a different story. The stock carries a P/B of 7x while the US Semiconductor peer group averages 3.5x. That kind of gap points to a richer tag, not an obvious bargain.
This higher multiple means investors today are paying almost double the sector’s book value yardstick for a business that is still loss making and not expected to turn profitable within three years. The question is simple: Is that premium really compensation for quantum potential, or just extra valuation risk if progress stalls?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Unsure whether Rigetti Computing’s recent swings reflect opportunity or excess risk and want to move quickly rather than watch from the sidelines? Consider both sides of the story and review the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Rigetti Computing?
If Rigetti Computing has you thinking harder about risk, reward, and timing, use that momentum to widen your opportunity set with focused screeners.
- Target resilient performers by scanning a 31 resilient stocks with low risk scores that filters for businesses with lower risk profiles and steadier characteristics than high volatility quantum stocks.
- Hunt for potential mispriced opportunities by running a 35 high quality undervalued stocks that surfaces companies where quality fundamentals and current pricing appear out of sync.
- Anchor your watchlist with balance sheet strength by checking a list of solid balance sheet and fundamentals (24 results) that highlights firms with healthier debt, liquidity, and capital structures.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com