


Rio Tinto Group (LSE:RIO) put its bauxite business in focus with a planned US$1.9b spend on the Kangwinan project in Queensland, aimed at sustaining Weipa output as older mines wind down.
The Rio Tinto share price has slipped over the past quarter, with a 30 day share price return of 13.7% and a 90 day share price return of 16.8% in the red. However, the 1 year total shareholder return of 23.3% and 5 year total shareholder return of 96.9% point to momentum that has built over longer horizons as investors react to projects like Kangwinan alongside other recent updates.
Scan how Rio Tinto Group compares with other miners repositioning for long-term resource supply and capital discipline by reviewing the hand picked 33 best rare earth metal stocks alongside this Kangwinan update.
Short term weakness and a US$1.9b bauxite commitment put Rio Tinto at an awkward crossroads. Does it make more sense to step in after this pullback or wait for a cleaner entry as the valuation case unfolds next?
Most Popular Narrative: 18% Undervalued
Against a last close of £62.01, the most followed narrative sees Rio Tinto Group’s fair value closer to £75.37. This puts the Kangwinan decision inside a bigger story about productivity, copper and battery materials shaping the long run cash profile.
The approach to capital allocation and portfolio reshaping is evolving as Rio Tinto Group progresses plans to release US$5b to US$10b of cash from its asset base and commits US$1.9b to the Kangwinan bauxite project in Queensland with an expected 22% internal rate of return. This can influence future free cash flow, return on capital and capacity to fund dividends.
See why 294 investors see Rio Tinto Group as 18% undervalued.
Result: Fair Value of £75.37 (UNDERVALUED)
Still, the narrative of Rio Tinto Group can be knocked off course by ESG disputes or legal actions that lift costs and slow key projects such as Simandou.
Find out about the key risks to this Rio Tinto Group narrative.
Another View: What Rio Tinto’s P/E Is Really Saying
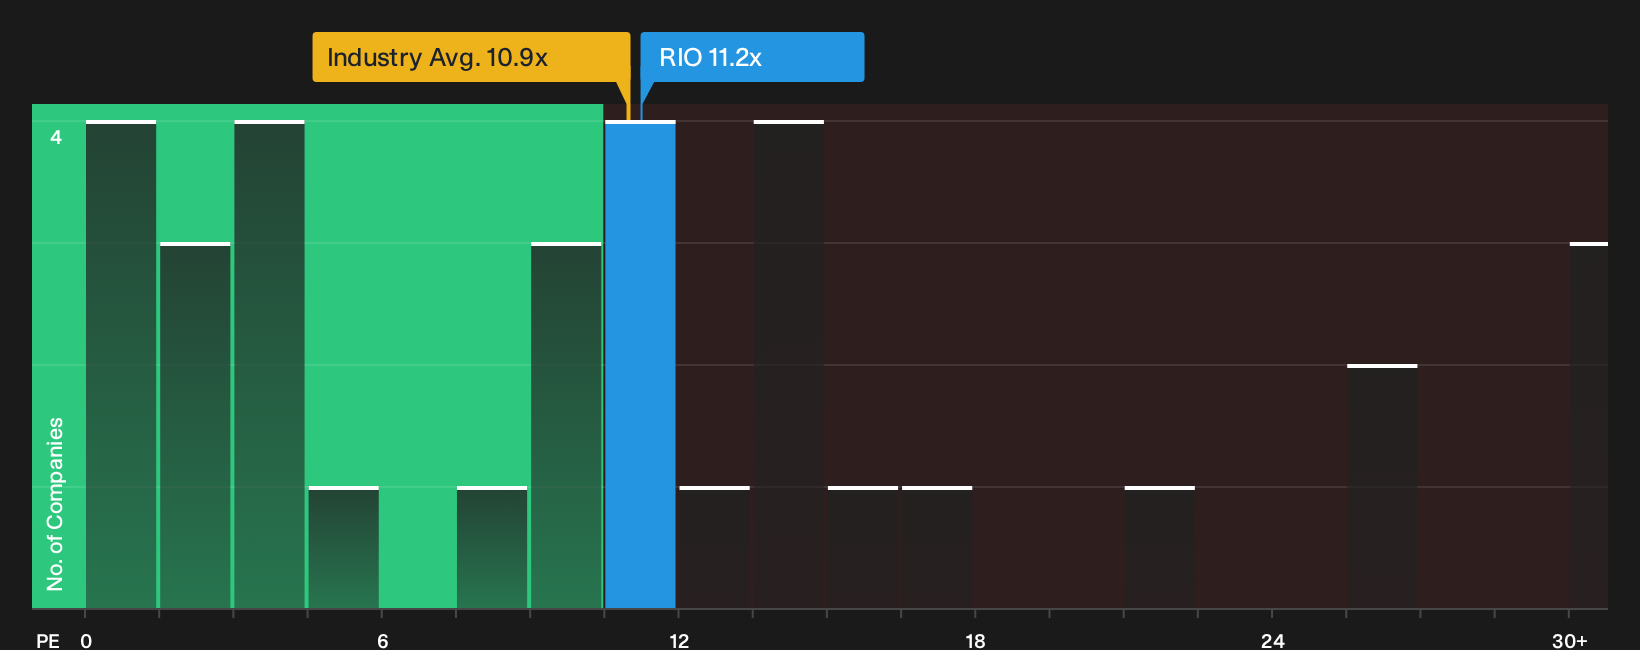
The DCF style fair value narrative pegs Rio Tinto Group near £75.37, yet the current share price of £62.01 is not the only signal investors look at. On simple P/E terms of 11.2x, the stock is described as slightly expensive versus the UK Metals and Mining average of 10.9x, yet cheaper than a 16.5x peer average and well below a fair ratio of 18.7x. That mix of modest premium to the sector, discount to peers and gap to a fair ratio raises a practical question for you: Is the market underpricing quality or correctly charging for risk?
See what the numbers say about this price in more detail by reviewing the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data can be useful if you move quickly and test the story against your own expectations. To weigh up both the concerns and the potential upside in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more Rio Tinto investment ideas?
If Rio Tinto has sharpened your focus on quality, do not stop here. Fresh, data driven ideas can quickly shift how you think about your next move.
- Target financial resilience by scanning companies with robust cash and low debt through the list of solid balance sheet and fundamentals (10 results).
- Hunt for better value by reviewing the 14 high quality undervalued stocks that combine strong fundamentals with pricing that still looks reasonable.
- Prioritise steadier rides by checking the 5 resilient stocks with low risk scores that score well on resilience and business quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com