


Globant (NYSE:GLOB) has rolled out Glob.AI OS, a new governance layer for its AI-Native Services Platform. The company aims to make enterprise AI deployment more controllable, contextual and scalable across large organizations.
Recent trading has been punchy for Globant, with the share price up 4.96% over the last day, 11.00% across the past week and 34.38% over the past month. However, year to date the share price return is still down 23.83% and the 1-year total shareholder return has declined 20.20%, extending a multi-year slide where total shareholder return over 3 and 5 years has fallen 73.92% and 85.49% respectively. As a result, the latest Glob.AI OS launch and the October 2026 credit agreement revision look more like a burst of renewed momentum than a confirmed long-term turnaround.
Scan Globant’s AI push against a curated field of peers by reviewing the 53 AI infrastructure stocks that is already attracting attention from investors looking at the same theme.
Globant’s rebound leaves the stock trading below both analyst targets and an estimate of fair value, yet years of weak shareholder returns still hang over it. Is that discount a margin of safety or a warning sign?
Most Popular Narrative: 7% Undervalued
Globant’s most followed narrative pegs fair value at about $51.59, a touch above the latest $48.04 close. This frames the recent bounce as a partial catch up rather than euphoric overreach.
Globant is pushing a shift from traditional headcount-based delivery to AI-native Glob.AI and AI Pods, with reported Glob.AI ARR moving from US$32.8 million in March 2026 to US$52.8 million in June 2026. Management is now talking about at least US$110 million in ARR by year end, and AI Pods are approaching roughly 4% of total revenue. Together, these factors point to a growing base of subscription-like revenue that can lift earnings visibility.
See why 56 investors see Globant as 7% undervalued.
Result: Fair Value of $51.59 (UNDERVALUED)
Still, subdued revenue growth and ongoing legal scrutiny of Globant’s past disclosures could easily unsettle that 7% undervalued narrative if these issues persist.
Find out about the key risks to this Globant narrative.
Another View: DCF Puts a Different Price on Globant
The first narrative leans on fair value around $51.59 for Globant. A second lens tells a tougher story. Our DCF model points to future cash flows worth about $40.51 per share, which sits below the recent $48.04 price and presents the stock as overvalued on that basis. Which lens do you consider more relevant when real cash generation is the focus?
Look into how the SWS DCF model arrives at its fair value.
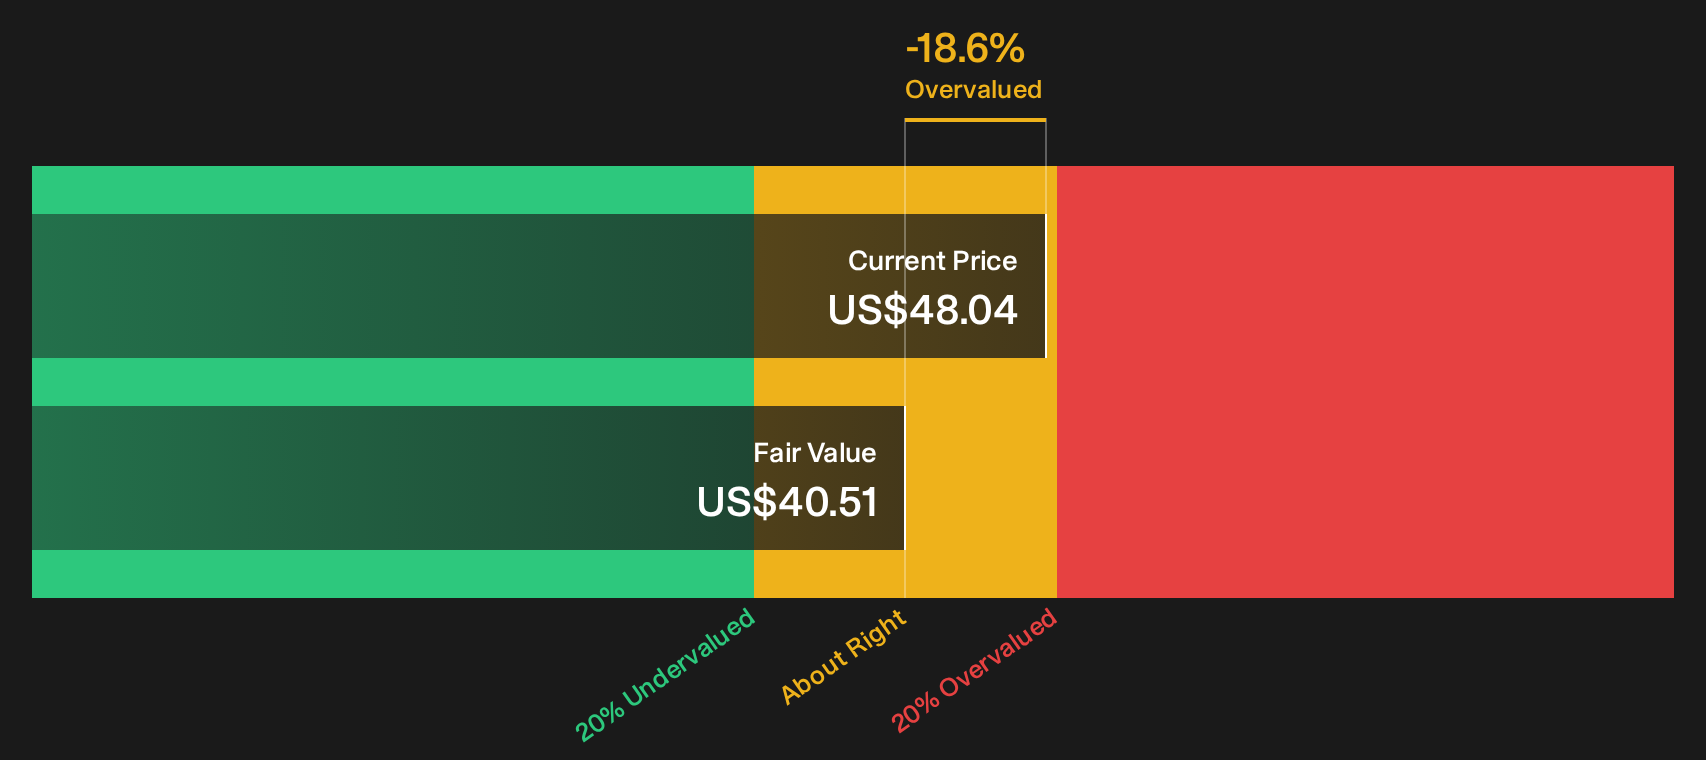
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Globant for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Signals on Globant appear mixed so far. If this combination of risks and potential rewards seems finely balanced, it may be useful to review the 4 key rewards and 2 important warning signs.
Looking for more Globant sized ideas?
If Globant has you rethinking where the real opportunities might be, do not stop here. Use powerful screeners to surface ideas before everyone else does.
- Target potential mispricings by running a focused search across 35 high quality undervalued stocks that pair quality fundamentals with compressed expectations.
- Prioritise resilience by filtering for companies on the list of solid balance sheet and fundamentals (24 results) so you are not relying solely on story or sentiment.
- Get ahead of the crowd by scanning the 19 high quality undiscovered gems and lining up ideas the broader market may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com