


Cimpress (CMPR) has reported first quarter results for the period ended September 30, 2026, with sales of US$934.05 million and a shift from prior-year profit to a net loss of US$2.67 million.
The first quarter update has landed against a choppy backdrop for Cimpress, with the share price up 7.14% on the day to US$63.32 but down 17.07% over 30 days and 34.39% over 90 days. The 1 year total shareholder return has slipped 2.16% and the 5 year total shareholder return is down 27.29%, pointing to fading momentum despite the latest single-day bounce as investors reassess both earnings risk and the longer term thesis.
Scan beyond Cimpress and line up other potential opportunities using our curated list of 35 high quality undervalued stocks that pair balance sheet strength with solid cash generation.
Cimpress just jumped 7.14% in a day, yet still trades well below both recent levels and the analyst price target near US$105. Where does fair value land inside that gap between market price and estimated range?
Most Popular Narrative: 40% Undervalued
Cimpress closed at $63.32 compared with a widely followed fair value narrative of $105.50. This puts a wide gap between the current quote and what that framework suggests the business might be worth using a 9.21% discount rate.
The main factor that needs to work in Cimpress's favor is successfully turning its current wave of efficiency projects, AI deployment and shared manufacturing investments into the cost savings, EBITDA growth and free cash flow conversion that management is targeting through fiscal 2028.
The current valuation indicates that the market is not fully crediting Cimpress for its stated targets of at least $615 million of adjusted EBITDA, roughly 45% free cash flow conversion and lower net leverage by fiscal 2028. These factors could allow for share price appreciation if those outcomes are delivered.
See why 3 investors see Cimpress as 40% undervalued.
Result: Fair Value of $105.50 (UNDERVALUED)
Still, the Cimpress narrative could be challenged if efficiency projects fail to deliver the planned US$70 million to US$80 million in savings or if higher value categories cannot offset pressure in legacy print.
Find out about the key risks to this Cimpress narrative.
Another View On Cimpress Valuation
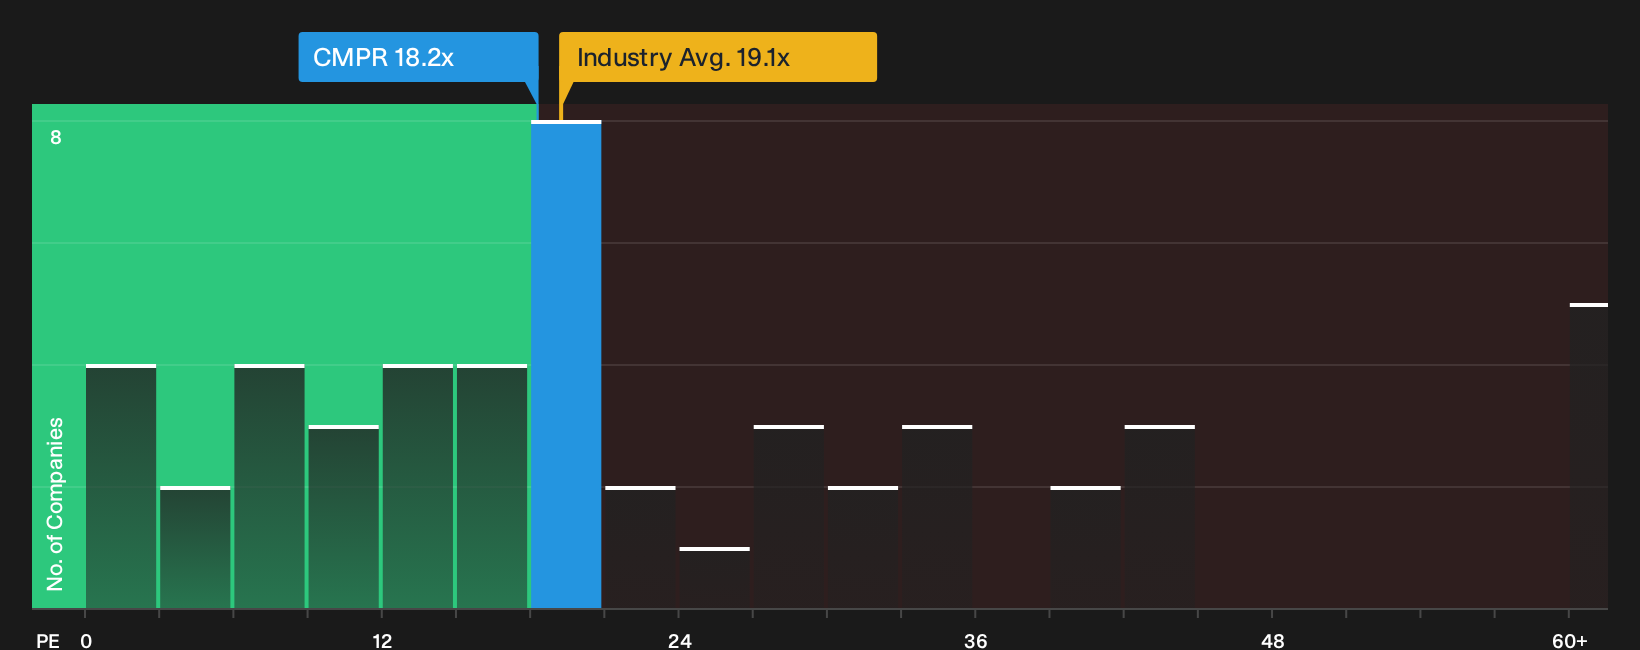
The first narrative presents Cimpress as materially undervalued relative to a US$105.50 fair value that is based on earnings and margin forecasts. Another perspective looks at the current P/E of 18.2x versus peers at 14.6x and a fair ratio of 20.9x. This implies investors already pay a premium to the sector while the multiple still sits below the level suggested by the ratio model. Is that a safety margin or a warning that expectations are already demanding?
For a closer look at how this earnings multiple compares with peers and how the fair ratio model estimates it could change over time, take a moment to review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Cautious or optimistic about Cimpress after these results? The fastest way to cut through the noise is to inspect the data yourself and stress test the assumptions that matter most to you. To weigh the tension between potential upside and the issues investors are worrying about, start with the 3 key rewards and 2 important warning signs.
Looking for more Cimpress-sized investment ideas?
If Cimpress has sharpened your focus on valuation and risk, do not stop here. The next move is comparing it with other opportunities that fit your criteria.
- Spot potential value gaps before the crowd by scanning the 35 high quality undervalued stocks and lining up businesses with both quality and mispriced expectations.
- Prioritise resilience and sleep-better-at-night positions using the 31 resilient stocks with low risk scores so you are not relying on a single story to carry your portfolio.
- Hunt for lesser-known opportunities with solid fundamentals through the 19 high quality undiscovered gems and avoid kicking yourself later for missing them early.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com