


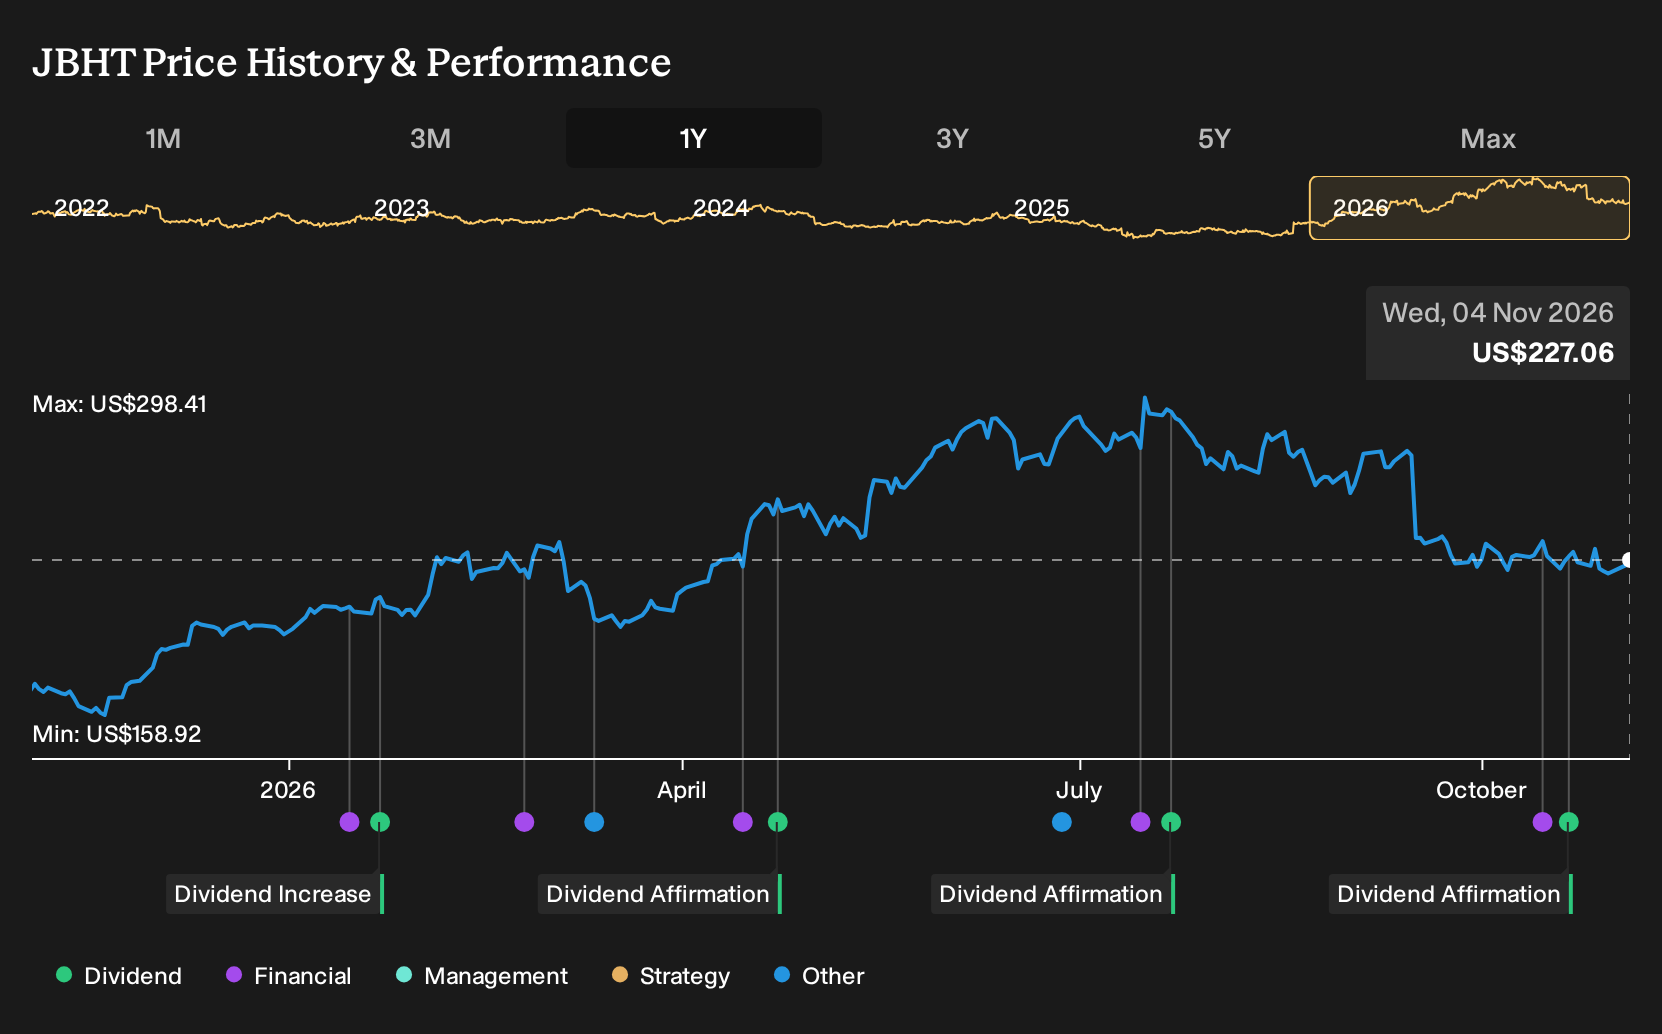
- Rosen Law Firm has begun investigating potential securities claims against J.B. Hunt Transport Services after allegations that prior public statements about business conditions were materially misleading, following the firm’s earlier warning that Q3 earnings would be pressured by higher recruiting, advertising, onboarding, training and sign-on bonus costs.
- The legal probe puts a spotlight on J.B. Hunt Transport Services’s labor related expenses and disclosure practices. These sit alongside existing cost headwinds and could affect how investors assess the durability of its operating model and risk profile.
- We will now look at how J.B. Hunt Transport Services' broader investment narrative may shift as this securities investigation unfolds around its guidance.
Broaden your watchlist by comparing J.B. Hunt Transport Services with a curated 31 resilient stocks with low risk scores that may better align with your comfort regarding legal, earnings, and cost-related risks.
J.B. Hunt Transport Services Investment Narrative Recap
To own J.B. Hunt Transport Services, you need to be comfortable with a story built on intermodal scale, Dedicated contracts, and ongoing cost discipline. The latest legal investigation focuses on whether prior comments around labor costs and business conditions were accurate. That matters mainly because driver, recruiting, and fuel expenses are already pressuring near term earnings guidance.
The key short term swing factor is whether productivity tools and prior structural cost cuts can offset higher labor and fuel outlays. The biggest risk right now is that elevated cost inflation persists while legal scrutiny keeps sentiment cautious, without a clear operational relief valve in Q3 2026 and beyond. If that link breaks, the thesis weakens.
Recent news puts those upcoming investor conferences into sharper focus. J.B. Hunt Transport Services plans to appear at events hosted by Baird, Stephens, and Goldman Sachs, with presentations available live and in replay. That forum gives management a chance to walk through labor cost trends, the Q3 earnings pressure, and any process changes around disclosure.
For you as a shareholder or watcher, these sessions can matter more than usual. They may clarify how the freight network is performing, whether intermodal volumes and Dedicated economics still underpin the story, and how leadership frames the legal probe within its risk management. Execution on cost to serve efforts and the AI freight platform remains central to that message.
J.B. Hunt Transport Services' narrative projects US$16.7b revenue and US$1.1b earnings by 2029. This aligns with analysts factoring in 9.5% yearly revenue growth and about a US$425.5m earnings increase from US$674.5m today.
Uncover how J.B. Hunt Transport Services' fair value indicates a 24% potential upside to its current price, before enthusiasm around the discount starts to fade.
Exploring Other Perspectives
Some of the most optimistic analysts focus on tighter truckload capacity as a potential positive for J.B. Hunt Transport Services, arguing that firmer pricing could support their more bullish view. Before this legal investigation, that group was modeling revenue of about US$19.6b and earnings of roughly US$1.3b by 2029. Those expectations might now face a rethink, so consider this as one perspective among many rather than a definitive guide to what will happen next.
Explore 3 other J.B. Hunt Transport Services fair value estimates, including one that suggests as much as 37% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your J.B. Hunt Transport Services research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for J.B. Hunt Transport Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J.B. Hunt Transport Services' overall financial health at a glance.
Looking for more investment ideas beyond J.B. Hunt Transport Services?
If this J.B. Hunt Transport Services story has you rethinking concentration risk, it can help to widen the lens and compare it with other businesses that better fit your comfort level on balance sheets, dividends, and growth potential. The Simply Wall St Screener gives you a structured way to do that in a few minutes.
- For steadier balance sheets and cleaner financial footing, start with a curated list of solid balance sheet and fundamentals (24 results) that keeps the focus on resilience rather than headlines.
- If income is your priority, review a hand picked 5 dividend fortresses where higher yields pair with a focus on payout sustainability.
- To broaden the opportunity set with under followed ideas, scan a 19 high quality undiscovered gems that filters for quality fundamentals before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com