


Palantir Technologies (PLTR) has consistently delivered robust quarterly financial performance, and Q3 was no different. The company’s top-line growth rate continued to accelerate. Moreover, PLTR again raised the full-year outlook. Accelerating top-line performance and an upward revision to its full-year guidance highlight strong demand for its AI platform (AIP). Despite its solid growth, Palantir stock has struggled to rise.
One main reason is Palantir’s expensive valuation, which makes it hard for the stock to move higher even when the company delivers strong results. At the same time, a slowdown in total contract value (TCV) bookings has raised some concerns about future growth.
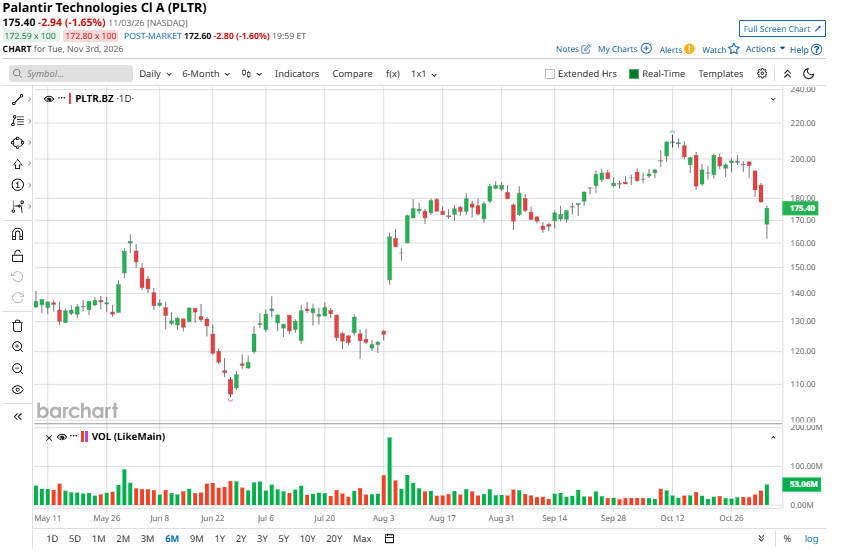
Palantir Delivers Solid Q3, Lifts Outlook
Palantir delivered an exceptionally strong third quarter, supported by accelerating revenue growth across its commercial and government businesses. Revenue exceeded $2 billion, up 96% year over year. The results highlight the growing adoption of the company’s AIP and its expanding role in enterprise and government operations.
The U.S. market remained a major growth driver, with revenue up 119% year over year. Growth among larger customers was equally encouraging. Revenue from the company's top 20 customers over the trailing 12 months increased 76% to an average of $146 million per customer, suggesting that existing customers are expanding their use of Palantir's products.
The commercial business was once again the bright spot. Revenue in this segment grew 113% year over year to $1.17 billion, while U.S. commercial revenue jumped 148% to $984 million. The number of U.S. commercial customers also increased 29% to 686. More importantly, U.S. commercial revenue exceeded U.S. government revenue for the first time. This marks a notable shift in the company's revenue mix.
Government business also remained strong, with revenue up 81% year over year to $1.15 billion. U.S. government revenue rose 96% to $953 million, supported by existing contracts and new project wins.
Following the strong performance, management raised its full-year 2026 revenue guidance midpoint to $8.53 billion, implying 91% year-over-year growth. U.S. commercial revenue is now expected to exceed $3.56 billion, representing at least 143% growth. The company also increased its adjusted operating income and adjusted free cash flow guidance.
Overall, Palantir's Q3 performance highlights strong AI demand, growing customer relationships, and improving financial strength. The higher guidance reflects sustained demand for its AIP.
Palantir’s TCV Bookings Momentum Moderates
Palantir delivered accelerated revenue growth in Q3, but its commercial Total Contract Value (TCV) bookings indicate moderating deal momentum compared with the exceptionally strong performance in the previous quarter.
PLTR secured $1.65 billion in commercial TCV bookings in Q3, representing 17% year-over-year growth. While the absolute booking value remained substantial, the growth rate decelerated considerably from Q2, when commercial TCV bookings reached $2.34 billion, marking an impressive 118% year-over-year increase.
A similar slowdown was evident in the U.S. commercial segment. Q3 U.S. commercial TCV bookings totaled $1.46 billion, up 11% year-over-year, compared with a record $2.13 billion in Q2, which represented 153% growth.
While Palantir's competitive positioning is strengthening as its AI platform is a leading solution for deploying large language models (LLMs), moderating TCV bookings warrant caution.
PLTR’s Valuation Is a Concern
Palantir’s quarterly financials show strong operating momentum, supported by robust revenue growth, rising customer spending, and successive upward revisions to guidance.
However, its extremely high valuation raises concerns. Trading at approximately 98.9x price-to-sales (P/S), Palantir commands an exceptionally high valuation premium, exceeding that of its industry peers and large mega-cap technology companies with substantial exposure to the expanding AI infrastructure market.
Even if Palantir continues to deliver strong financial results, sustaining its current valuation will require exceptionally high growth rates over an extended period. Consequently, the risk-reward is not attractive for PLTR stock, limiting the upside potential.
AI Momentum Is Strong, but Investors Should Remain Cautious
Palantir’s Q3 results reflect strong business momentum, driven by accelerating AI adoption, expanding commercial operations, and higher full-year guidance. However, the moderation in TCV bookings raises questions about the sustainability of its exceptional growth trajectory. More importantly, its lofty valuation leaves little room for execution setbacks or a slowdown in growth.
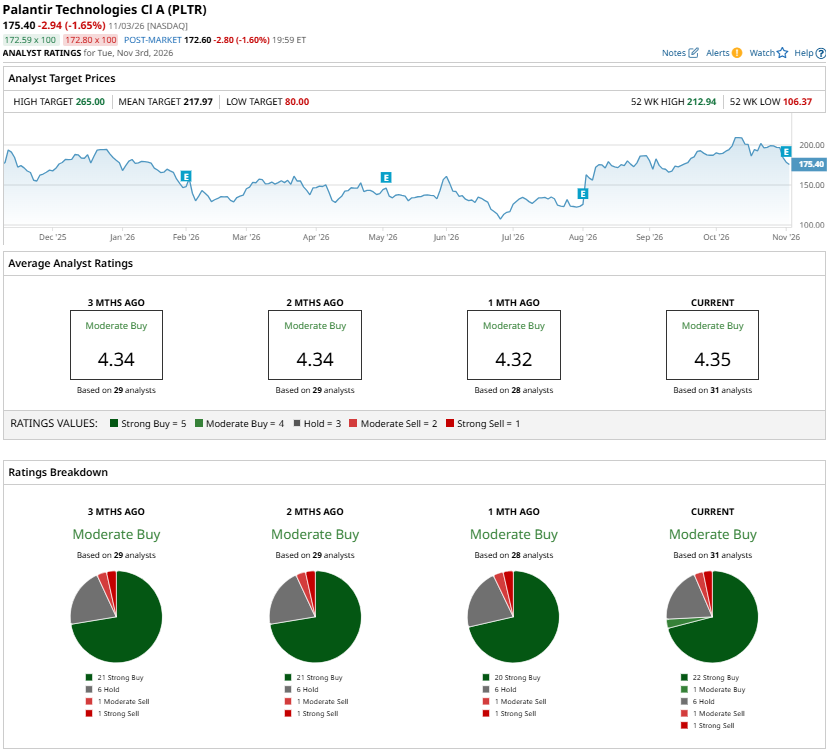
While Palantir’s long-term prospects remain promising, its current risk-reward profile appears unattractive. Analysts maintain a “Moderate Buy” consensus rating on PLTR stock.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.