


Stocks in the tech sector are experiencing a drawdown over the past month due to concerns over steep valuations, falling profit margins, surging debt, and higher capital expenditures.
The Nasdaq 100 index ($IUXX) is close to correction territory, which is defined as a pullback of 10% from all-time highs. Despite the ongoing volatility, analyst Dan Ives expects one cybersecurity stock to continue to outperform over the next 12 months and beyond. Let’s see why.
Why the AI Selloff Rattled Software Stocks
According to a Seeking Alpha report:
- The tech selloff began with two software names. Concerns about ServiceNow (NOW) and Fortinet (FTNT) brought back what traders call the SaaS apocalypse trade. Analysts and investors are worried that AI will disrupt products offered by SaaS (software-as-a-service) companies.
- Ives called the selling "indiscriminate," as even fundamentally strong companies with competitive moats were impacted in the sell-off. Ives is not calling every software stock a buy. But AI now drives a double-digit share of revenue at many of them, measured in annual recurring revenue (ARR).
- Ives explained that his team has read earnings call transcripts from software and cybersecurity companies back to early 2023. They tracked what executives said about AI demand and revenue, then compared it with cloud provider spending, estimates, bookings, and valuations.
- Notably, AI turns into software revenue on a delay. At the application level, that delay has run about two years, and Ives says the wait is now ending. While Wall Street has priced hyperscalers for the payoff, several SaaS companies are trading at cheaper valuations.
- However, Ives confirmed that the increase in bookings remains on schedule. For instance, the remaining performance obligations for Salesforce grew by almost 14% year over year in the last quarter. The metric measures contracted future sales and grew at the fastest pace since early 2023. ServiceNow grew its AI contract value by 65% year over year and raised its full-year AI target for the second time.
- Management comments on AI demand have cooled twice since 2023, in early 2024 and early 2026. After the 2024 warning, every one of those companies reported a bigger AI number within four quarters. The companies that got cautious this year have already done the same.
- That is why Ives stays bullish on software and cybersecurity into 2027. CrowdStrike is his cybersecurity pick. The other stocks on the list include Nvidia (NVDA) for chips, Microsoft (MSFT) for hyperscalers, Palantir Technologies (PLTR) for software, Apple (AAPL) for consumer internet, and Tesla (TSLA) for physical AI.
He says each one of these stocks sits where demand is contracted, funded, and accelerating.
CrowdStrike's AI Kill Switch Steps In
Earlier this week, at the Fal.Con Europe conference, CEO George Kurtz unveiled an AI Kill Switch, CNBC reported.
The tool lets security teams shut down rogue AI agents, stops them from restarting, and cuts off their network access. It is part of the Falcon Guardian platform and is available now.
Kurtz told CNBC's Jim Cramer that everyone is building agents, but "they never had the off button, and now they do." Kurtz called safe agents a massive market opportunity. He pointed to CrowdStrike's partnership with Anthropic. Enterprise customers, he said, told Anthropic they needed CrowdStrike before deploying AI.
Why CrowdStrike's Growth Numbers Back the Story
CrowdStrike’s CFO Burt Podbere told Citi's Global TMT Conference on Sept. 10 that the second quarter was the best in company history. Net new ARR rose to $333 million, up 51% from a year ago.
Ending ARR, the yearly value of CrowdStrike’s subscriptions at the close of the quarter, reached $5.8 billion, President Michael Sentonas said in early September.
Ending ARR reached $5.8 billion, President Michael Sentonas told Fal.Con. Podbere was optimistic about three growth engines, which include the cloud segment that grew 29% to $900 million. Next Gen SIEM (security information and event management) rose 60% to $700 million, while next-gen identity rose 33% to $600 million.
A licensing model called Flex helps CrowdStrike land bigger deals. Customers negotiate once, then add more products under the same terms. More than 2,900 customers use the licensing model. Moving a customer to Flex lifts average ARR 40%, up from 34% a year earlier. Customers also come back to buy more CrowdStrike products, on average eight months into their contract.
Management now believes the company can surpass $10 billion in ARR within fiscal 2030 and $20 billion within fiscal 2035.
At Fal.Con, Kurtz claimed customer demand remains robust. He cited Gartner figures showing AI spending rising from $2.67 trillion in 2026 to $5.95 trillion in 2030.
Is CrowdStrike Stock Still a Good Buy?
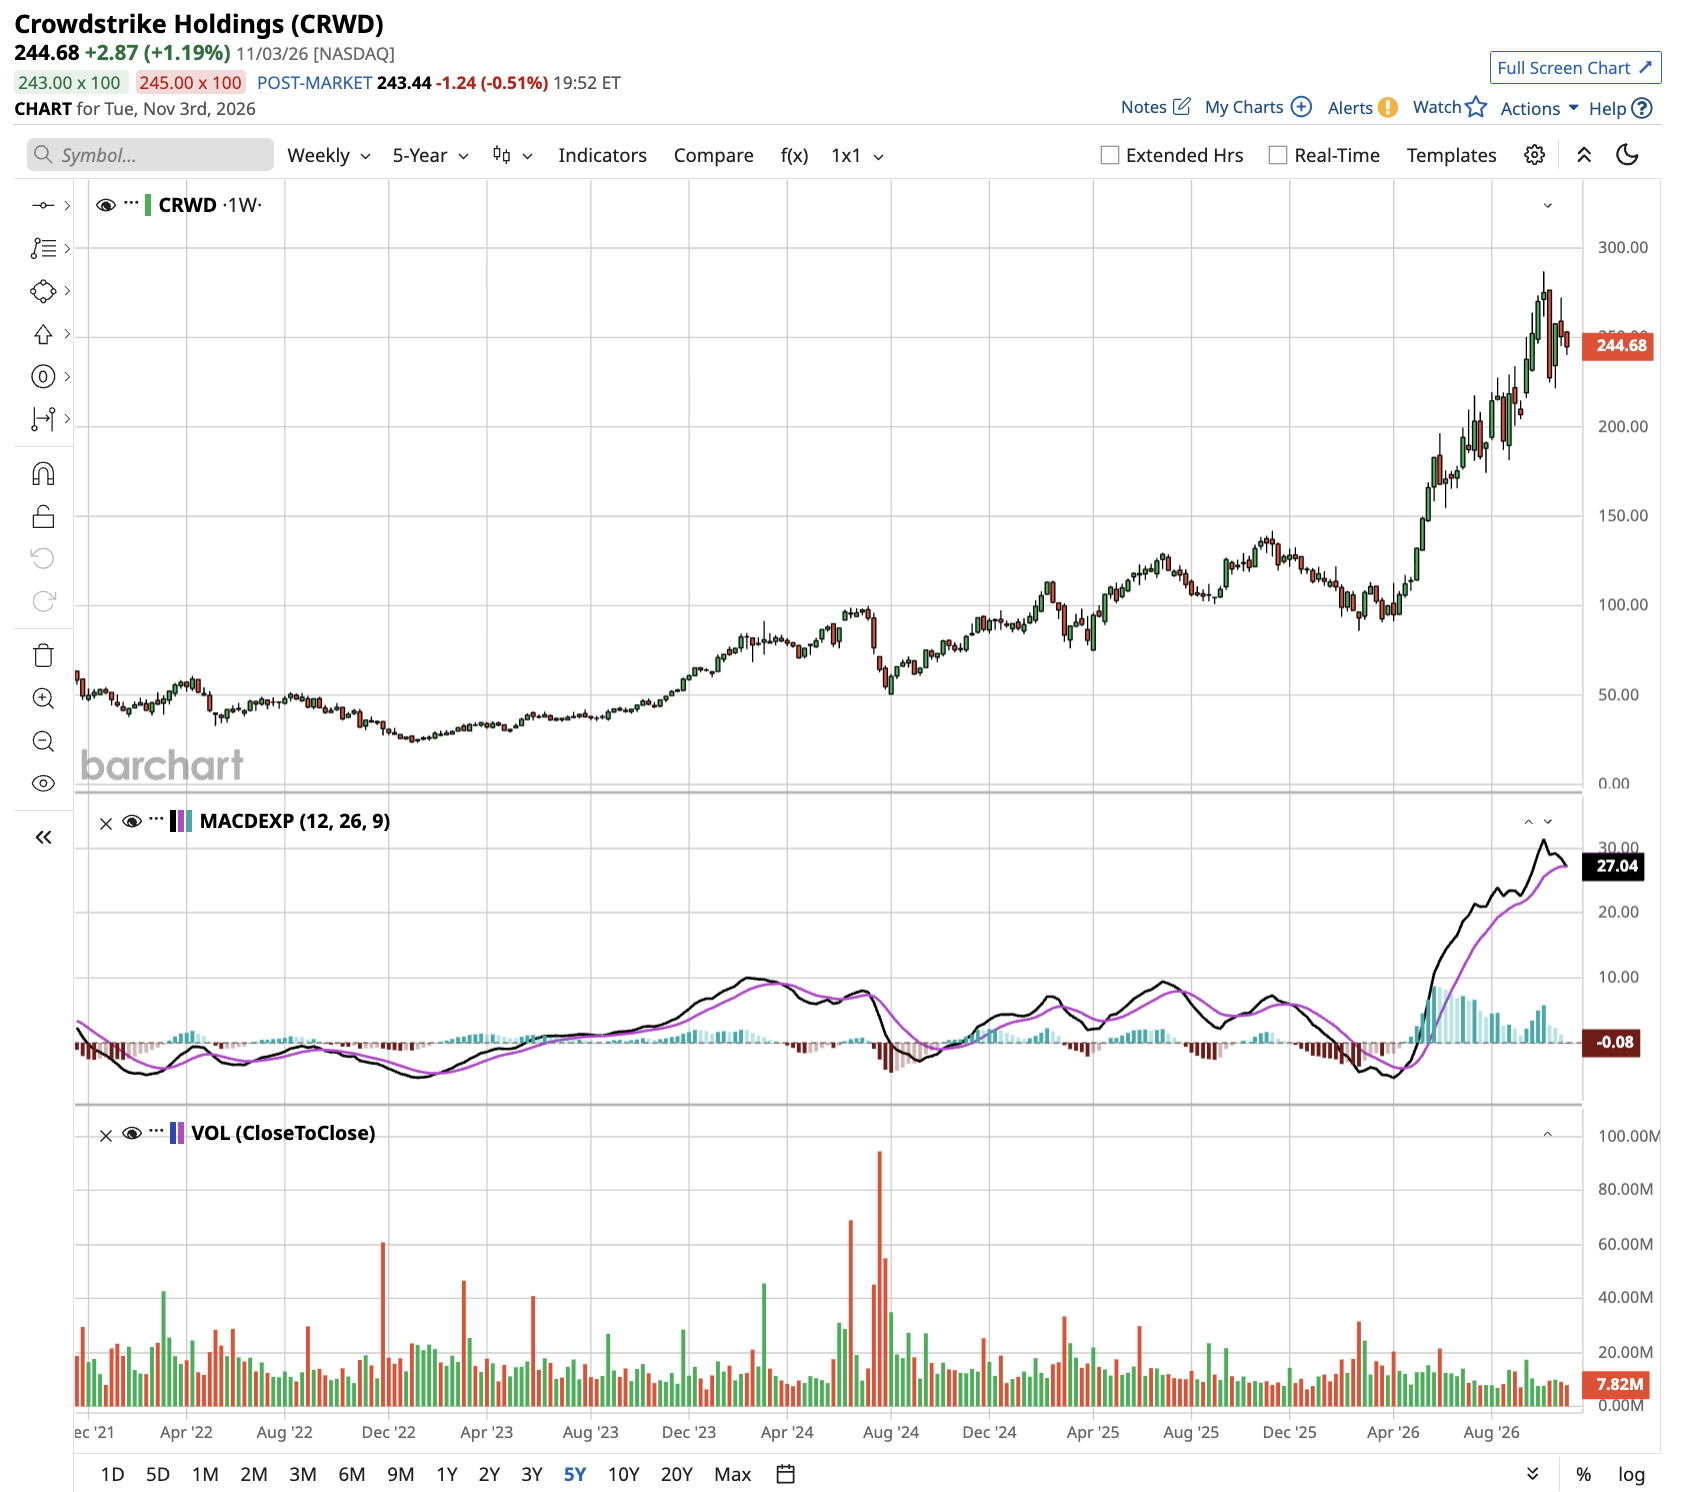
Valued at a market cap of $248 billion, CRWD stock is down over 10% from all-time highs. However, the cybersecurity giant has returned over 1,150% to shareholders since its initial public offering in 2019.
Analysts tracking CRWD stock forecast free cash flow to expand from $1.24 billion in fiscal 2026 (ended in January) to $4.68 billion in fiscal 2031. If the tech stock is priced at 75x forward FCF, which is below the current multiple of 119x, it could surge over 40% within the next three years.
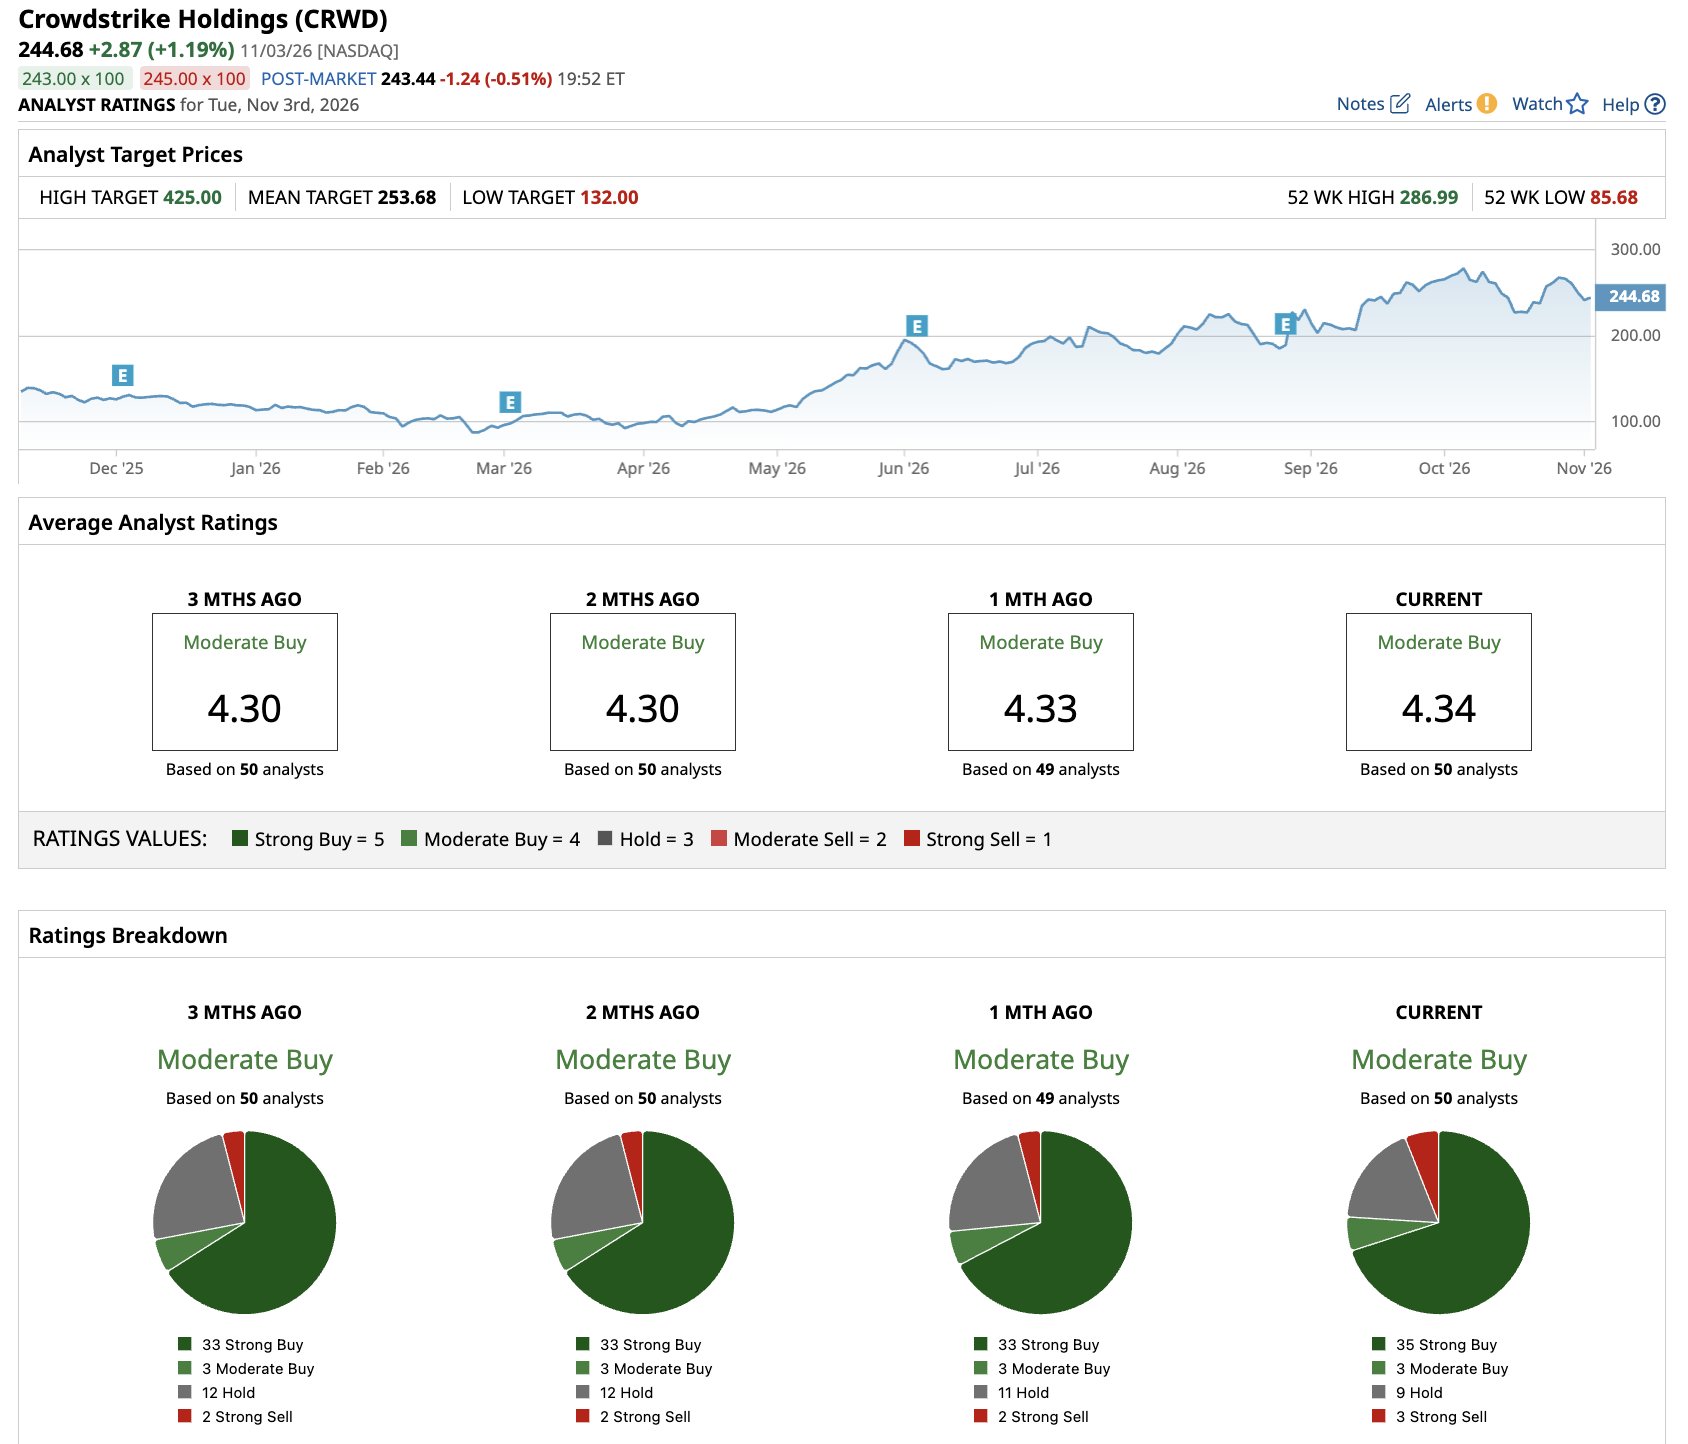
Out of the 50 analysts covering CRWD stock, 35 recommend “Strong Buy,” three recommend “Moderate Buy,” nine recommend “Hold,” and three recommend “Strong Sell”. The average CrowdStrike stock price target is $254, above the current price of $245.
On the date of publication, Aditya Raghunath did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.