


The Bank of England has just lifted interest rates for the first time in more than three years, and that puts the spotlight on funding costs for smaller British businesses. In a world where borrowing is getting pricier, low share price companies with healthier balance sheets can look more resilient than highly leveraged rivals. This article walks through three such penny stocks from our quality focused UK screener.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses with a focus on financial strength. However, if you want the strongest names, these 16 elite penny stocks are at the top of the list.
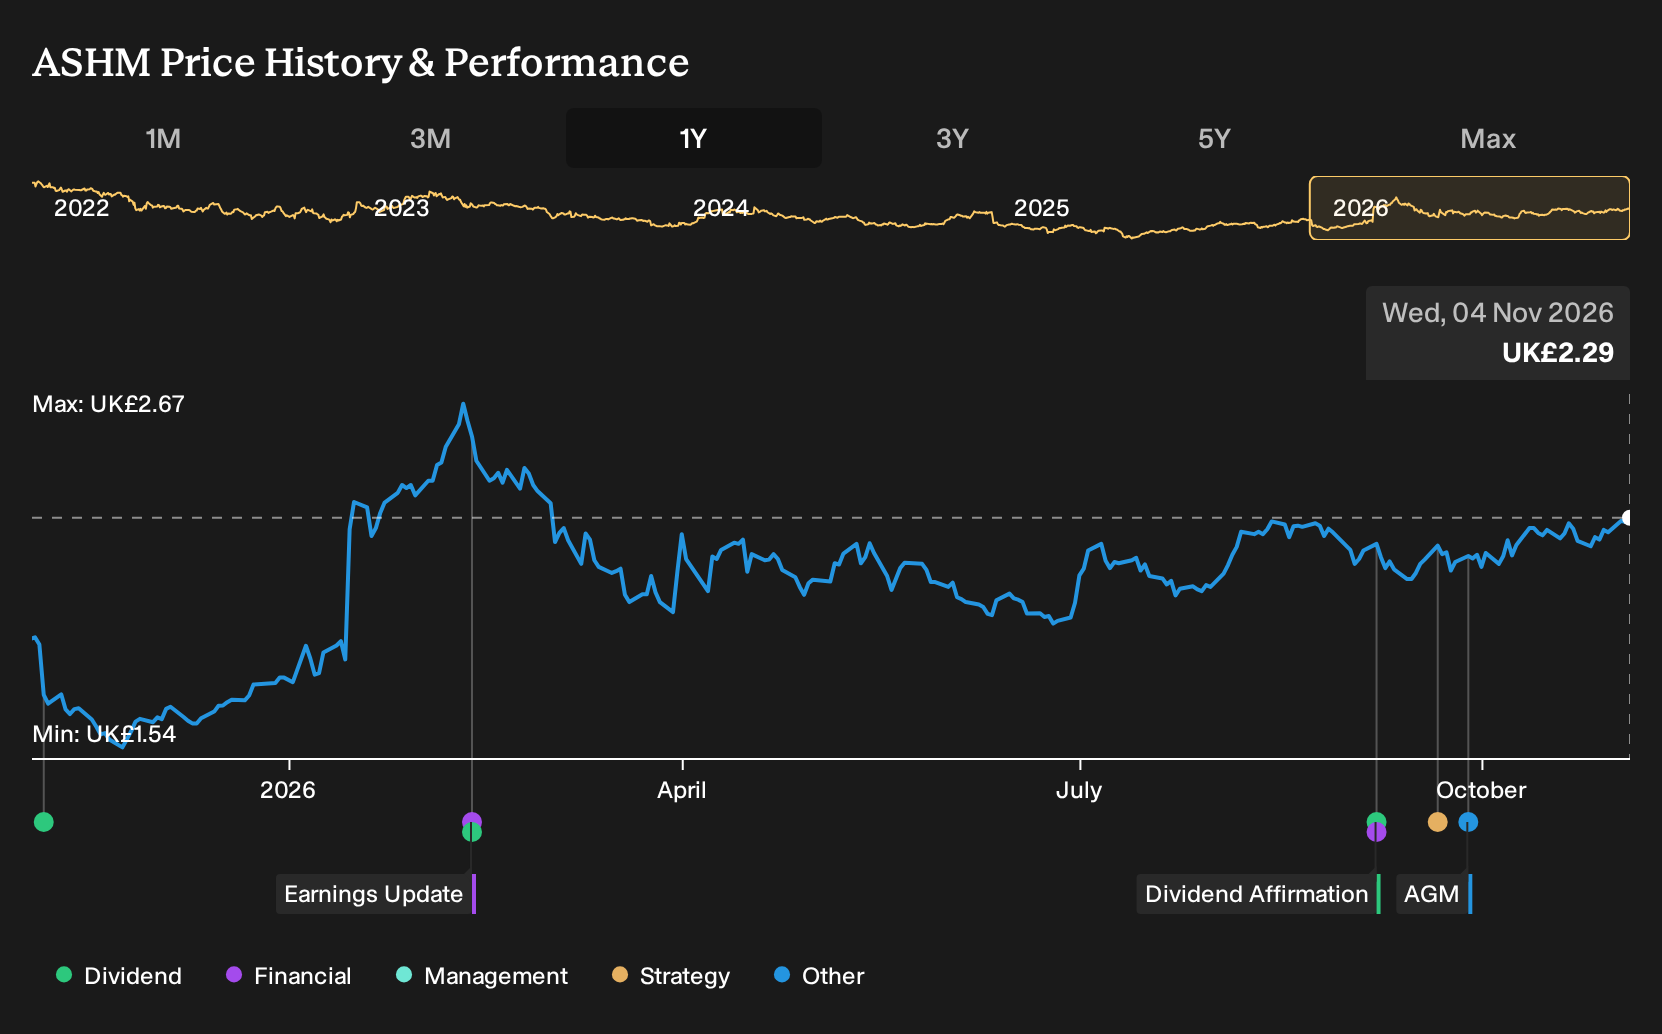
Ashmore Group (LSE:ASHM)
Ashmore Group is a London based asset manager focused on emerging market bonds and shares. It manages £139 million from investment management services and links directly to the Financially Fit Penny Stocks theme through its work with smaller and niche issuers, with a market value of about £1.5 billion.
Ashmore Group gives you targeted exposure to emerging markets where financially solid smaller issuers matter most. The recent shift in client flows has become a key test of how durable that model really is.
"The renewed net inflow phase into emerging markets, with Ashmore Group reporting FY26 net inflows of $2.7b alongside rising subscriptions and lower redemptions, creates scope for a longer period of higher fee earning AuM than consensus typically models."
The real swing factor is how one internal earnings engine behaves if market conditions and client risk appetite change direction again.
If you want to understand how that earnings engine could accelerate or stall, read the full narrative for Ashmore Group for the full story on the moving parts behind it.
Applied Nutrition (LSE:APN)
Applied Nutrition leans directly into the Financially Fit Penny Stocks idea, because its sports nutrition powders, bars, drinks and hydration products are the actual fitness focused goods many consumers already keep in their gym bags.
Applied Nutrition generates about £134 million from the manufacture and sale of sports nutrition products and has a market cap around £763 million.
"High reported free cash flow conversion of 72% in FY25, combined with an adjusted EBITDA margin of 29% and a net cash position, provides Applied Nutrition with room to pursue bolt-on capacity or capability investments that could add incremental revenue without materially increasing financial risk."
What really decides how powerful that cash generation story becomes is whether one quiet capacity decision ultimately supports margins or starts to squeeze them.
That quiet capacity call is the hinge. Read the full narrative for Applied Nutrition to see whether Applied Nutrition’s expansion plans are accelerating value or quietly squeezing returns.

Currys (LSE:CURY)
Currys plugs into the Financially Fit Penny Stocks theme through affordable consumer electronics, mobile devices and repair or insurance services, even though the shares themselves are not penny stock territory. The retailer runs an omnichannel model across the UK and Nordics that blends stores, online sales and support services.
Currys runs an omnichannel chain selling consumer electronics, low cost mobile tech and related services, generating about £5.5b from UK & Ireland and £3.8b from the Nordics, with a market value near £1.5b.
"Expansion of higher margin recurring services such as credit, installations, connectivity and repair, which now account for over 30% of UK revenue and have been growing faster than product sales, can keep lifting Currys group revenue quality and EBIT margins as more customers shift into these offers."
How much one still underappreciated service stream continues to compound within that mix may influence the extent of any margin gains.
That underappreciated stream could be the real engine, and the full narrative for Currys shows how Currys’ service mix might be quietly reshaping risk and upside.

Seeking Alternatives Before Momentum Flies Past?
Fresh ideas do not stay quiet for long. Breakout candidates get spotted, momentum builds, and late arrivals can end up paying higher prices. Review these curated lists before they become widely followed and consider them while they remain less noticed.
- Identify resilient balance sheet leaders early and run your filters across a curated list of solid balance sheet and fundamentals (10 results) while the strongest options are still relatively under the radar.
- Track dividend cash flows and sift through a focused group of 4 dividend fortresses before yields change and some income opportunities become less accessible.
- Explore structural themes in critical metals and review a hand picked pool of 33 best rare earth metal stocks before short-term trading activity significantly shifts attention to these areas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com