


- Americold Realty Trust reported third quarter 2026 revenue of US$691.56 million and net income of US$683.36 million, compared with a loss a year earlier, alongside the appointment of Anita Nanda as Chief Technology & Solutions Officer and the opening of a Global Innovation Center in Atlanta.
- The sharp shift back to profitability, combined with a centralized Global Operations Command Center, highlights how tighter execution and technology-heavy operations are reshaping Americold Realty Trust’s cost structure and service model.
- We will now look at how Americold Realty Trust’s renewed profitability and Global Innovation Center could influence the broader investment narrative.
Scan beyond Americold Realty Trust and track other tech enabled logistics and infrastructure plays that screen strongly on cash flows and balance sheets with the curated 35 high quality undervalued stocks
Americold Realty Trust Investment Narrative Recap
To own Americold Realty Trust, you need to believe that demand for third party cold storage and temperature controlled logistics remains resilient enough for the firm to keep its facilities well utilized, while technology and automation improve efficiency. The sharp swing to a third quarter net profit of US$683.36 million and US$2.38 in basic EPS points to a materially different operating picture than the recent loss making history.
The key near term swing factor is whether this profitability level reflects sustainable operations or one off items, especially given earlier concerns around occupancy, pricing pressure, and high leverage. The biggest risk still sits in utilization and pricing, particularly if customers keep insourcing cold storage or if macro headwinds keep inventory levels subdued.
The most relevant development here is the third quarter 2026 result itself. Revenue of US$691.56 million, compared with US$663.67 million a year earlier, came alongside a move from a US$11.37 million loss to US$683.36 million in net income. For the first nine months, revenue reached US$1.98b with net income of US$326.99 million, versus a loss in the prior period.
For a business previously flagged as unprofitable and carrying meaningful debt, this kind of earnings profile directly affects the conversation around dividend coverage, capital spending on automation, and balance sheet flexibility. Your focus now should be on how repeatable these earnings are, how much stems from underlying warehouse and services performance, and whether cash generation lines up with the headline profit.
Americold Realty Trust's narrative projects US$2.8b revenue and US$1.0b earnings by 2029. This assumes 2.5% yearly revenue growth and an earnings increase of about US$1.1b from a loss of US$111.7 million today.
Uncover how Americold Realty Trust's fair value indicates a 7% potential upside to its current price that could narrow quickly if Americold Realty Trust’s profitability run continues.
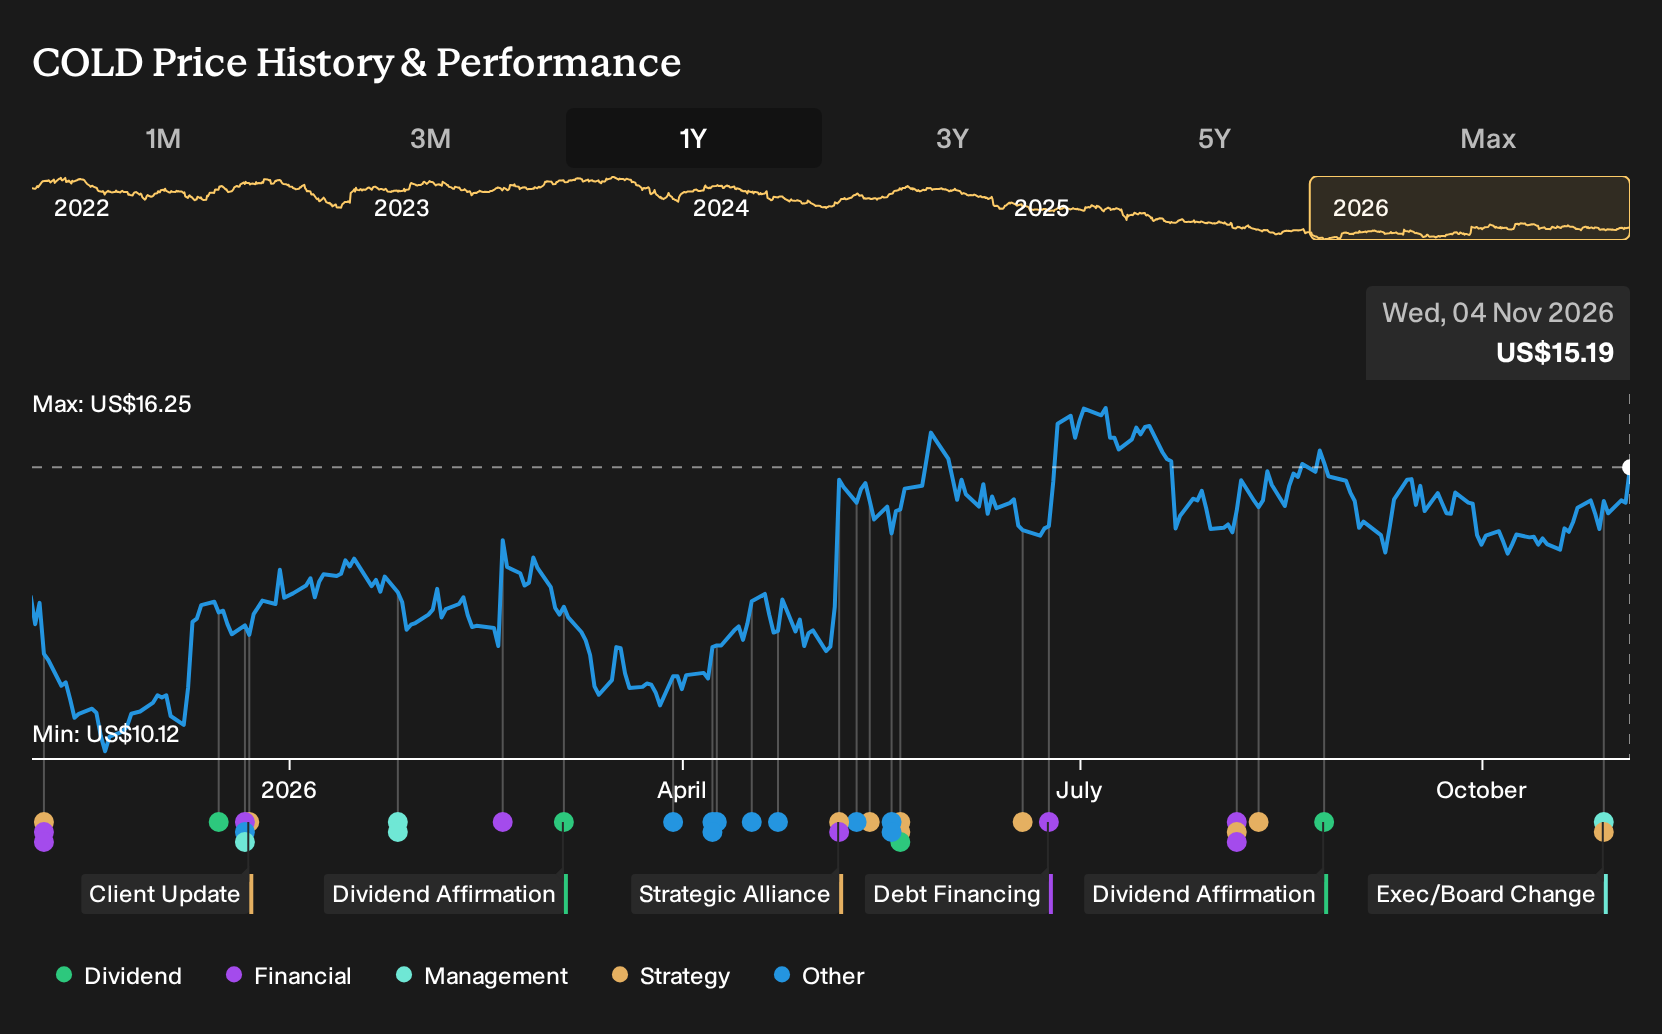
Exploring Other Perspectives
Some of the most optimistic analysts hook their thesis to Americold Realty Trust’s cost programs and debt reduction. Before this earnings shock, they were penciling in revenue growth of 4.5% a year and earnings of US$78.0 million by 2029. You can treat this quarter as a fresh data point that might push those narratives to evolve in very different directions.
Explore 3 other Americold Realty Trust fair value estimates, including one that suggests as much as 45% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Americold Realty Trust research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Americold Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Americold Realty Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Americold Realty Trust?
Once you have a handle on Americold Realty Trust, it can help to widen the lens and compare it with other opportunities that line up with your risk tolerance and income goals. The Simply Wall St Screener lets you filter for the kind of businesses that fit your plan instead of working from a random watchlist.
- If you want lower volatility at the portfolio level, start with companies that show stronger stability metrics and review the 31 resilient stocks with low risk scores as a pre-filtered starting universe.
- For investors who care most about financial resilience, narrow your focus to robust balance sheets and consistent fundamentals with the curated list of solid balance sheet and fundamentals (24 results).
- If you are hunting for overlooked opportunities with healthier economics, scan through the 19 high quality undiscovered gems and see which businesses warrant a deeper look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com