


- Electro Optic Systems Holdings recently appointed senior defence executive Nicolas Chamussy as Executive Vice President for Corporate Strategy and signed a cooperation MoU between EOS Defence Systems and VOP CZ on Czech and wider European armoured vehicle programmes.
- The combination of a Europe based strategy leader and a fresh industrial partnership points to Electro Optic Systems Holdings sharpening its execution focus on European defence demand, integration capability and programme capture, rather than relying only on product technology.
- We will look at how Electro Optic Systems Holdings' investment narrative is shaped by Chamussy's new strategy role and European focus.
Scan how Electro Optic Systems Holdings fits into the broader defence theme by sizing it up against 92 robotics and automation stocks, which is pushing hard into autonomous weapons, sensors and military automation.
Electro Optic Systems Holdings Investment Narrative Recap
To own Electro Optic Systems Holdings, you need to believe the defence and space portfolio can convert its technology position in counter drone systems, high energy lasers and space control into consistent contracts and, over time, profits rather than ongoing losses. The immediate swing factor still looks like execution, turning existing programs and the MARSS platform into repeatable, cash generative projects.
The biggest near term risk is that customer procurement cycles or production ramp ups slip, which would prolong losses and keep reliance on higher risk funding. The Chamussy appointment shapes the playbook for growth but on its own does not change that core catalyst or the operational risk profile in the short run.
The most relevant recent development is the appointment of Nicolas Chamussy as Executive Vice President for Corporate Strategy, with an initial base in Europe. For a defence contractor like Electro Optic Systems Holdings, that concentrates attention on where future tenders, industrial partnerships and customer dialogues are managed, especially given existing activity in the Netherlands and the MARSS hub in Nice.
Investors are watching whether this new leadership role tightens discipline around which bids to pursue, how quickly new offerings are industrialised and how capital is allocated between defence and space. Execution in these areas could support the growth expectations already embedded in analyst forecasts, while weak follow through would leave the company more exposed to competition and slow decision making by government buyers.
Electro Optic Systems Holdings' narrative projects A$526.8 million revenue and A$84.2 million earnings by 2029. This assumes 60.1% yearly revenue growth and an earnings increase of about A$156.6 million from a loss of A$72.4 million today.
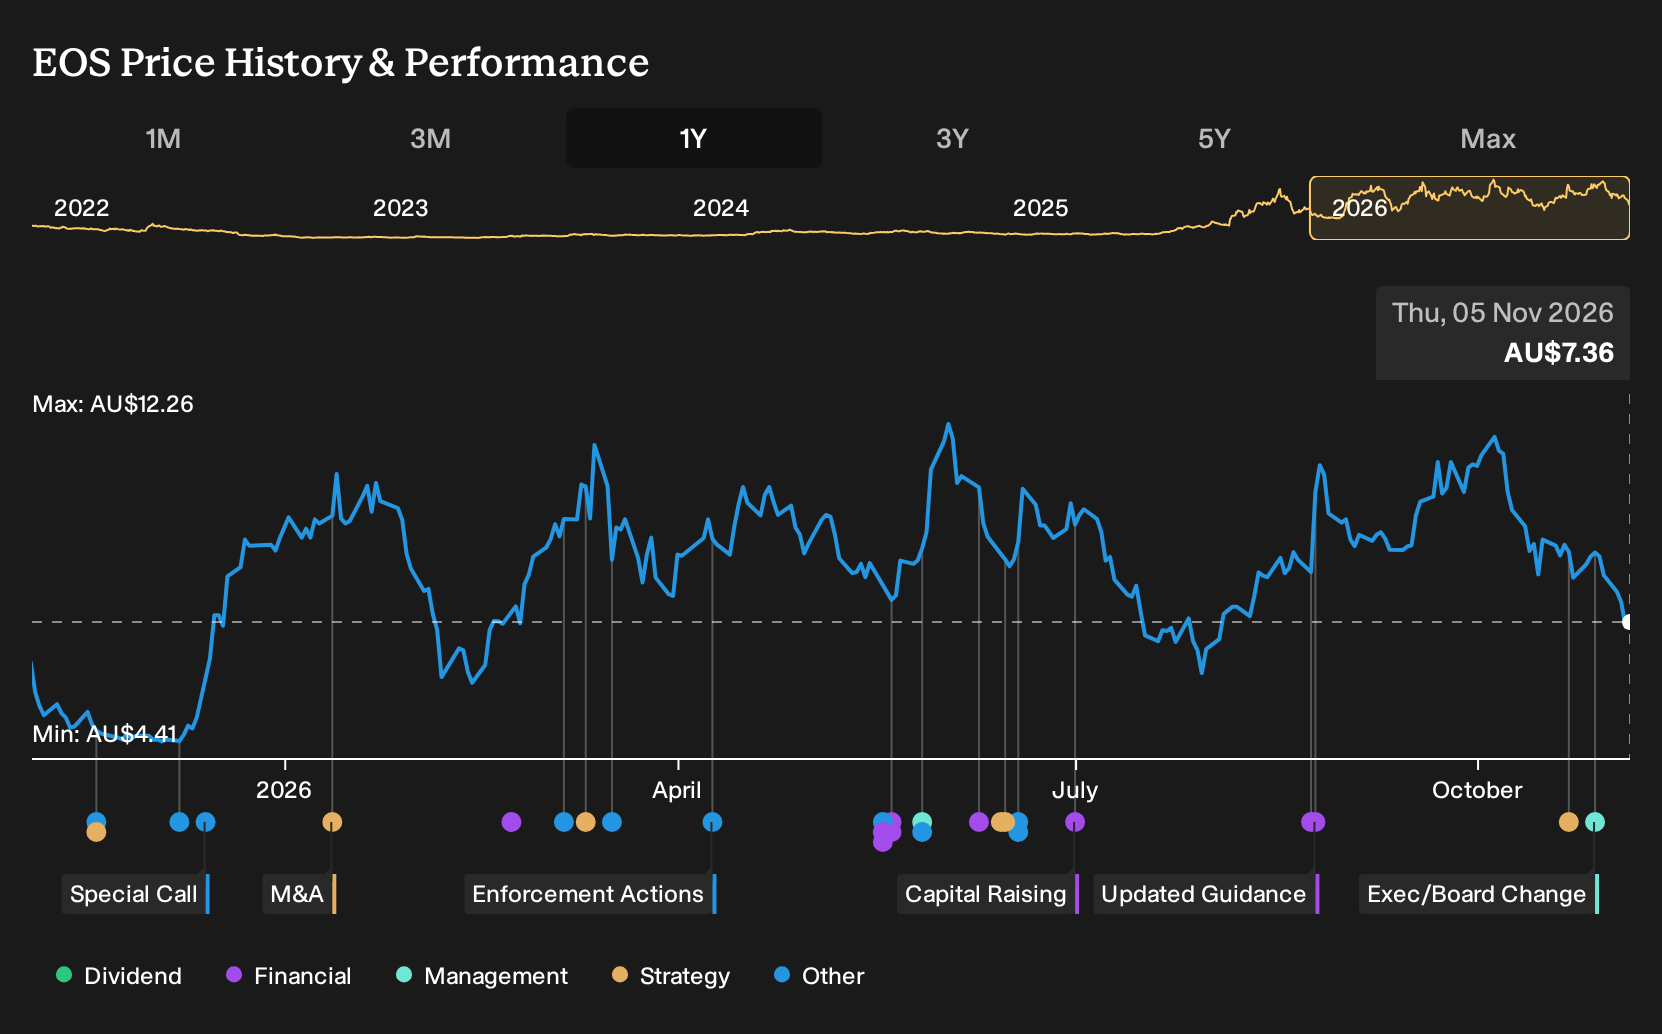
Uncover why Electro Optic Systems Holdings' fair value indicates a 91% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Analysts at the bullish end of the spectrum present an alternate Electro Optic Systems Holdings story based on much faster revenue growth, expecting about A$784.3 million in revenue and A$141.1 million in earnings by 2029, compared with the consensus forecast of A$526.8 million in revenue and A$84.2 million in earnings. Those projections were set before the Chamussy appointment, so your view might shift as this European focus unfolds.
Explore 4 other Electro Optic Systems Holdings fair value estimates, including one that suggests as much as 138% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so trust your own analysis.
- A great starting point for your Electro Optic Systems Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Electro Optic Systems Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Electro Optic Systems Holdings' overall financial position at a glance.
Looking for more Electro Optic Systems Holdings investment ideas?
If you want to balance your view on Electro Optic Systems Holdings with other opportunities, use the Simply Wall St Screener to scan for shares that better match your own risk appetite, income needs and valuation discipline.
- If capital preservation matters to you, start with a set of 6 resilient stocks with low risk scores that may help you keep drawdowns under tighter control.
- If you prefer quality at a sensible entry point, filter for 14 high quality undiscovered gems that the wider market might not be focusing on yet.
- If balance sheet strength is your priority, narrow in on a list of solid balance sheet and fundamentals (12 results) that complements a higher risk holding like Electro Optic Systems Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com