


TeraWulf has delivered a very large share price gain over the past three years, even as more recent returns have cooled. That puts a sharper spotlight on whether today’s valuation can be grounded in its sales base. With the stock last closing at US$11.70 after a mixed short term run, the key issue for you is how that price lines up with what the business is actually generating in revenue.
- The share price is up by roughly 11x over three years. A lot of optimism is already embedded and that raises the stakes for how much current and future sales can justify.
- The expanded revolving credit facility to about US$400 million, plus an uncommitted accordion feature, can support TeraWulf’s data center build out and may shape both the pace of revenue growth and the timing of cash flows tied to those projects.
- Your read on TeraWulf is one view; the desks covering it have another. See what analysts think TeraWulf's shares could be worth.
The issue now is whether TeraWulf’s current share price is adequately supported by its sales when set against the Fair Ratio benchmark.
If you want to test the same sales based valuation question that hangs over TeraWulf across a broader set of AI infrastructure plays, take a look at 53 AI infrastructure stocks.
Has TeraWulf Run Too Far on Sales?
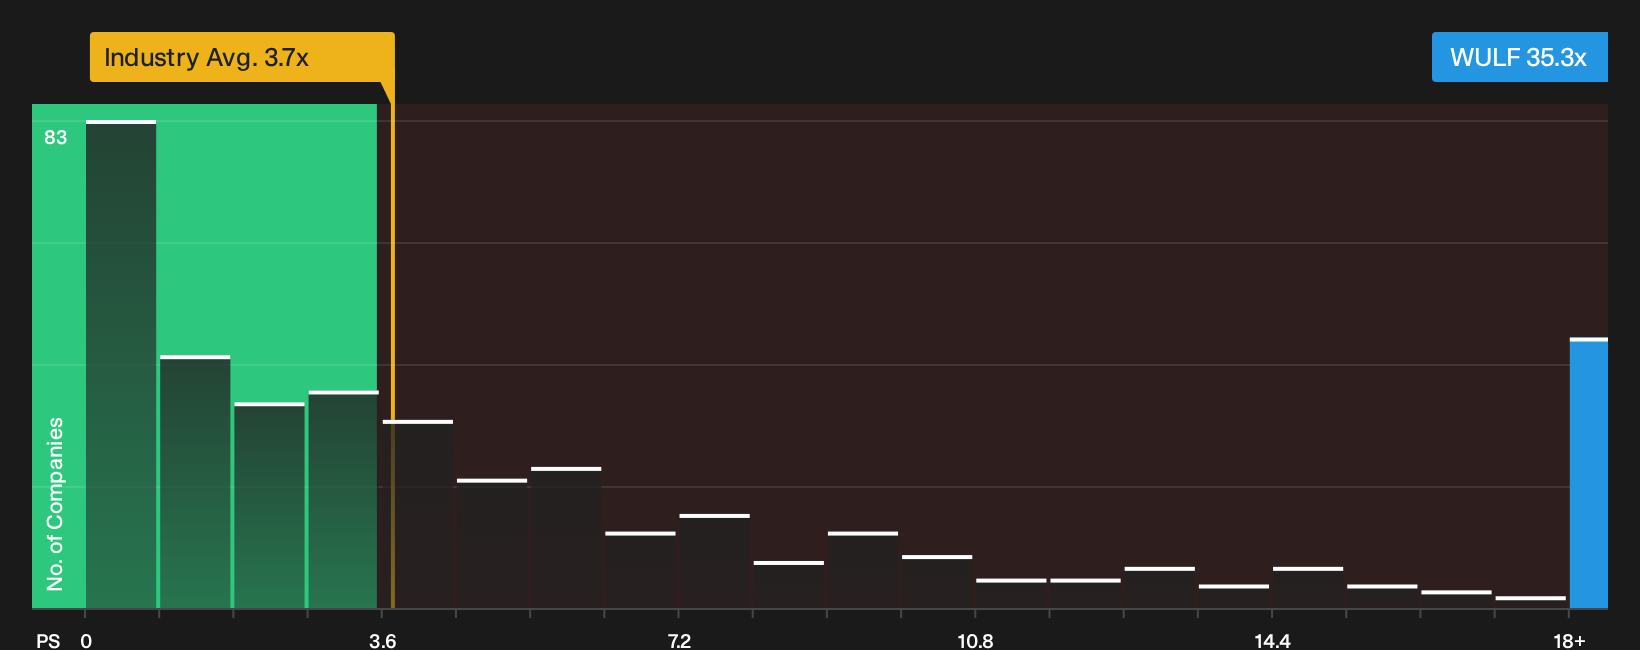
P/S suits TeraWulf because investors are focused on what its revenue base can support while free cash flow is still deeply negative. On that lens, the stock changes hands at about 35.3x P/S, compared with roughly 3.7x for the wider software industry and around 9.4x for closer peers. This signals a very rich sales tag for every dollar of turnover the company generates today.
The Fair Ratio, which reflects what a more tailored model might expect given TeraWulf’s sector, scale and risk profile, sits materially lower than the current P/S, so the shares screen overvalued on this yardstick. Because the expanded revolving credit facility has pushed AI data center sentiment higher, the recent bounce leaves even less margin between the market’s optimism and what that Fair Ratio implies. You should decide whether the revenue potential and project pipeline are strong enough to justify paying this kind of premium to both peers and the Fair Ratio benchmark before committing fresh capital to the stock. Explore the numbers behind TeraWulf's P/S valuation.
The TeraWulf Narrative: What Would Justify Today's Price?
TeraWulf Narratives pick up where the P/S puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to appear meaningfully undervalued or expensive at today’s price on Simply Wall St's Community page. Rather than relying on a single multiple or model output, each scenario sets out its key assumptions so you can compare them with future results as they are reported.
One of the top community narratives on TeraWulf: 64% undervalued
"TeraWulf's recent multi-billion-dollar, multi-year hyperscale hosting agreements mark a significant shift from a pure bitcoin mining model toward diversified, contracted revenue streams."
Discover why this Narrative puts TeraWulf at 64% undervalued.
Before you act on TeraWulf’s valuation, there is one more angle to check
Price multiples tell only part of the TeraWulf story, because separate checks on the business have raised specific concerns that deserve your attention before you move further. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com