


Regeneron Pharmaceuticals has rallied hard over the past few years, and fresh earnings headlines keep pulling investor attention back to the same issue. With the share price moving quickly, the key concern now is whether that valuation can still be explained by the company’s earnings power.
- Over the past 5 years the stock has returned 51.0%, which puts real weight on the question of whether the current price is still grounded in the underlying profit stream.
- Recent earnings news points to strong demand for treatments such as Dupixent and Libtayo, which can shape how investors think about the durability and timing of future cash flows that support today’s P/E-based pricing.
- There is a second opinion on Regeneron Pharmaceuticals worth weighing. See what analysts think Regeneron Pharmaceuticals's shares could be worth.
The issue now is whether Regeneron Pharmaceuticals’ current share price is adequately supported by the earnings it is generating today and is expected to produce in the years ahead.
If you want a wider starting point for ideas in the same vein, apply the same earnings-focused lens to a curated list of 35 high quality undervalued stocks.
Is Regeneron Pharmaceuticals Still Cheap on Earnings?
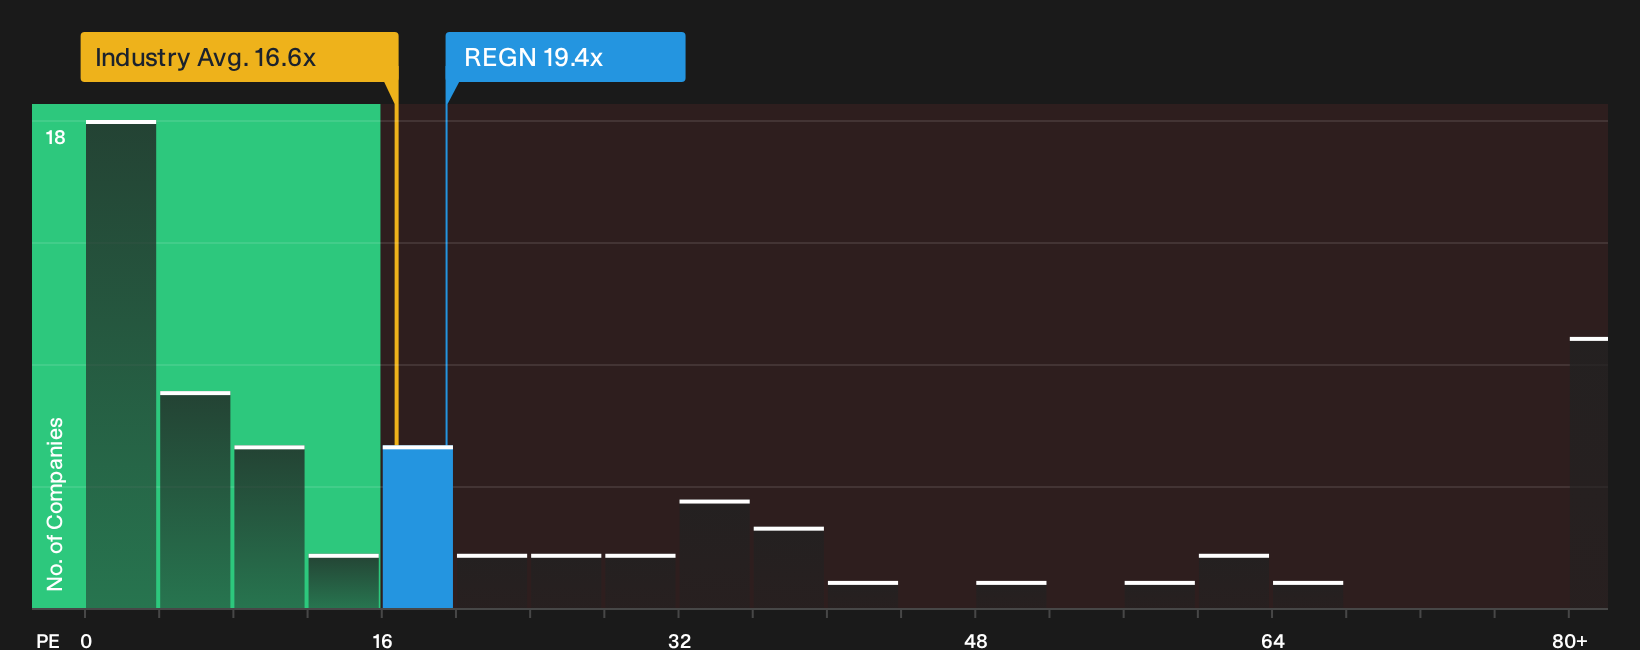
P/E tends to be the cleanest way to think about Regeneron Pharmaceuticals because earnings are a key focus for this business. The stock trades on a P/E of about 19.4x, which is below both the biotech industry average of roughly 16.6x and the peer group closer to 48.0x. That puts Regeneron in an unusual spot where the shares are priced above the broad sector but well under many direct comparables that investors often watch.
The fair P/E that would typically line up with Regeneron’s mix of growth profile, margins, size and risks sits above the current 19.4x level, so on this framework the shares screen as undervalued. Because recent Q3 2026 results featured strong earnings per share alongside upbeat commentary on products like Dupixent and Libtayo, the current multiple suggests the market is not fully mirroring that backdrop in the price. For investors, the key question is whether that gap to a higher implied fair multiple can persist or eventually close. Explore the numbers behind Regeneron Pharmaceuticals's P/E valuation.
The Regeneron Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Regeneron Pharmaceuticals pick up where the P/E debate leaves off and explain what kind of future growth, profitability and earnings path would need to occur for the stock to be worth materially more or less than the current share price, based on a reasonable set of assumptions. Each scenario links its figures to a specific view of how Regeneron Pharmaceuticals' growth, margins and risk profile might change over time. You can track these scenarios against new results on the Community page.
Community views on Regeneron Pharmaceuticals are split between those who see extra earnings power still being underappreciated and those who think retinal risks already cap the upside.
Bull case: 16% undervalued
"Full recognition of Regeneron Pharmaceuticals’ share of Sanofi collaboration profits from Q3 2026 onward, following repayment of the development balance…"
Discover why this Narrative puts Regeneron Pharmaceuticals at 16% undervalued.
Bear case: 7% overvalued
"Kodiak Sciences reported that Zenkuda matched EYLEA on vision outcomes while allowing many wet AMD patients to dose every six months…"
Explore why this Narrative puts Regeneron Pharmaceuticals at 7% overvalued.
One more Regeneron Pharmaceuticals factor to weigh before making a move
Before you treat today’s valuation as the full story, it helps to see how professional analysts currently map out Regeneron Pharmaceuticals a few years from now, then compare that view with your own. Explore where analysts expect Regeneron Pharmaceuticals to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com