


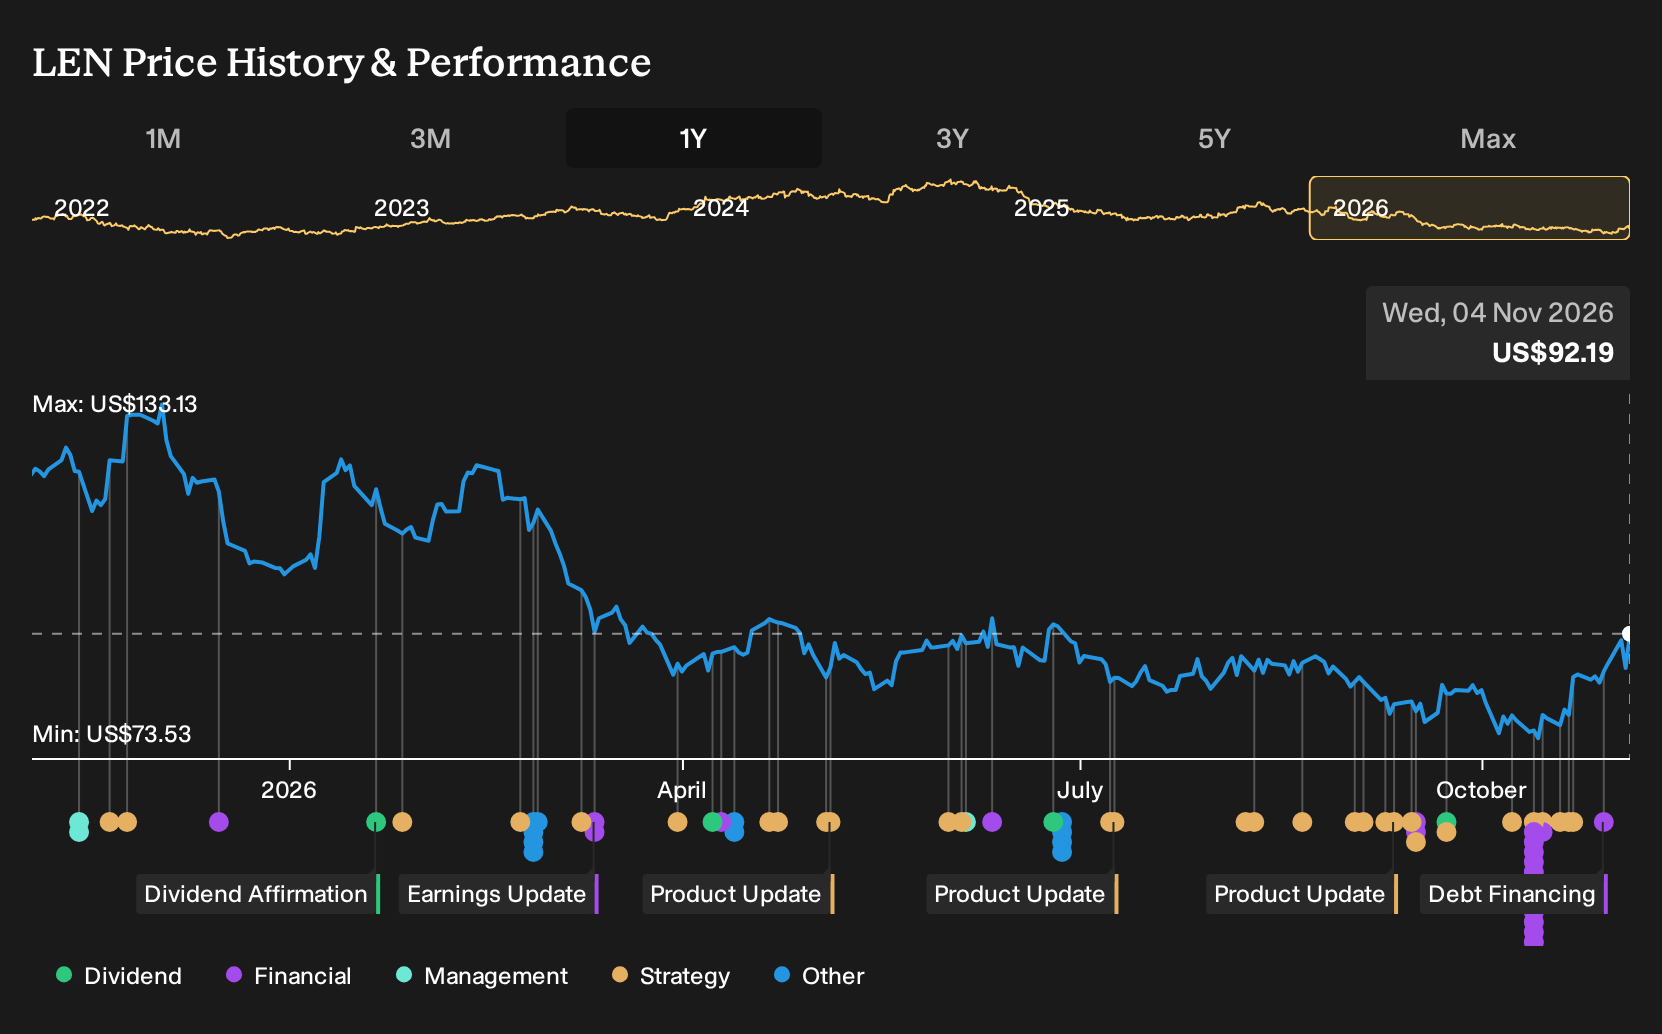
- Lennar amended and restated its revolving credit and delayed draw term loan agreements, lifting total potential borrowing capacity to about US$4.545b, extending key maturities into 2031 and removing a previous 0.10% SOFR credit spread adjustment while adding rating based interest and fee reductions.
- The larger unsecured facilities, guaranteed mainly by homebuilding subsidiaries and available for working capital and acquisitions, give Lennar more room to fund land, construction and new master planned communities while dealing with higher build costs and affordability pressure.
- This analysis reviews how Lennar's investment narrative is affected by the larger revolving credit capacity and longer dated debt maturities.
Compare how Lennar is handling higher build costs and tighter financing conditions with peers by scanning our hand picked list of solid balance sheet and fundamentals (24 results).
Lennar Investment Narrative Recap
To own Lennar, you need to be comfortable with a volume driven homebuilding model that leans on faster build cycles, incentives and an asset light land approach to keep homes moving even as affordability stays strained. The recent expansion and extension of credit lines mostly reinforces that playbook rather than changing it.
The key near term swing factor is how well Lennar converts that liquidity into steady orders and closings while protecting already compressed margins. The biggest current risk remains further pressure from high mortgage rates and rising land costs, which could squeeze profitability even if funding is available and construction efficiency holds.
Among recent updates, the launch of King Oaks near McDonough matters most alongside the credit news. It shows Lennar still committing capital and attention to larger master planned communities that can support its volume focus and just in time model even as it manages a heavier financing toolkit.
Execution at projects like King Oaks will feed directly into the main catalysts investors watch, including construction cycle times, incentive levels and the ability to keep communities affordable without eroding returns. If those communities struggle with demand or require deeper discounts, the risks around margins and the asset light strategy become more visible.
Lennar's consensus narrative points to revenues of about US$40.6b and earnings of roughly US$2.7b by 2029, based on analysts assuming 8.3% yearly revenue growth and an earnings increase of about US$1.4b from current earnings of roughly US$1.3b.
Uncover why Lennar's fair value indicates a 16% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view argues that Lennar’s larger credit lines mainly amplify risk if affordability keeps biting. Those bearish analysts were penciling in roughly flat revenue near US$31.7b and earnings of only about US$1.0b by 2029 before this financing news. That is a much harsher story than consensus, so explore both narratives before deciding how this shift in firepower might reshape expectations.
Explore 4 other Lennar fair value estimates, including one that suggests as much as 40% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lennar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lennar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lennar's overall financial health at a glance.
Looking For More Ideas Beyond Lennar?
If Lennar has you thinking about where to put the next dollar of capital, it helps to scan a broader field of opportunities. Use the Simply Wall St Screener to quickly filter for businesses that fit your risk appetite, income needs and valuation discipline instead of trawling through tickers one by one.
- If capital preservation matters most right now, start with companies that pair resilient balance sheets with measured risk using our 31 resilient stocks with low risk scores.
- For investors who want quality at a reasonable price, focus on businesses that combine stronger fundamentals with what may be more modest valuations through the 35 high quality undervalued stocks.
- If you prefer to back underfollowed stories with solid financials, target less crowded opportunities using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com