


Par Pacific Holdings has delivered a powerful run over the past few years, even as the share price has recently pulled back, which naturally raises the question of whether the current US$69.66 level is still supported by its earnings power. With that kind of track record in the rear-view mirror and fresh company updates on the table, the valuation story now hinges on how much earnings strength you think the business can sustain.
- Par Pacific Holdings has returned about 344.5% over the past 5 years, so a lot of past success is already reflected in the share price and puts more pressure on the earnings picture to carry the story from here.
- Recent news that the company plans to sell its 46% stake in Laramie Energy and has seen its renewables arm reach profitability may support shifts in future earnings mix, cash generation and capital needs that matter directly for how you value those earnings today.
- There is a second opinion on Par Pacific Holdings worth weighing. See what analysts think Par Pacific Holdings's shares could be worth.
The issue now is whether Par Pacific Holdings' current share price is justified by the earnings it is generating and what investors expect those earnings to look like over time.
For a broader watchlist alongside Par Pacific Holdings, start a focused search using 35 high quality undervalued stocks as another way to find stocks where current pricing and business quality may not fully align.
Is Par Pacific Holdings a Bargain on Earnings?
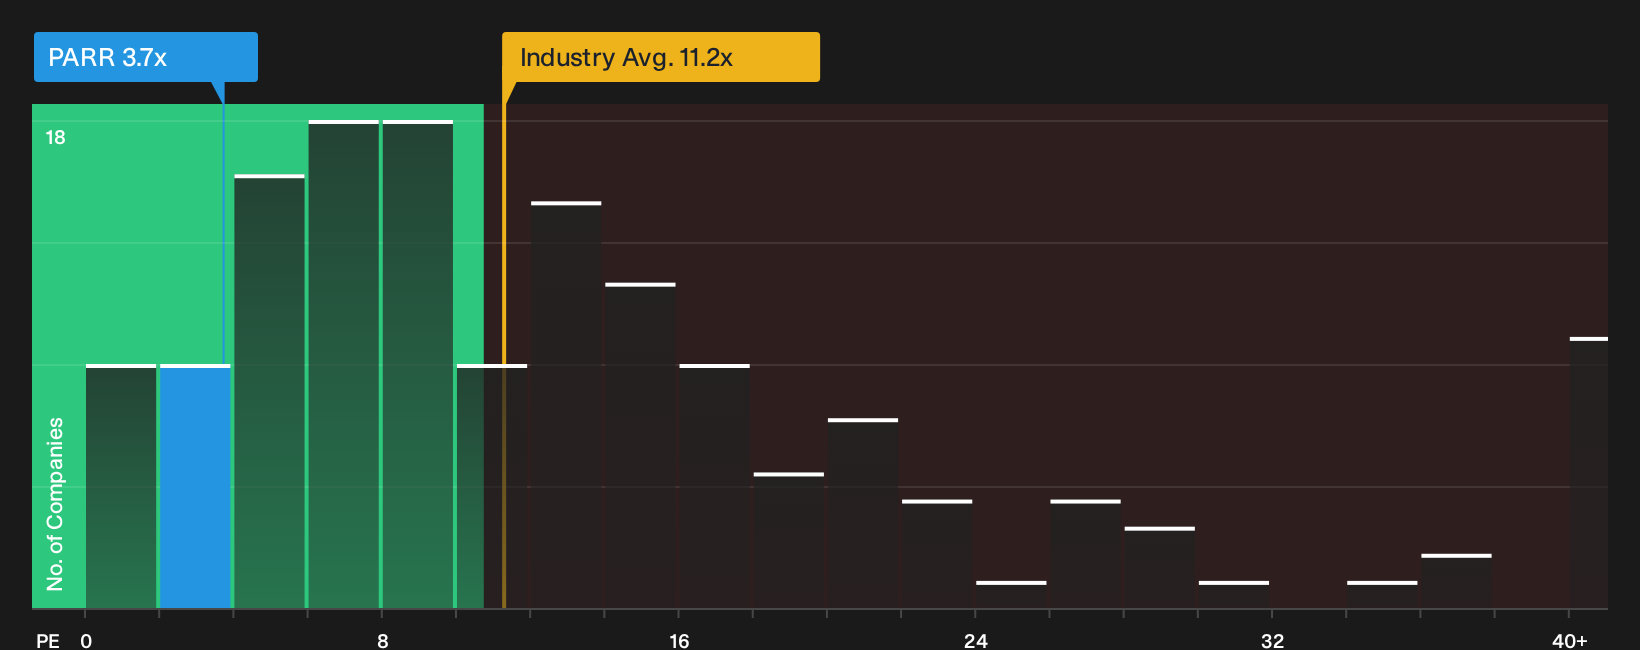
The P/E ratio suits Par Pacific Holdings because earnings are a key driver for how investors look at refiners and energy infrastructure groups. On this lens, the stock trades on a P/E of about 3.7x compared with an Oil and Gas industry average of roughly 11.2x and a peer group around 11.9x, which is a steep gap. A tailored fair multiple that blends the firm’s growth profile, margins, size and risk suggests the shares trade below where that framework would normally place them.
Because the third quarter of 2026 brought profitable renewables operations and a planned US$120 million cash inflow from the Laramie Energy sale, the current discount on Par Pacific Holdings' P/E ratio indicates the market is giving limited credit to those developments. For any holder or potential buyer, the key judgment is whether today’s earnings level and business mix can support that kind of gap to both sector norms and the more customised fair multiple. Explore the numbers behind Par Pacific Holdings's P/E valuation.
The Par Pacific Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Par Pacific Holdings valuation puzzle leaves off. They spell out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s share price. Each one sets out a fair value view as a thesis about how the business might play out over time, so you can track how the story evolves on the Community page.
One of the top community narratives on Par Pacific Holdings: 25% undervalued
"The main thing that has to go right is that Par Pacific maintains high distillate and jet yields, executes the Hawaii Renewables ramp…"
Discover why this Narrative puts Par Pacific Holdings at 25% undervalued.
The share price is only one piece of the Par Pacific Holdings puzzle
Valuation tells you what you are paying, but the real test for Par Pacific Holdings is what the underlying risk checks are quietly flagging in the background. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com