


- DXP Enterprises reported third quarter 2026 sales of US$587.18 million and net income of US$26.87 million, with both basic and diluted earnings per share from continuing operations above the prior year period.
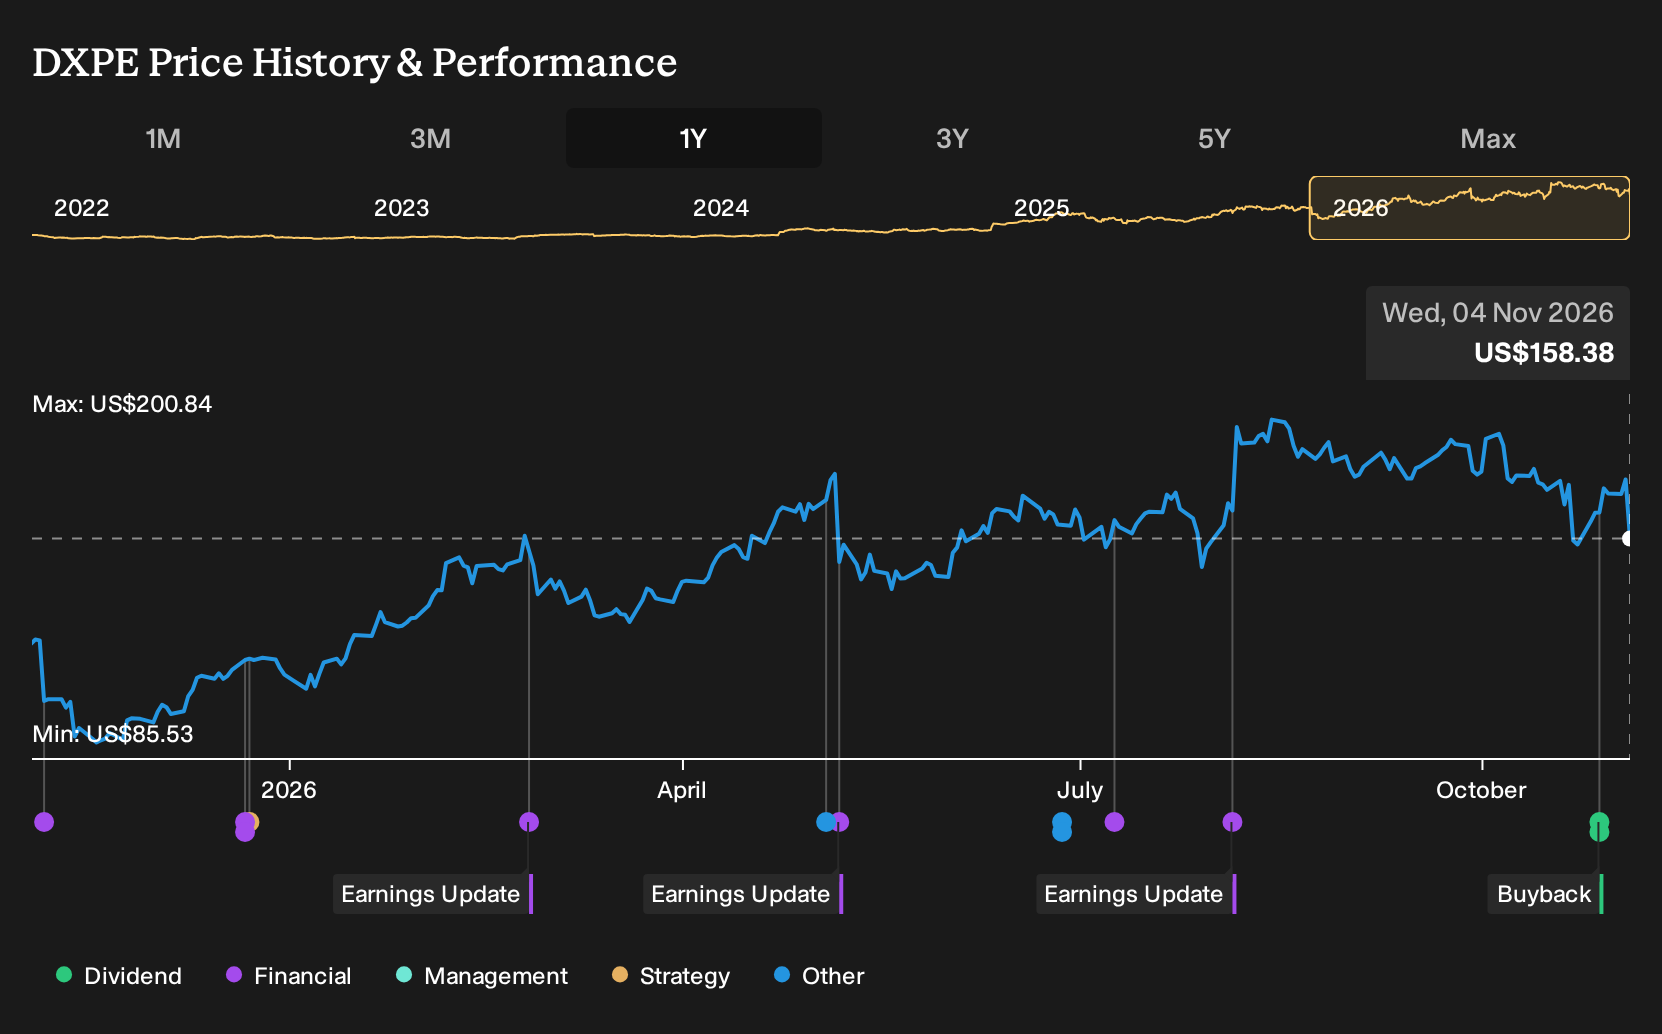
- The newly authorized 24 month, US$150 million share repurchase program covering up to 1,000,000 shares adds a capital allocation layer on top of DXP Enterprises' higher earnings per share, which can influence how investors weigh its cash flow priorities and balance sheet use.
- We will now look at how DXP Enterprises' reported third quarter earnings relate to its investment narrative around margins and cash use.
Scan how DXP Enterprises fits alongside other cash generative industrials by reviewing our hand picked list of solid balance sheet and fundamentals (24 results), which also prioritizes disciplined capital returns such as buybacks.
DXP Enterprises Investment Narrative Recap
To own DXP Enterprises, you need to be comfortable with a business that leans heavily on acquisition driven expansion, higher value engineered solutions and steady cash generation to support a leveraged balance sheet. The Q3 2026 report shows sales of US$587.18 million and net income of US$26.87 million, which supports that cash flow story in the near term.
The near term catalyst is whether DXP can keep pushing mix toward water, wastewater and other engineered projects while integrating recent deals without margin slippage. The biggest risk still sits on the liability side. Total debt of about US$842.5 million means any stumble in earnings or free cash flow could make refinancing more uncomfortable.
The fresh 24 month, US$150 million share repurchase authorization for up to 1,000,000 shares now sits alongside those higher Q3 earnings per share. For you as a shareholder, the practical question is how this interacts with DXP Enterprises' priorities around acquisitions, interest costs and ongoing investment in service capabilities.
A buyback of up to 6.1% of outstanding stock can tighten the share count over time and may amplify per share metrics if operating performance holds up. It also concentrates risk. With debt not well covered by operating cash flow, the execution test is whether management can keep funding deals, servicing borrowings and running this program without stretching the balance sheet.
DXP Enterprises' current analyst narrative points to revenues of US$2.7b and earnings of US$174.7 million by 2029, based on assumed yearly revenue growth of 8.7% and an earnings increase of about 88% from US$93.1 million today.
Uncover how DXP Enterprises' fair value indicates a 26% potential upside to its current price, which could narrow quickly if DXP Enterprises continues to execute on its plan.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$196.24 and US$200 per DXP Enterprises share, yet past commentary has flagged the stock trading at a very large premium to some other intrinsic value views. As you weigh debt risks, acquisition plans and the new buyback, recognise how widely investor opinions can differ and consider reviewing several alternative viewpoints before drawing conclusions.
Explore another DXP Enterprises fair value estimate, including one that suggests it could be worth just $196.24!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DXP Enterprises research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DXP Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DXP Enterprises' overall financial health at a glance.
Looking For More Investment Ideas Beyond DXP Enterprises?
If DXP Enterprises has sharpened your focus on balance sheets, cash generation and capital returns, it can be useful to line it up against other listed businesses with different risk and income profiles.
- For potential mispricings where quality and valuation intersect, review our hand picked 35 high quality undervalued stocks that fit a similar focus on fundamentals and cash generation.
- If capital protection matters most to you, scan companies in the 31 resilient stocks with low risk scores that pair sturdier financial profiles with lower overall risk scores.
- For investors hunting for resilient income, compare DXP Enterprises with yield focused opportunities by checking out the 5 dividend fortresses that have historically offered higher payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com