


Mitsubishi has delivered a long stretch of strong share price gains, and the pace of that climb now puts a sharper spotlight on whether today’s valuation is still grounded in what the business earns. With the stock near recent highs, the question for investors is how well the current price lines up with Mitsubishi’s earnings profile.
- Over the past 5 years the share price has returned about 442.1%, which raises the question of how much of that move can be linked to changes in the company’s earnings power.
- Mitsubishi’s decision to raise its full year profit forecast and approve up to ¥1t of share buybacks can support the case that earnings and capital returns are playing a larger role in how the market is thinking about the stock.
- Your read on Mitsubishi is one view; the desks covering it have another. See what analysts think Mitsubishi's shares could be worth.
The stock’s next move may depend on whether Mitsubishi’s current share price is adequately explained by the earnings that underpin it today.
If you want to stress test this same earnings question beyond Mitsubishi, you can compare it with companies filtered by 19 high quality undervalued stocks.
Is Mitsubishi a Bargain on Earnings?
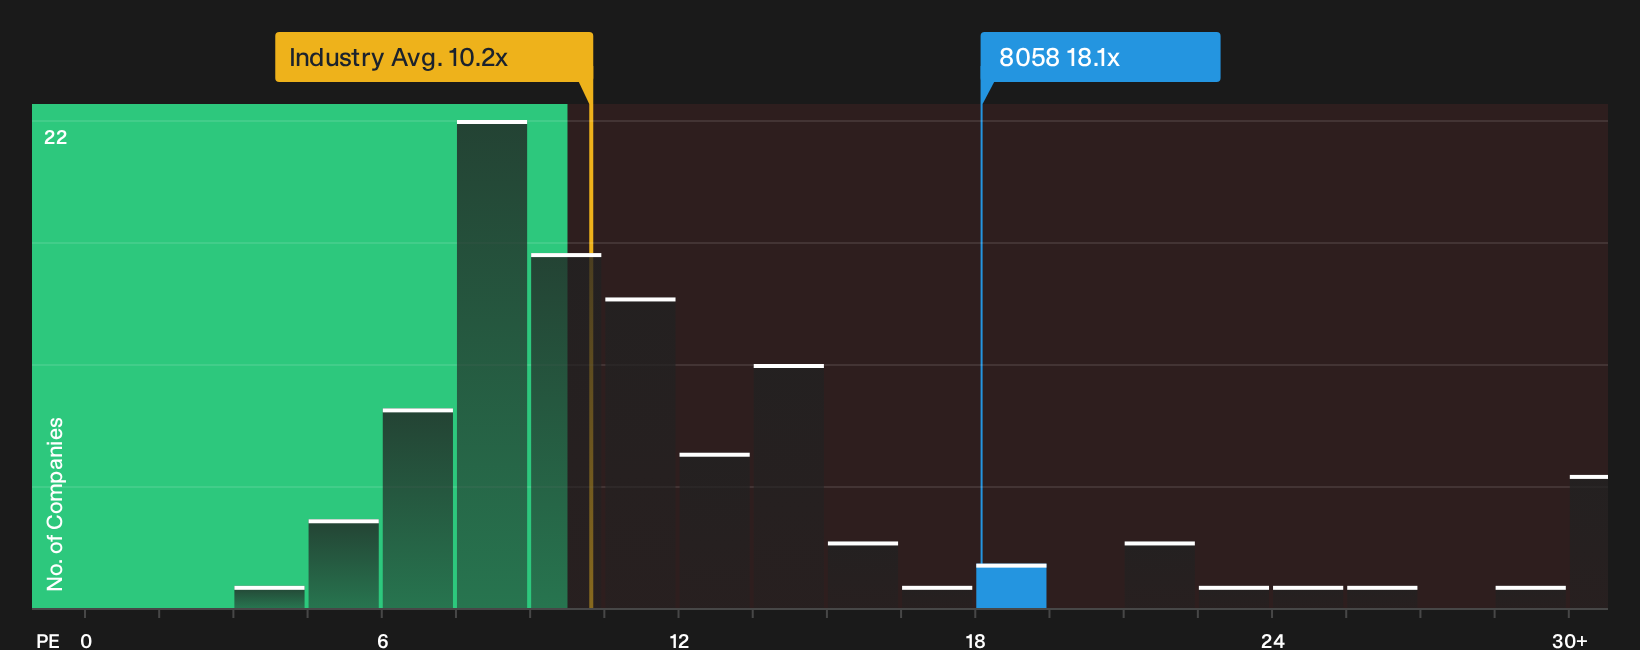
P/E works well for Mitsubishi because profits are a key focus for investors in large trading houses. On this lens, the stock changes hands at about 18.1x earnings, which is higher than the Trade Distributors sector average of roughly 10.2x and also above the peer group near 14.9x. Those simple comparisons point to the market already assigning a richer tag to each yen of Mitsubishi’s net income relative to many rivals.
That premium still screens as undervalued against a more tailored fair P/E that takes Mitsubishi’s earnings profile, business mix and risk into account, which implies the current multiple sits below where that framework would place it. Because management recently lifted its full year profit forecast and signed off on up to ¥1t of buybacks, the gap suggests investors are not fully pricing in the earnings and capital return story that the company is now leaning into. Explore the numbers behind Mitsubishi's P/E valuation.
The Mitsubishi Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Mitsubishi valuation puzzle leaves off and spell out which growth, margin and earnings paths would need to hold for the shares to be worth meaningfully more or less than today’s price. Each narrative sets out Mitsubishi’s implied fair value as a specific, testable idea about how the business might develop over time, so you can watch how that thesis matures on the Community page.
Bulls and bears on Mitsubishi are looking at the same cash flow targets and energy projects, but they read the risk and reward very differently.
Bull case: 25% undervalued
"The plan to divest roughly 20 identified companies under Mitsubishi’s ROE-focused portfolio discipline creates room to recycle capital into higher return projects..."
Discover why this Narrative puts Mitsubishi at 25% undervalued.
Bear case: 61% overvalued
"Although Mitsubishi Corporation is expanding its gas value chain through the large Haynesville shale acquisition and related LNG options, the plan to rely on upstream gas and LNG facilities to capture future demand leaves cash flows exposed if decarbonization policies, customer preferences or technology reduce hydrocarbon usage faster than expected..."
Explore why this Narrative puts Mitsubishi at 61% overvalued.
Mitsubishi’s valuation still hinges on one unresolved question
Share prices and earnings only tell part of the story for Mitsubishi, because the people directing capital and the way their pay is structured can heavily influence what happens next. See who runs Mitsubishi and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com