


APA Corporation has delivered a powerful share price run, and the current quote raises a straightforward question for holders and watchers alike. Is the recent strength in APA stock still aligned with what the business earns today.
- Over the past 1 year, APA has returned 111.3%, which puts the spotlight squarely on whether that gain is supported by the company’s earnings power.
- The group’s ability to turn its resource base into consistent profits, and then into cash that can cover reinvestment and shareholder returns, can heavily influence how much investors are prepared to pay for each dollar of APA earnings.
- The analysts covering APA have run their own numbers. See what analysts think APA's shares could be worth.
The stock’s next move may depend on whether APA’s current share price is reasonable when set against the earnings the business is generating today.
If you are testing whether APA's 111.3% 1 year run still lines up with its earnings, it can help to compare it with other stocks filtered through the same lens using 35 high quality undervalued stocks.
Is APA Still Cheap on Earnings?
The P/E ratio is a useful lens for APA because earnings remain a key anchor for how investors weigh this kind of oil and gas producer.
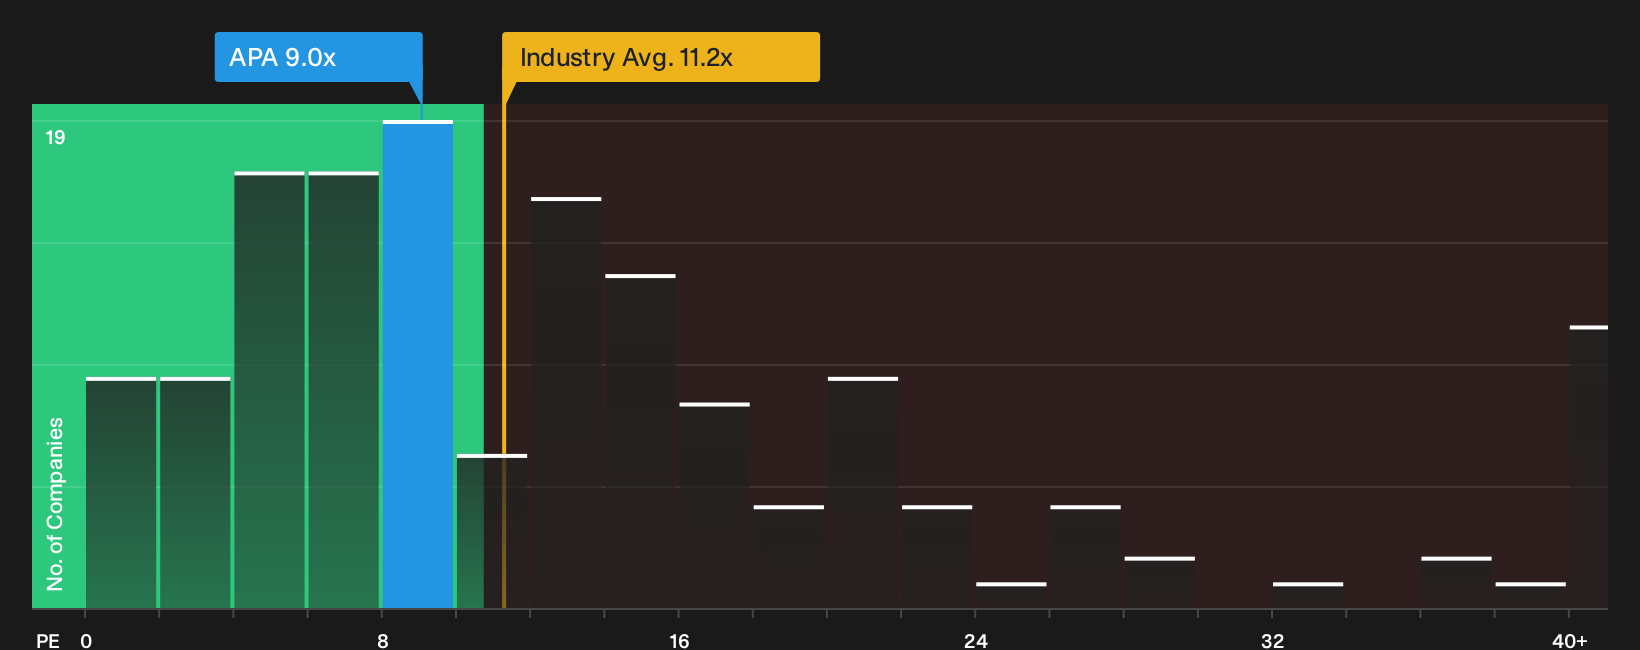
APA trades on a P/E of 9.0x, which is below the Oil and Gas industry average of 11.2x and also below the broader peer group on 17.9x. The tailored fair multiple, which adjusts for APA’s own growth profile, profitability and risk, points to a higher P/E than where the stock is currently priced. That gap suggests the market is asking a lower price for each dollar of APA earnings than this framework would indicate. Explore the numbers behind APA's P/E valuation.
The APA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where APA's P/E puzzle leaves off by spelling out which paths for APA's future earnings, margins and reinvestment would need to play out for the stock to look materially more expensive or cheaper than it does today on the Community page. Each scenario ties a fair value estimate to a clear story about potential catalysts and setbacks, so you can watch over time which version of events seems to match how APA's business actually develops.
APA brings out a clear split in the community, with one camp focused on cost and project execution upside and the other more alert to gas price and timing risks.
Bull case: 9% undervalued
"Strong operational improvements, including capital efficiencies in the Permian and Egypt, are now reinforced by APA targeting about US$500 million of annualized run-rate savings..."
Discover why this Narrative puts APA at 9% undervalued.
Bear case: 20% overvalued
"The numbers imply that APA's share price already reflects successful execution on cost savings, stable production from the Permian and Egypt, and meaningful future cash flow from Suriname and frontier exploration..."
Explore why this Narrative puts APA at 20% overvalued.
Before making a move on APA, there is one more piece of the puzzle
Price tags and earnings multiples only tell part of the story for APA, because the people steering the business and the way their pay is structured can heavily shape what happens next. See who runs APA and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com