


Semiconductor giant Marvell Technology (MRVL) has pitched an acquisition of optical and photonic products manufacturer Lumentum Holdings (LITE). This brings Lumentum’s lasers, optical transceivers, and optical circuit switches (OCS) to Marvell’s switching, electrical and optical interconnects, and custom XPUs. While the strategic rationale is sound, investors did not like the deal.
The $115 billion all-stock acquisition announcement led to a 12.7% intraday drop in MRVL stock and an 18.6% decline in LITE stock on Nov. 2. Marvell shareholders voiced concerns about share dilution, as Lumentum holders will receive 4.5 Marvell shares per Lumentum share, leaving them with 33% of the combined company. That is expected to materially increase Marvell’s share count and dilute existing holders. Lumentum shareholders are concerned because the deal would convert their ownership from a stand-alone AI optics company to Marvell shares.
Amid all this, Wedbush analyst Matt Bryson believes the deal, set to close in the first half of 2028, might not actually happen. Beyond the regulatory approval process and China’s reluctance to approve major technology mergers, lasers are in tight supply, with Lumentum currently supplying Marvell’s competitors.
As the deal drives sentiment around the two stocks, let's take a closer look at them.
The One Carrying Out the Acquisition: Marvell Technology (MRVL)
Marvell is a fabless semiconductor company that designs, develops, and sells data-infrastructure chips for data centers, cloud computing, networking, storage, security, and communications. Headquartered in Wilmington, Delaware, the company has a market capitalization of $154.05 billion.
Marvell’s stock has risen over the past year mainly because investors see it as a major beneficiary of hyperscalers’ spending on AI data centers. Over the past 52 weeks, MRVL stock has gained 48%, while it has risen 62% year-to-date (YTD). The company’s shares reached a 52-week high of $329.88 on June 18, but are down 58% from that level. However, the stock has dropped 37% over the past five days, mainly due to investor skepticism about the Lumentum deal and a broader selloff in chipmakers and AI stocks.
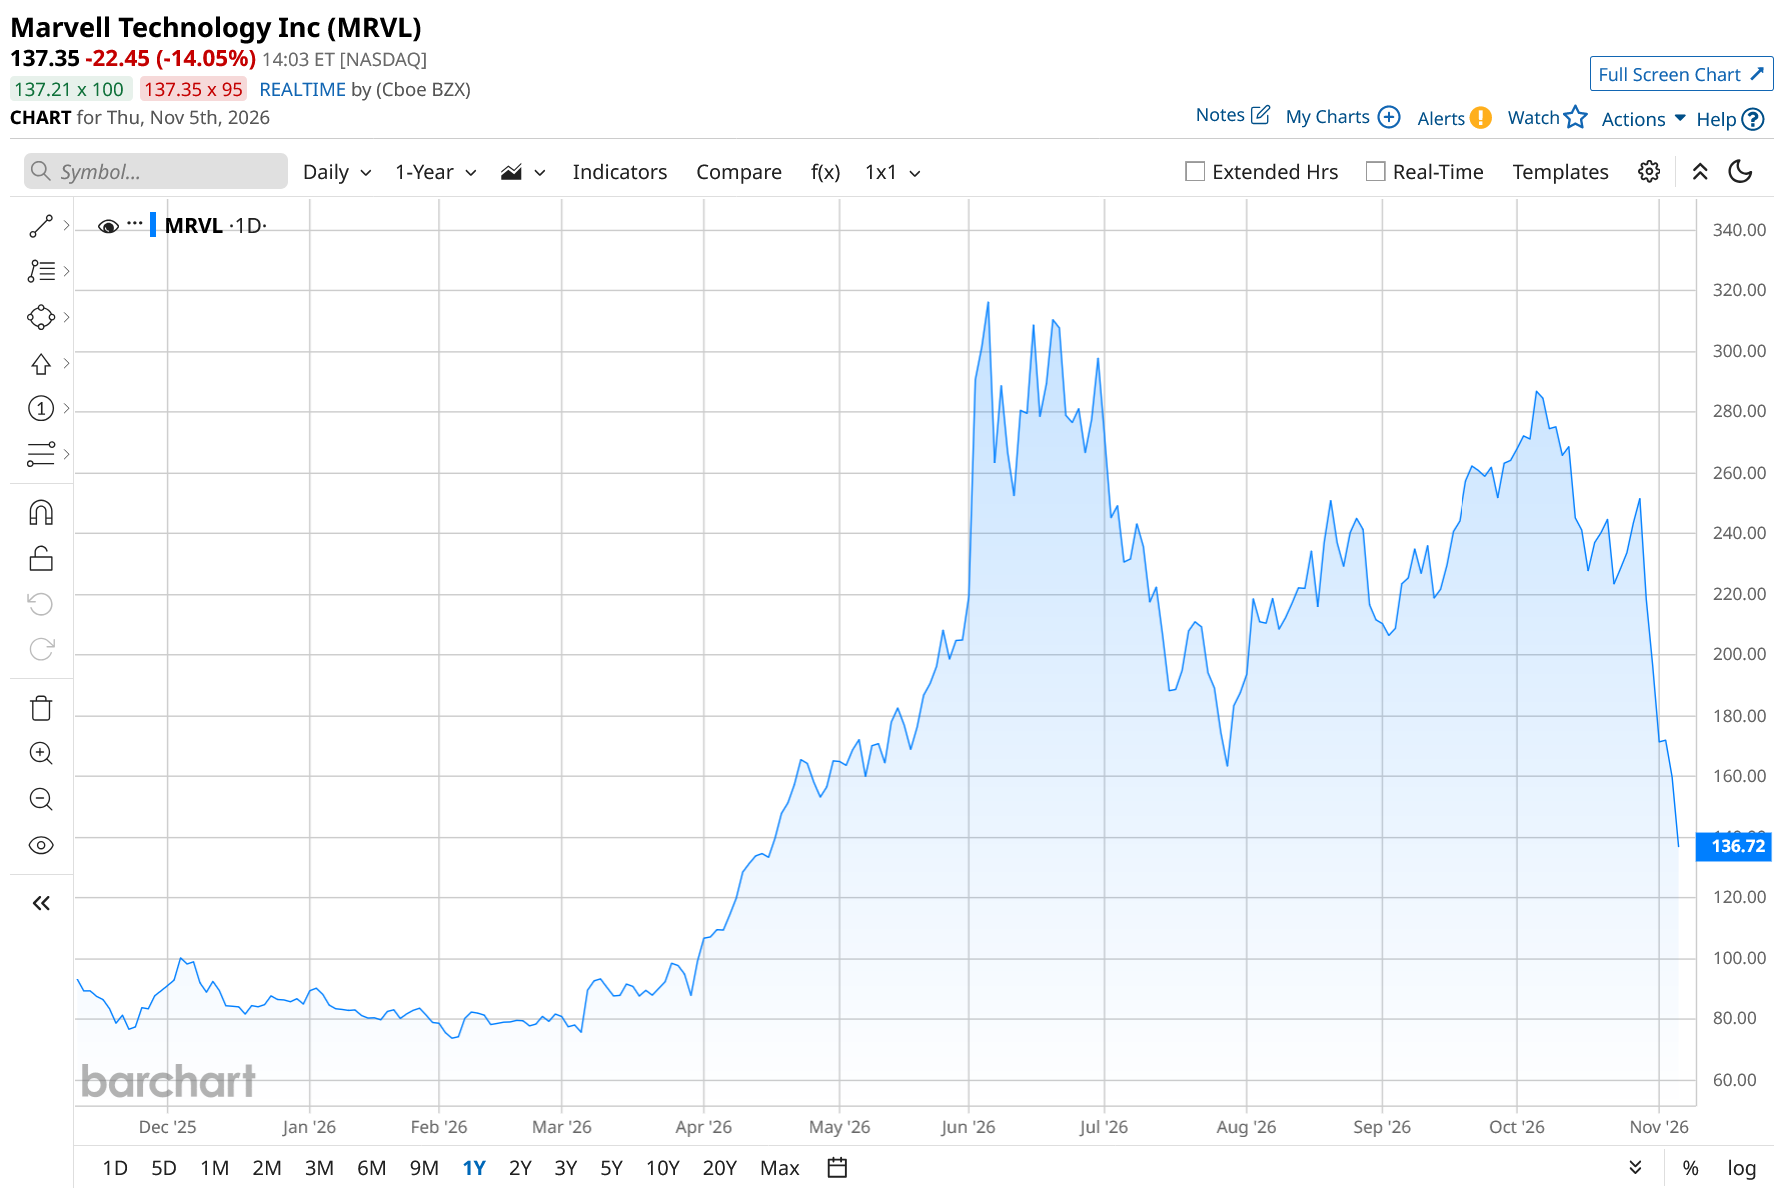
Despite the recent selloff, Marvell’s stock still doesn’t come cheap. On a forward-adjusted basis, its price-to-earnings (non-GAAP) ratio of 56.37x is higher than the industry average of 21.21x.
In the second quarter of fiscal 2027 (quarter ended Aug. 1), Marvell reported strong results driven by demand in its data center portfolio, in which the company reported a 46% year-over-year (YoY) growth. Its AI-related bookings remained robust, which is expected to continue creating tailwinds for its top line. Data centers now make up 79% of its revenue. The company’s total revenue increased 37% YoY to $2.74 billion. Its adjusted EPS rose 40% from the prior-year period to $0.94.
Wall Street analysts are robustly optimistic about Marvell’s future earnings. They expect the company’s EPS to climb 27.4% YoY to $0.79 for the third quarter of fiscal 2027. For fiscal 2027, EPS is projected to surge 41.2% to $3.05, followed by a 99.7% growth to $6.09 in fiscal 2028.
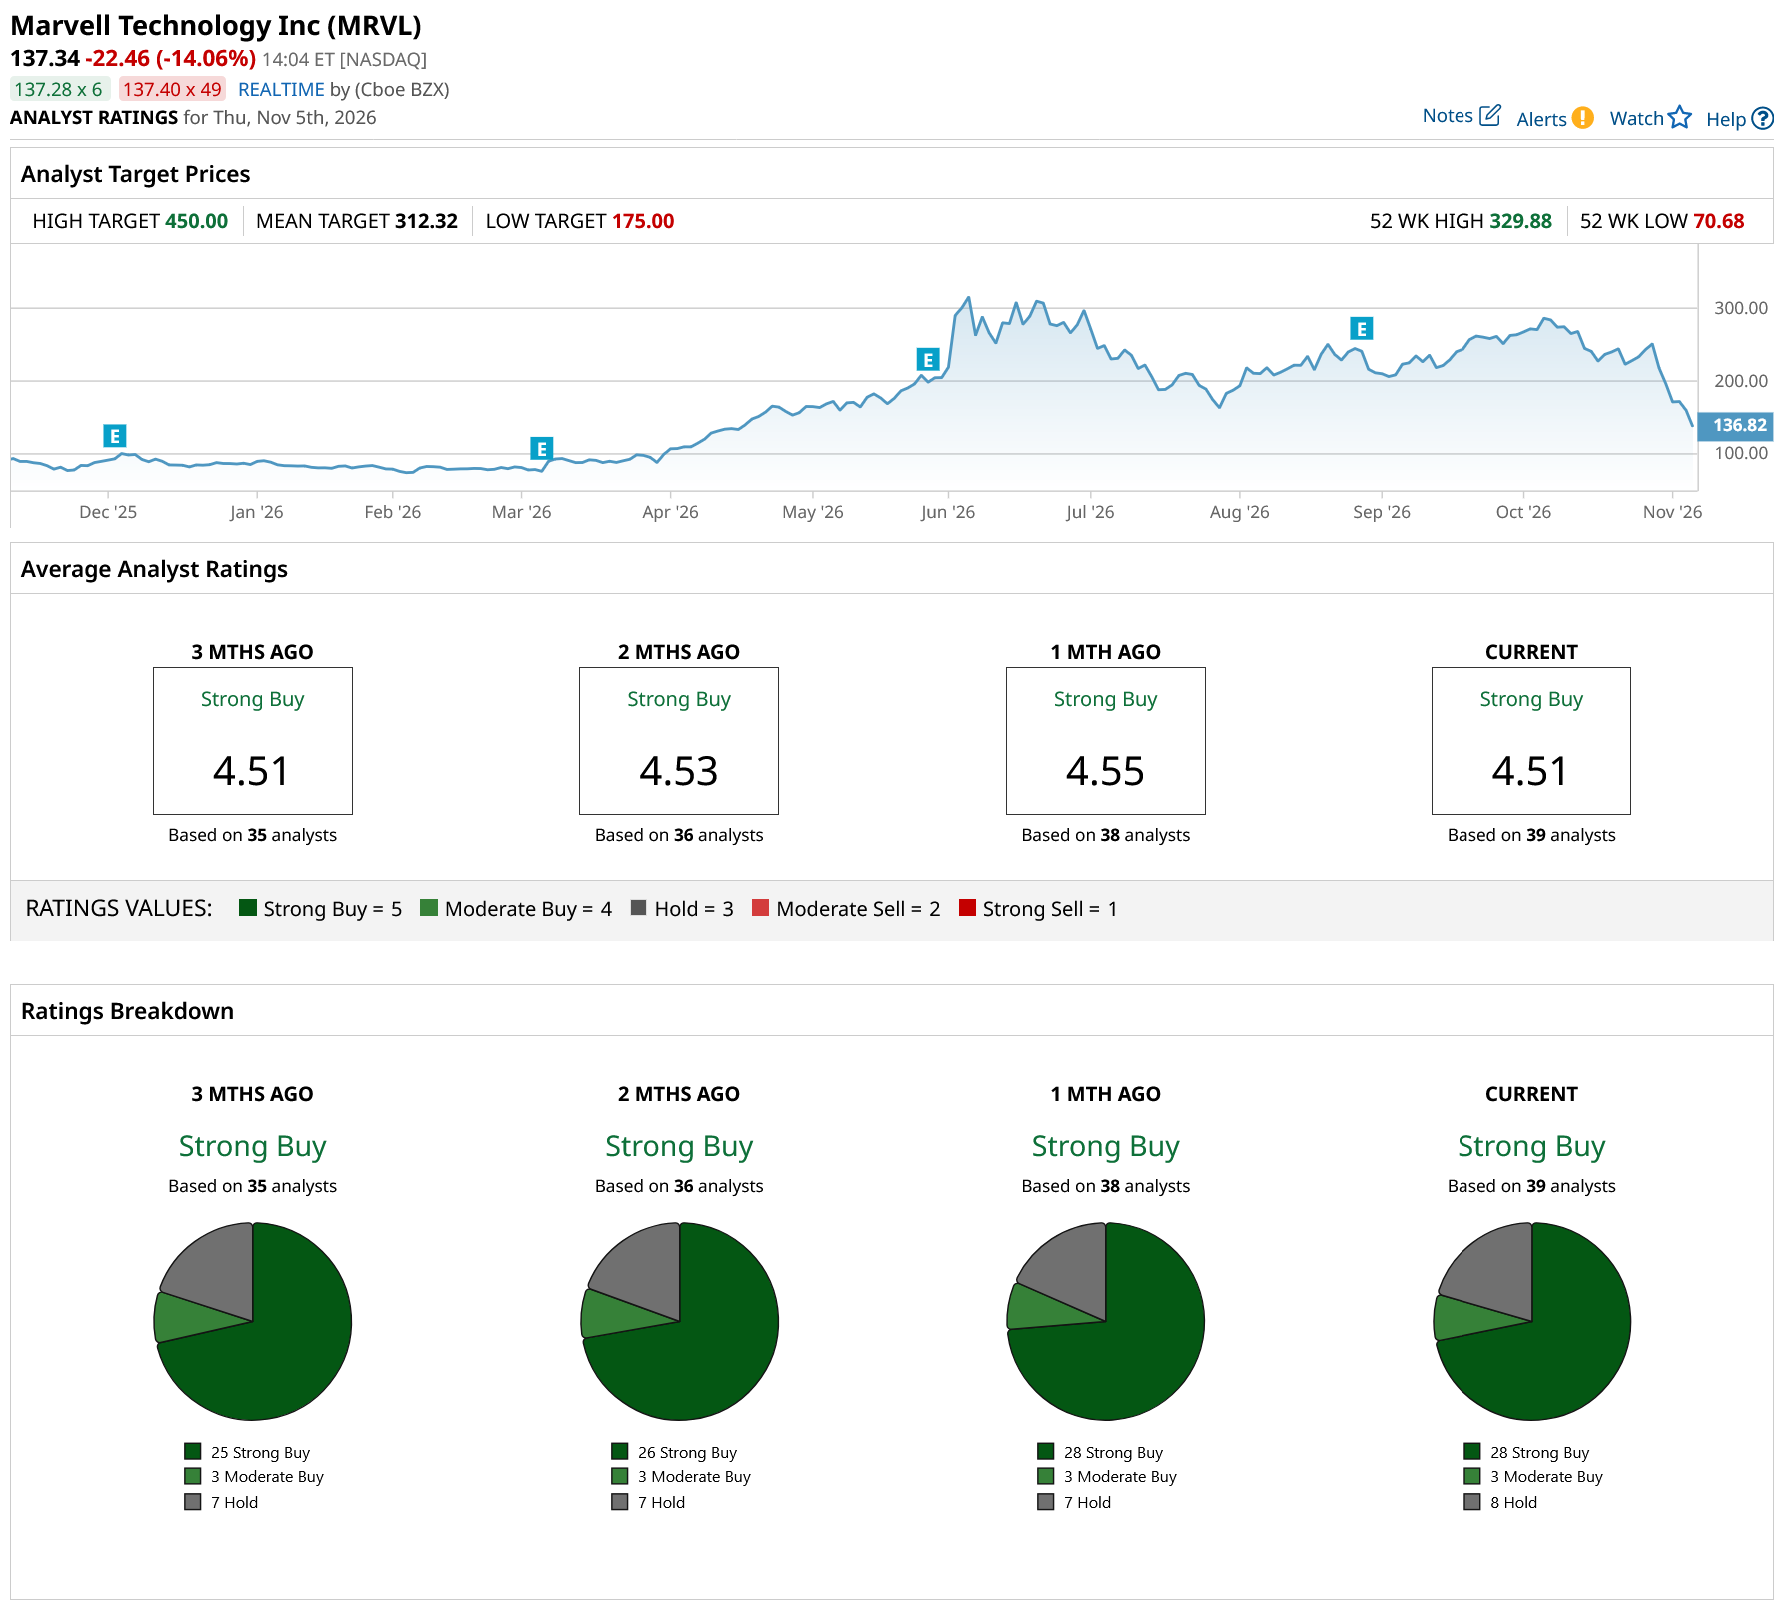
Marvell is gaining praise on Wall Street, with analysts awarding it a consensus “Strong Buy” rating overall. Of the 39 analysts rating MRVL stock, 28 have given it a “Strong Buy” rating, three analysts rated it a “Moderate Buy,” and eight took a middle-of-the-road approach with a “Hold” rating. The consensus price target of $317.05 represents an 131% upside from current levels. The Street-high price target of $450 implies a 229% upside.
The One Being Acquired: Lumentum Holdings (LITE)
Lumentum designs and manufactures optical and photonic technologies, including high-performance lasers, modules, and optical subsystems. Its products support data-center connectivity for AI and cloud computing, telecommunications networks, industrial manufacturing, and sensing applications. Headquartered in San Jose, California, Lumentum operates research, manufacturing, and sales facilities worldwide. The company has a market capitalization of $61.68 billion.
Due to explosive AI optics demand, Lumentum’s stock has gained 126% over the past 52 weeks, while it has been up 43% YTD. Like Marvell, Lumentum’s stock is also deep in the red, down 43% over the past five days due to both the same skepticism regarding the deal and the aforementioned broader selloff hitting most AI-related stocks. LITE stock reached a 52-week high of $1,143 on Oct. 9, but is down 54% from that level.
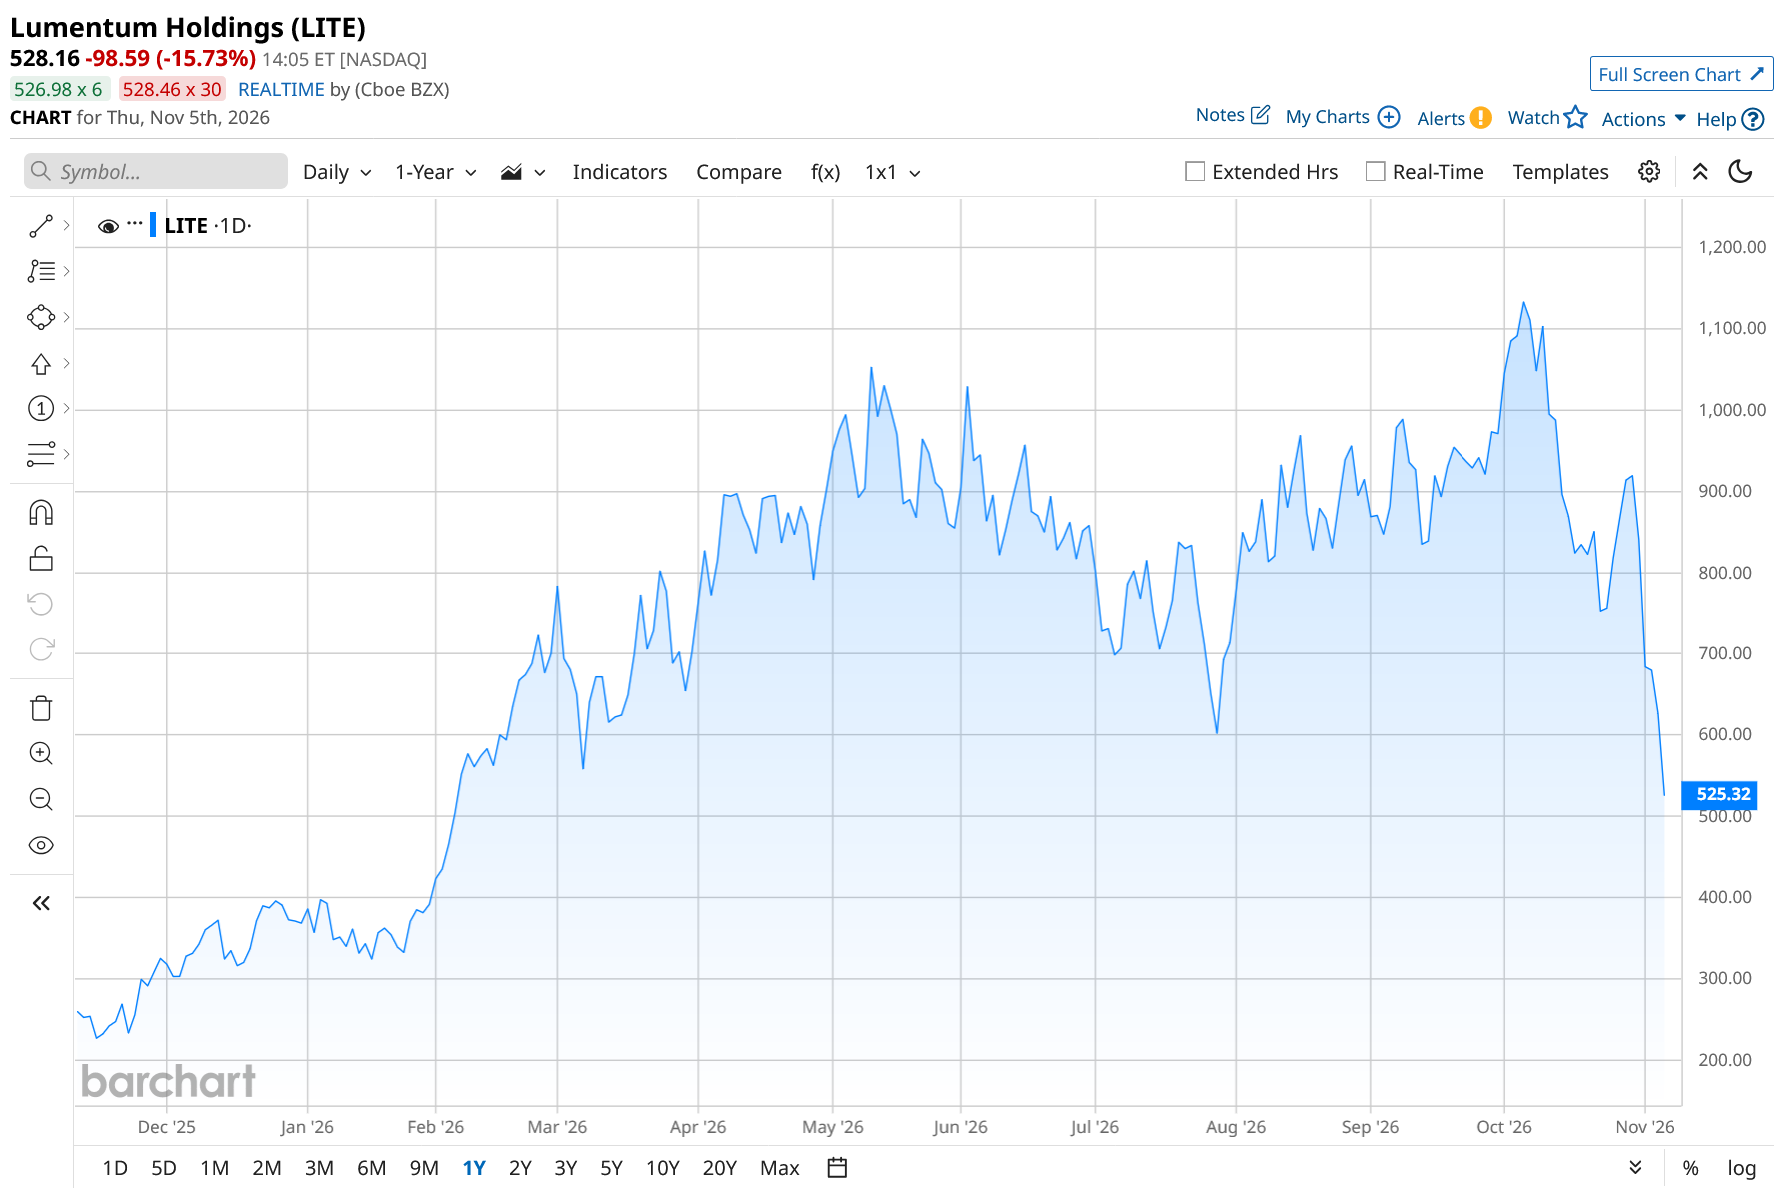
On a forward-adjusted basis, Lumentum’s stock has a price-to-earnings (non-GAAP) ratio of 34.36x, which is higher than the industry average of 21.21x.
For the first quarter of fiscal 2027 (quarter ended Sept. 26), Lumentum reported growth across all businesses, with pump lasers and OCS being the leading contributors. The company also reported greater OCS demand visibility, positioning optical switching as a multi-billion-dollar annual revenue stream. The company’s total revenue increased 136.5% YoY to $1.26 billion, while its non-GAAP EPS increased from $1.10 to $4.57 over the same period.
Wall Street analysts are strongly optimistic about Lumentum’s future earnings trajectory. They expect the company’s EPS to climb 271% YoY to $4.60 for the current quarter. For fiscal 2027, EPS is projected to surge 143.5% to $19.80, followed by a 67.8% growth to $33.23 in fiscal 2028.
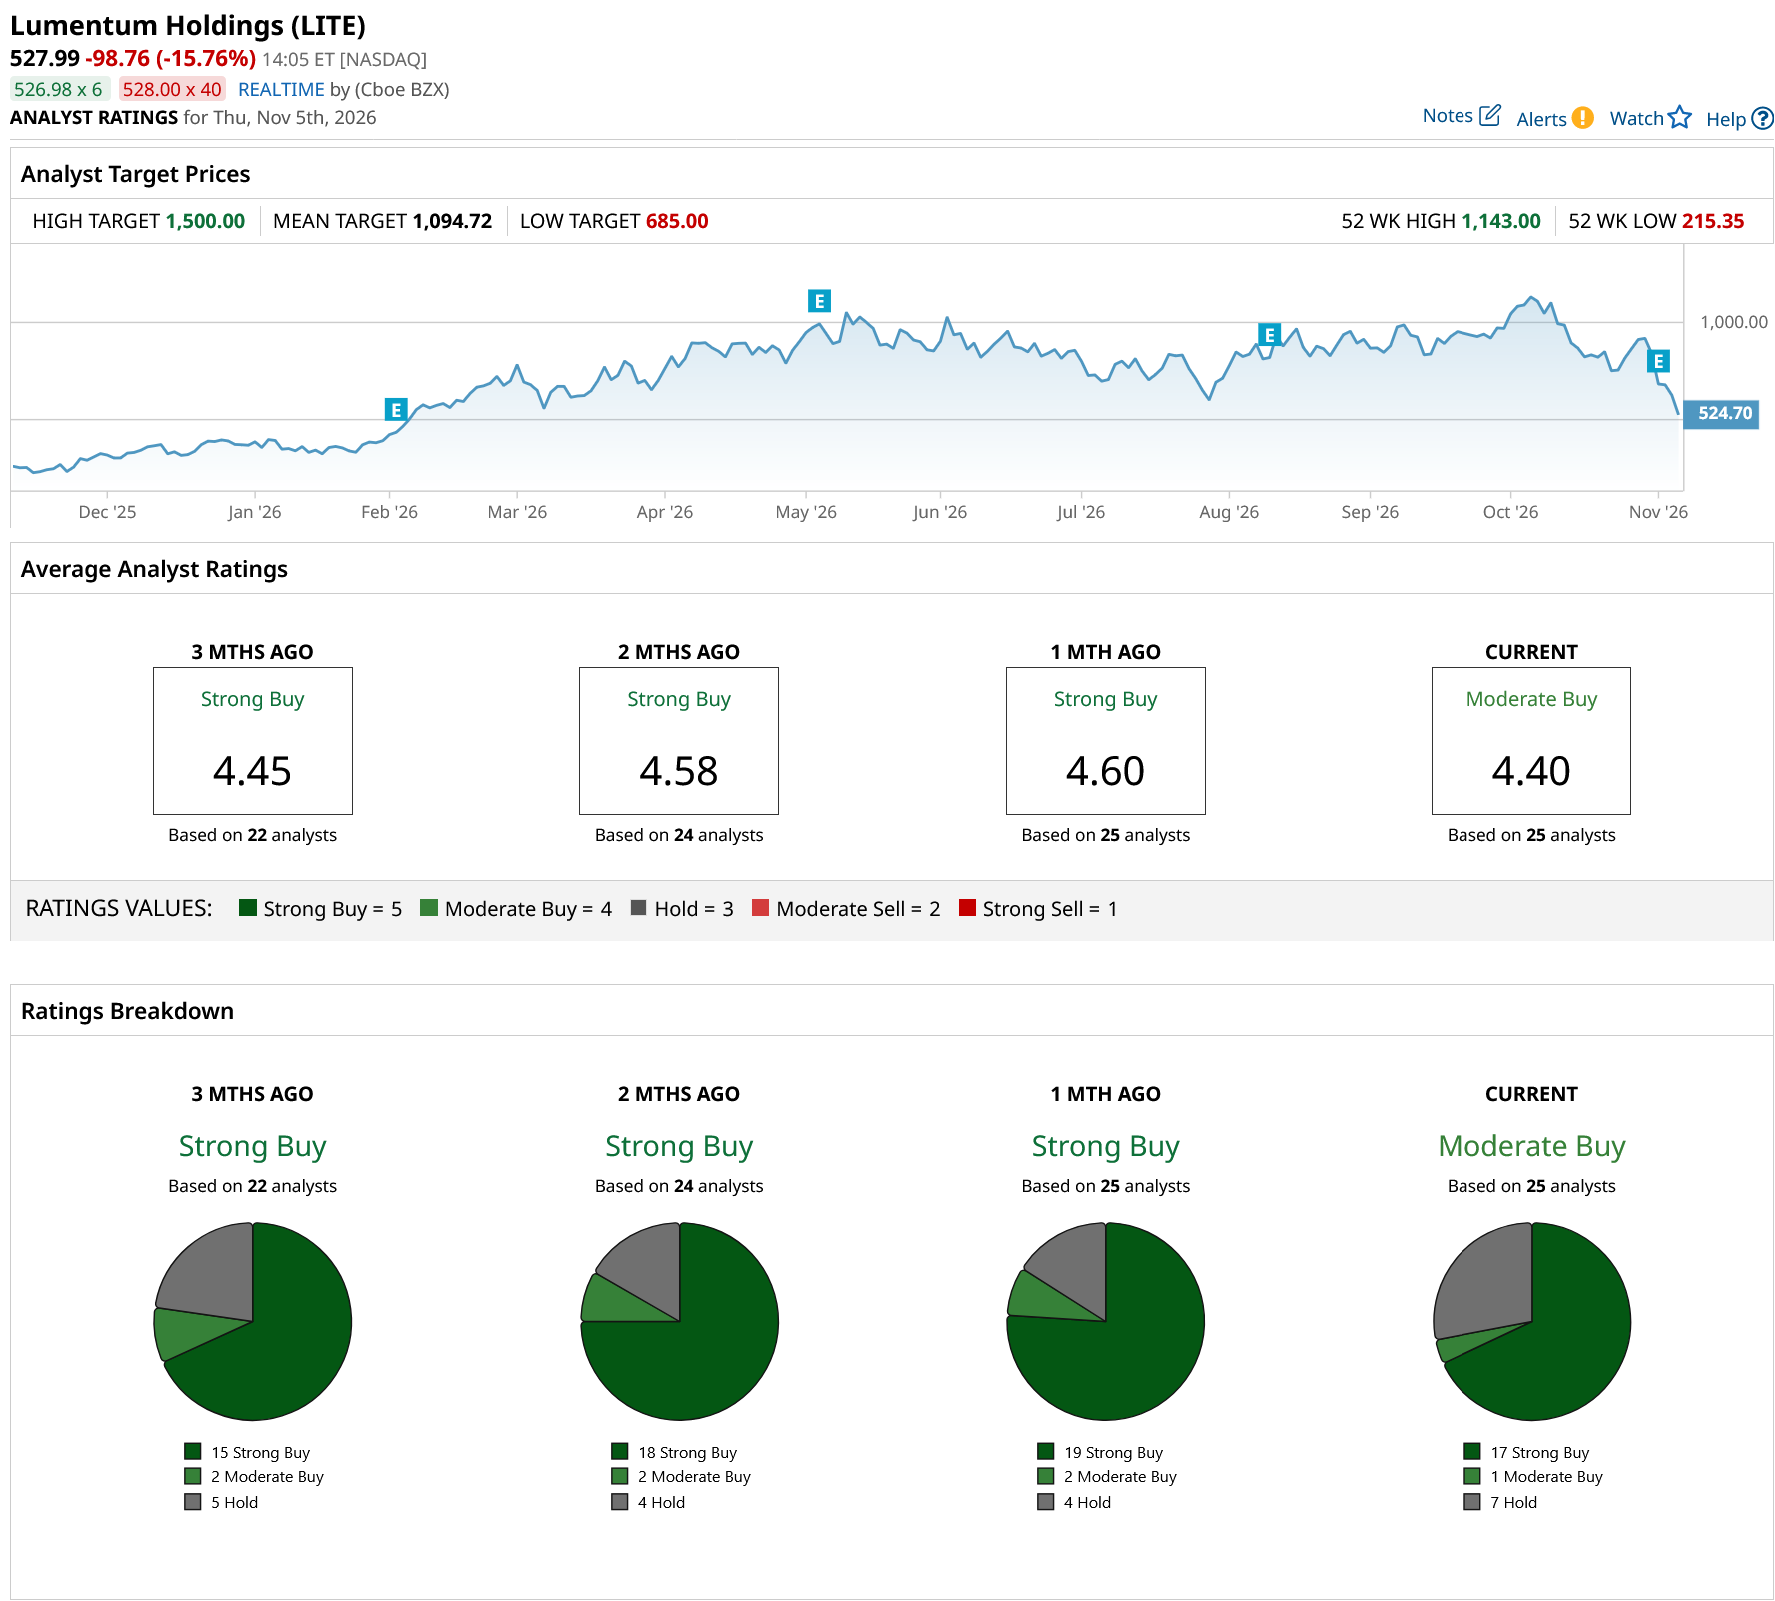
Lumentum’s stock has become a popular name on Wall Street, with analysts awarding it a consensus “Moderate Buy” rating. Of the 25 analysts rating LITE stock, 17 analysts have rated it a “Strong Buy,” one analyst rated it a “Moderate Buy,” and seven analysts gave a “Hold” rating. The consensus price target of $1,094.72 represents a 107% upside from current levels. Moreover, the Street-high price target of $1,500 indicates a 184% upside.
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.