


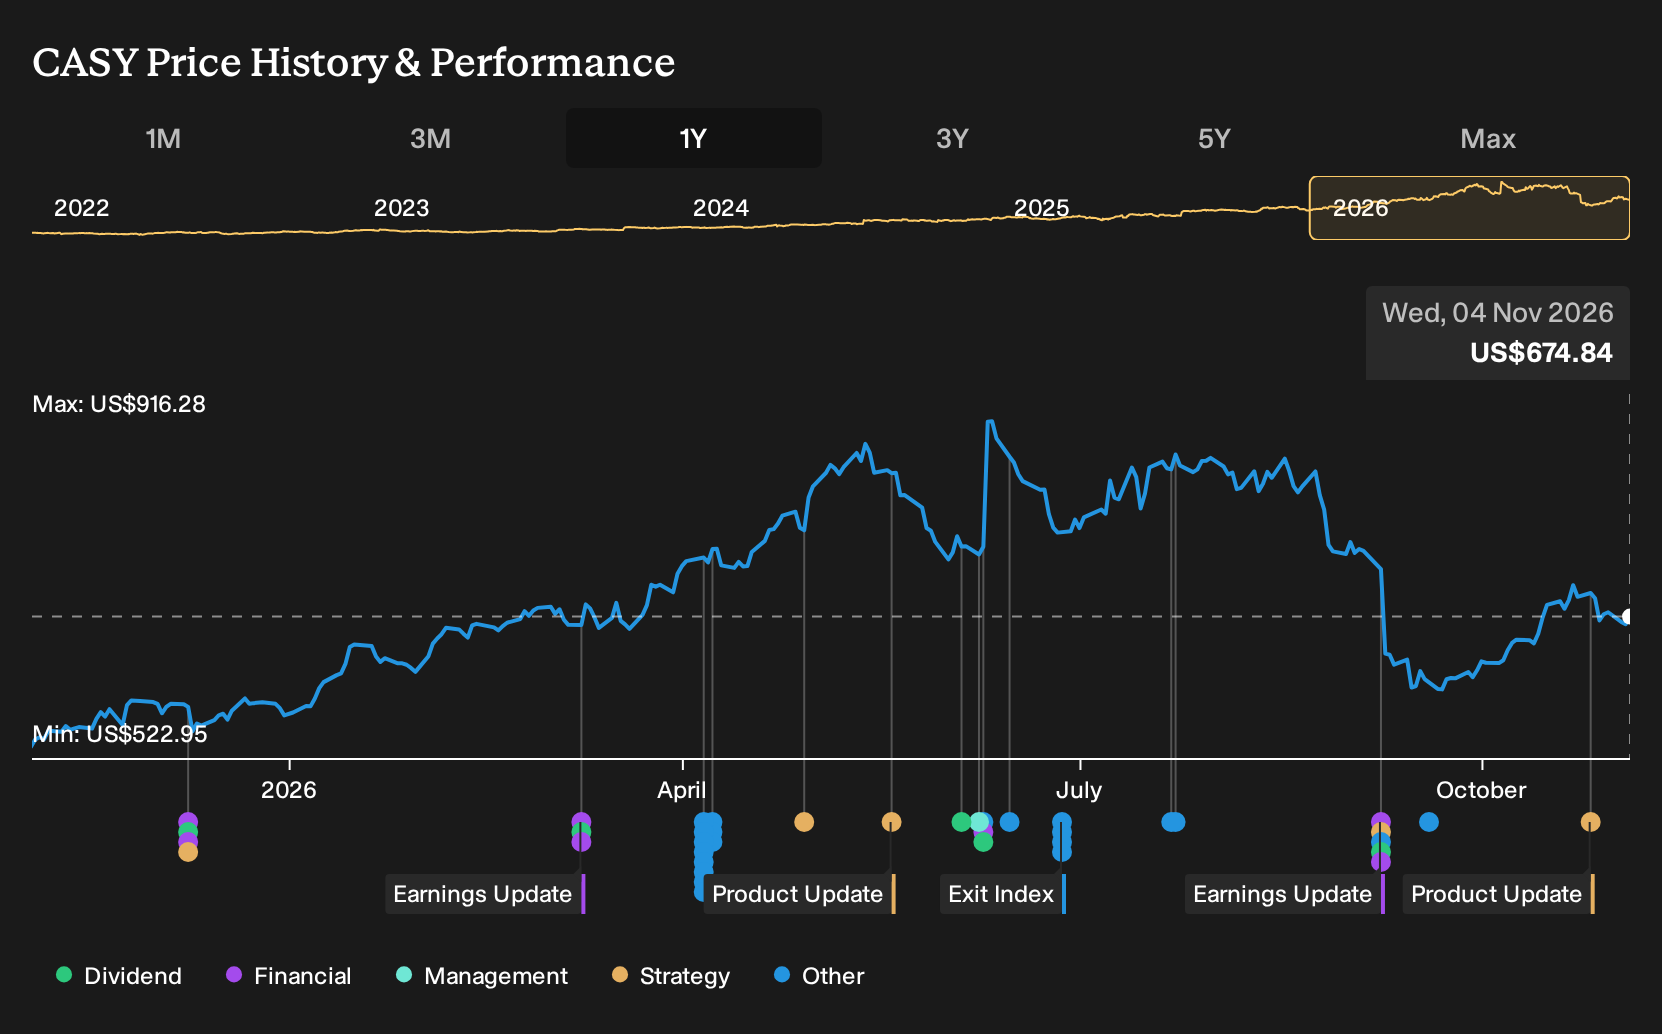
Casey’s General Stores kept landing upbeat headlines in 2026, from S&P 500 inclusion to fresh acquisition announcements, yet the share price still swung around key earnings dates. Holding Casey's General Stores over the past year would have returned 29.4%, including dividends. If you had put money to work on 4 November 2025, with bulls and bears split on valuation and acquisition risks, what exactly in the record justified taking that ride?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made Casey's General Stores harder to judge, start where the gap is still open and scan 35 high quality undervalued stocks.
The Argument You Would Have Been Weighing On Casey's General Stores
The shares cost US$523 at the start of the period, and investors in Casey's General Stores had to decide which story deserved more weight.
The bullish Narrative put Fair Value at US$571, built on assumed revenue growth of 6.0% and profit margins reaching 4.0%, with acquisitions and prepared foods expected to support those numbers.
The bearish view pointed to a Fair Value of US$450, stressing that integrating Fikes and CEFCO could pressure earnings as lower margin stores and extra costs strained profitability.
What The Results Changed For The Casey's General Stores Thesis
The clearest test of the Casey's General Stores story came from Q1 2027 numbers. Revenue moved from US$4,567.106m in Q1 2026 to US$5,678.336m and net income rose from US$215.355m to US$273.72m, with net margin edging from 4.7% to 4.8%. That pattern supported the case for growth and profitability, although only with a narrow margin improvement.
The key factor here was the margin assumption. Future forecasts on Casey's rely on small percentage shifts in profitability, so for any other retailer using acquisitions and prepared food as a driver, the figure to watch is net margin in each set of results.
What Casey's General Stores Buyers Are Paying For After A 29% Run
Casey's General Stores now trades at US$675, after a 29.4% gain over the past year from US$523. The selected Narrative still places Fair Value above that level and frames today’s quote as a test of how much faith you put in its operating playbook.
That thesis leans on rural store expansion, higher margin prepared food and technology driven cost control. The key question for anyone paying today’s price is whether prepared food and beverage sales can continue to offset rising operating expenses over the coming years.
"The main thing that has to go right is that Casey's continues to grow higher margin prepared food, beverages, and nicotine alternatives fast enough to offset category headwinds and rising operating expenses."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 25% below our estimate - embeds AI assistants into productivity platforms to streamline standardized enterprise workflows.
- Company 2 - 33% below our estimate - extends a substantial gold resource base by exploring and converting findings into reserves.
- Company 3 - 40% below our estimate - converts subsea project backlogs into higher margin equipment contracts and recurring service work.
That is three of the list. See every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com