


AI hungry data centers are pulling in hardware at record pace, even as freight, fuel and tariff costs reshuffle who actually benefits along the supply chain. That mix of strong demand signals and rising input pressure is already feeding through to large hardware producers and the logistics groups that move their gear. This article examines three stocks exposed to that news, and explains how current conditions might affect patient investors.
The stocks covered below are only a small sample of the opportunities linked to AI focused data center hardware. The full screen surfaces 48 more companies that carry similarly detailed stories that are not included in this article. If you want to identify and analyze the highest conviction ideas for your own watchlist, head straight to the AI-Driven Data Center Hardware and Infrastructure Beneficiaries screener.
MiTAC Holdings (TWSE:3706)
MiTAC Holdings is a Taiwan based hardware producer tied directly to AI data center build outs through its AI and cloud servers, HPC systems and storage platforms. Cloud computing products generated about NT$115.9b of its roughly NT$128.1b segment revenue, with automotive electronics and AIoT adding NT$9.2b, and other activities NT$3.1b. The group’s market value is about NT$103.2b.
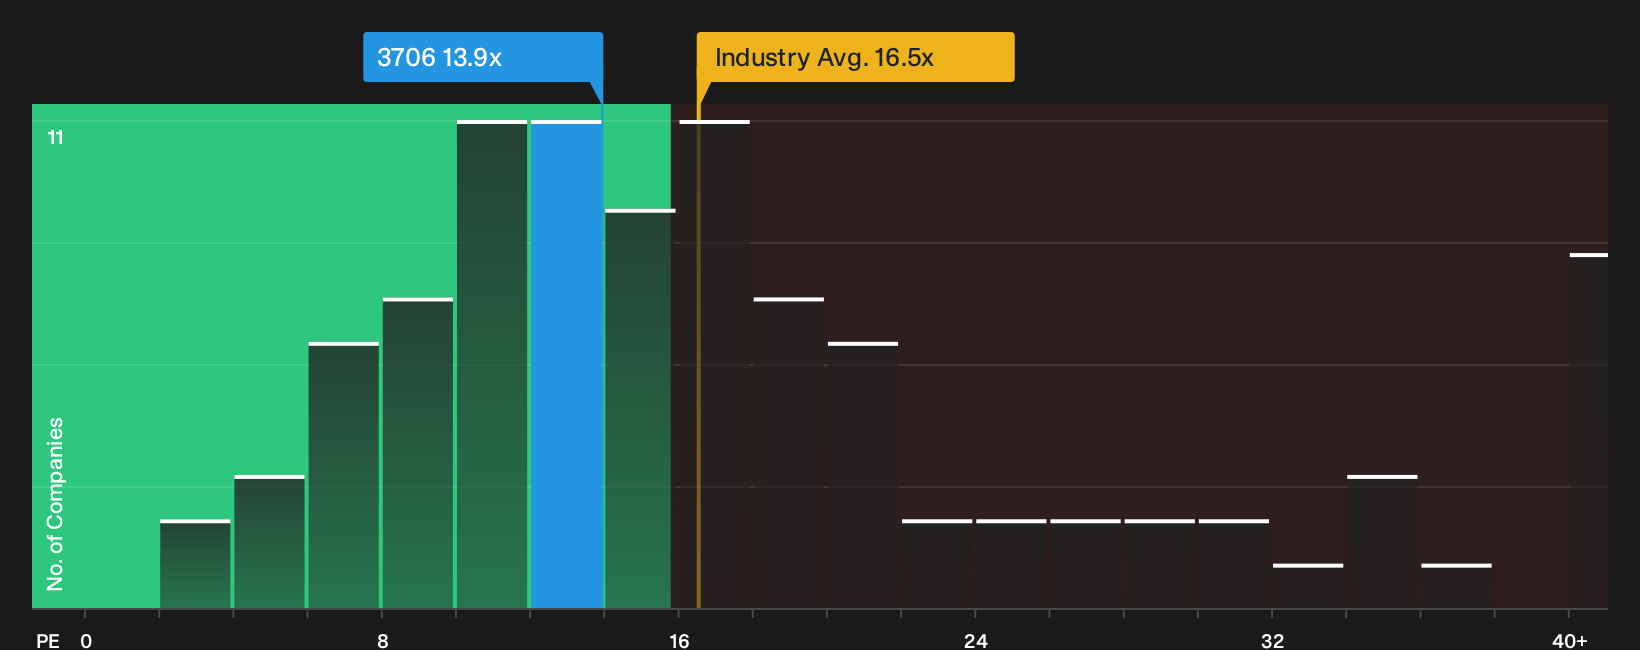
MiTAC Holdings provides targeted exposure to the racks and boxes inside AI data centers, from AI servers to storage hardware. It trades at a P/E of 13.9x, which is below both the Taiwan market and tech sector. That combination of AI infrastructure demand and one unresolved pressure on cash generation and leverage could be important for how future returns compare with expectations.
That tension between valuation, cash generation and leverage is exactly what you need to weigh. Start with the 3 key rewards and 2 important warning signs (1 is major!) for the full picture investors are debating.
Asia Vital Components (TWSE:3017)
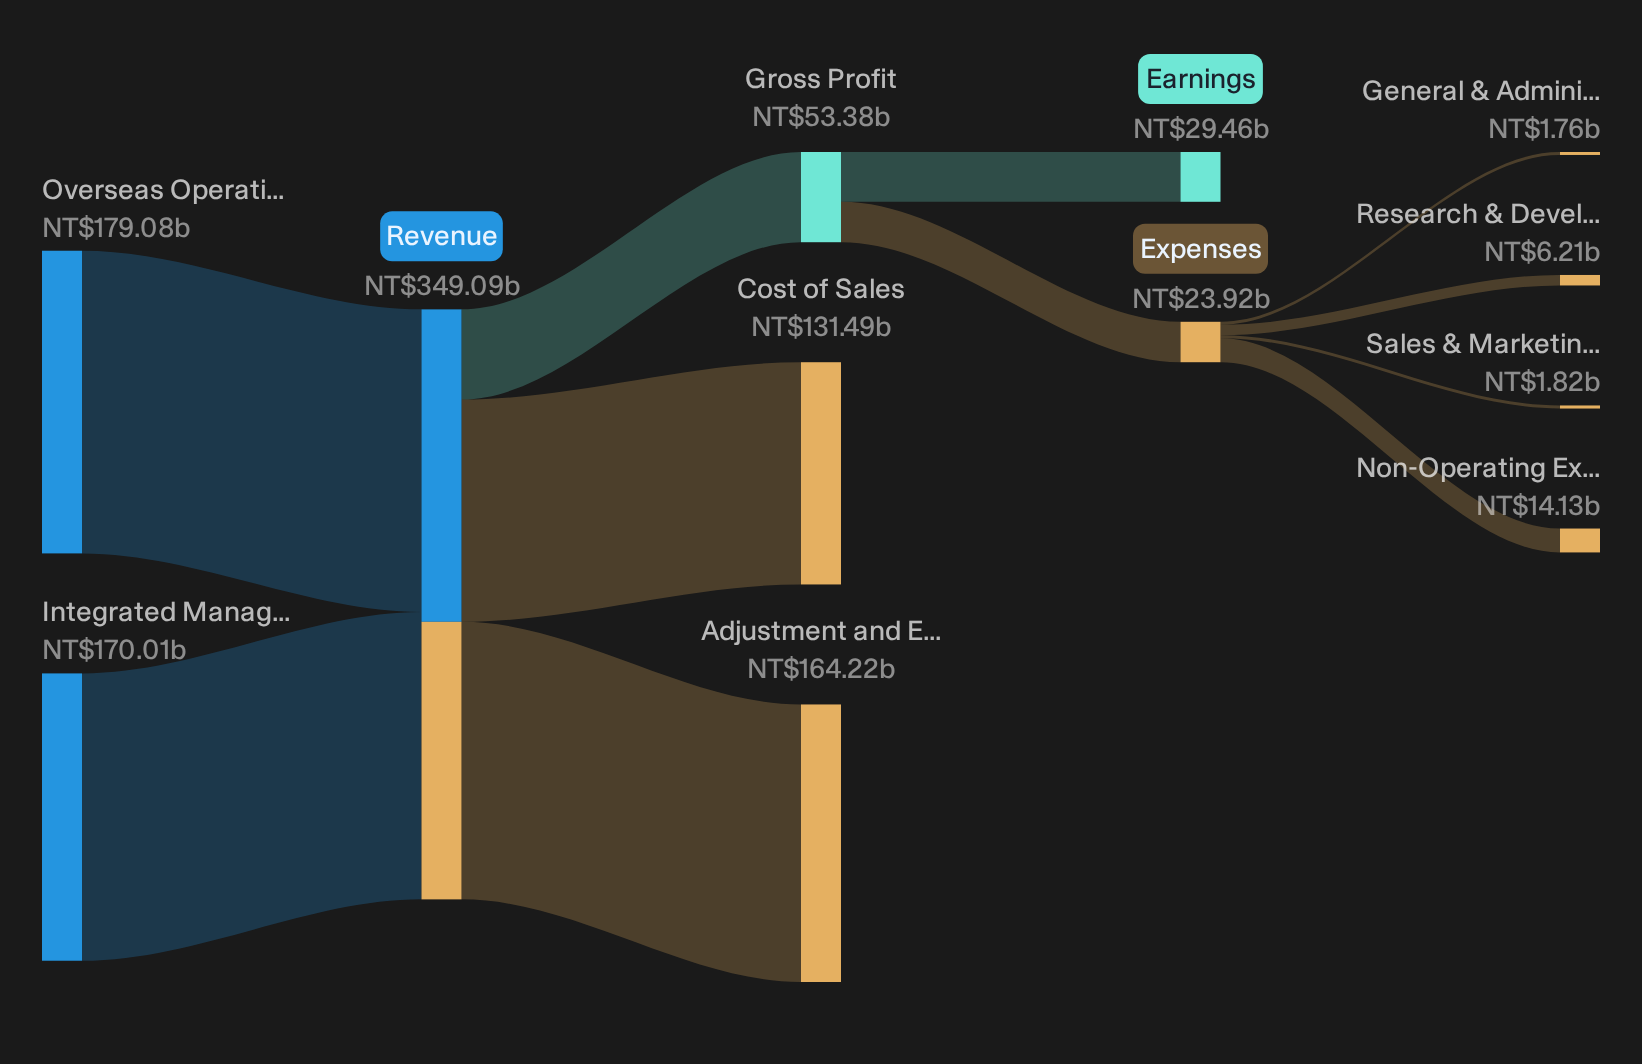
Asia Vital Components focuses directly on the heat challenges created by AI data centers, supplying the thermal hardware that allows dense GPU racks to operate without overheating. This is where the screener theme, its growing NT$179.1b overseas operations, and its NT$170.0b integrated management division connect to its roughly NT$1,006.9b market value.
"Rising demand for high power computing and wider liquid cooling adoption in data centers is increasing server related product contribution, which could support revenue scale and help sustain higher gross margin."
What matters next is how one capital intensive expansion decision shapes the balance between that demand and future profitability.
That expansion choice is the hinge. Read the full narrative for Asia Vital Components to see how Asia Vital Components balances capital intensity, AI demand, and any risks that might be masking future potential.
Gold Circuit Electronics (TWSE:2368)
Gold Circuit Electronics manufactures printed circuit boards that go into AI and advanced servers, networking gear and other electronics, placing it close to data center hardware demand. It generated about NT$77.7b from PCB manufacturing and has a market value of roughly NT$444.3b.
Gold Circuit Electronics sits on the PCB supply line for AI servers and networking equipment, with recent Q2 2026 sales of NT$24,279.31 million linked to that broader build out in data centers. Its earnings and margins give it room to keep investing in capacity, although what happens when one unseen pressure around cash conversion and funding costs shifts will be important for long term outcomes.
When that cash conversion and funding picture shifts, the 3 key rewards and 2 important warning signs (2 are major!) so you can see what current pricing might be missing on Gold Circuit Electronics.

Seeking Alternatives Before The Crowd?
Fresh ideas often move before prices. Instead of waiting on the sidelines, consider exploring potential breakout stories as they emerge. Review these under the radar picks and consider whether they fit your strategy.
- Identify relatively resilient businesses by tracking companies in the 215 resilient stocks with low risk scores that aim to keep volatility and downside pressure contained.
- Focus on income-oriented ideas by reviewing cash-generating enterprises in the 213 dividend fortresses that aim to keep payouts flowing while prices adjust for later entrants.
- Explore opportunities linked to infrastructure and power by reviewing the 41 power grid technology and infrastructure stocks that highlights operators associated with long term electricity demand trends.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com