


LTC Properties has delivered a strong share price run in recent years, which naturally raises a key question for anyone looking at the stock today. Is the current valuation properly grounded in the earnings that support this real estate investment trust?
- A return of 86.0% over the past 5 years puts real money on the line for the debate about what LTC Properties' earnings currently justify.
- The business model, which depends on collecting stable rent and converting it into dependable earnings, may support a case that the recent share price strength needs to be weighed carefully against the income it generates.
- The analysts covering LTC Properties have run their own numbers. See what analysts think LTC Properties's shares could be worth.
For investors, the debate is whether LTC Properties' recent share price level is adequately backed by the earnings power the company is producing today.
If you want a second reference point alongside LTC Properties for judging what earnings-backed pricing looks like, run the same lens over a curated list of 35 high quality undervalued stocks.
Is LTC Properties Still Cheap on Earnings?
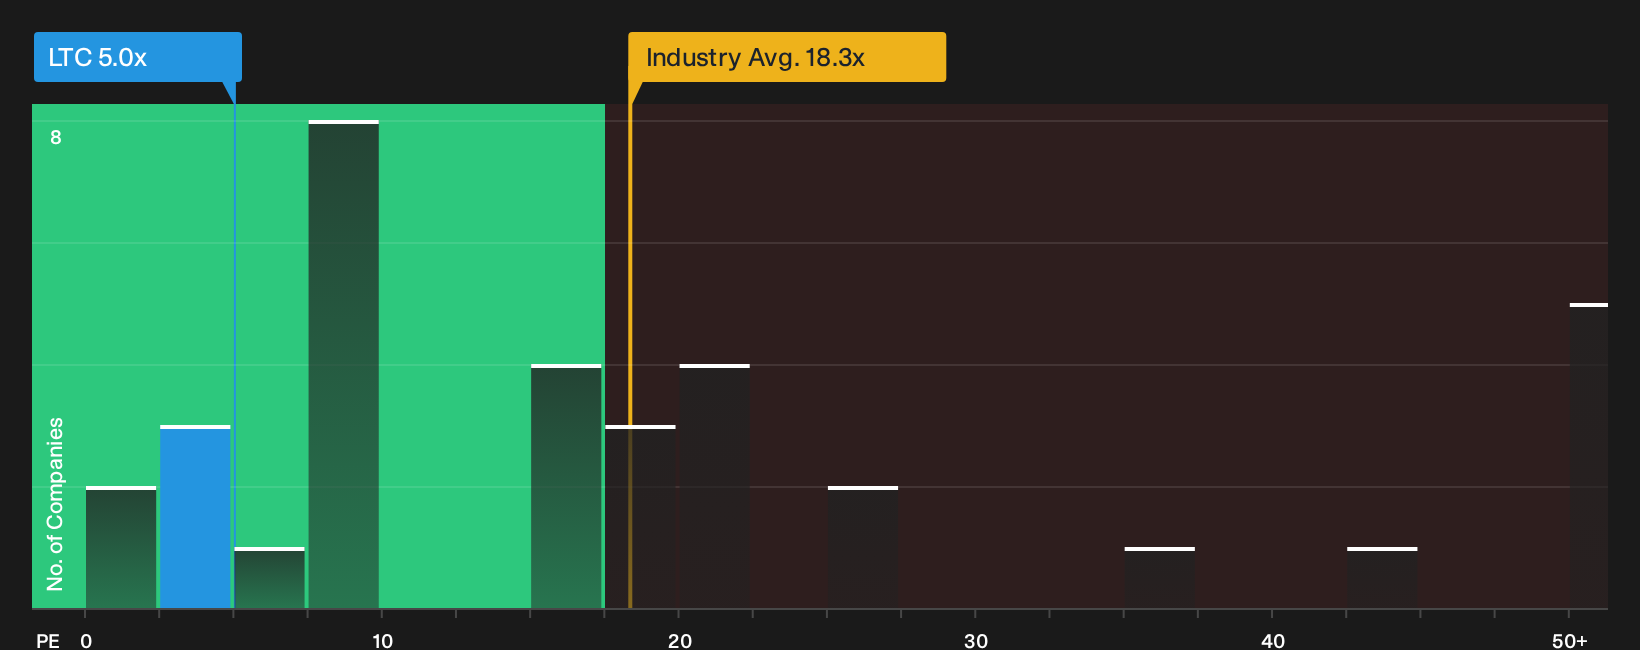
The P/E ratio fits LTC Properties because earnings are a central yardstick for a real estate investment trust that is built around recurring rent income. On this metric, the stock trades on roughly 5.0x earnings, while the wider Health Care REITs group sits closer to 18.3x. Compared with a peer set closer to 30.8x, that gap becomes even more striking for anyone benchmarking LTC Properties against other listed options in the space.
The fair P/E that a valuation model might expect for LTC Properties, after weighing its growth profile, profitability, size and risk, sits above the current multiple. That places the present P/E meaningfully below the level implied by those fundamentals, which points to a stock that screens as undervalued on this earnings yardstick. For investors comparing choices within health care real estate, this type of discount can matter for both return potential and margin of safety relative to peers. Explore the numbers behind LTC Properties's P/E valuation.
The LTC Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the LTC Properties valuation puzzle leaves off by spelling out what kind of future growth, margins and earnings power would need to apply for today’s share price to look either stretched or conservative when viewed against that earnings multiple. Each scenario ties its valuation view to a specific path for LTC Properties' growth, profitability and risk profile that you can return to as new information emerges, and they sit on the stock’s Community page.
One of the top community narratives on LTC Properties: roughly fairly valued
"The numbers imply the share price already reflects a fairly valued but bearish stance, in which strong SHOP growth, higher internal growth potential and insider buying are balanced…"
Discover why this Narrative puts LTC Properties at roughly fairly valued.
The LTC Properties share price is only one piece of the decision
The people steering LTC Properties, how they are chosen and what they are paid can strongly shape future outcomes. Yet that leadership scorecard has not been unpacked here. See who runs LTC Properties and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com