


CrowdStrike (CRWD) is pushing further into the artificial intelligence (AI) market after reaching agreements to purchase two AI cybersecurity startups, Fiddler AI and Dreadnode, for $495 million. CrowdStrike will reportedly pay $400 million for Fiddler AI and $95 million for Dreadnode.
Companies have been increasingly relying on AI agents to perform certain tasks, and CrowdStrike intends to improve its position in this growing market by acquiring firms that can help it detect and address emerging security threats associated with AI use. In particular, Fiddler monitors and explains AI agent activity, while Dreadnode uses automation technology to identify vulnerabilities prior to agent deployment.
CrowdStrike also recently launched AI Kill Switch functionality for its Falcon Guardian security tool to terminate potentially harmful AI agents. These developments will likely make CrowdStrike an even stronger player in the cybersecurity industry, despite current problems with the valuation of CRWD stock.
About CrowdStrike Stock
Based in Austin, Texas, Crowdstrike provides cybersecurity solutions including cloud-native endpoint protection, identity security, threat intelligence, and cloud workload protection. Currently, the company has a market capitalization of about $246.7 billion.
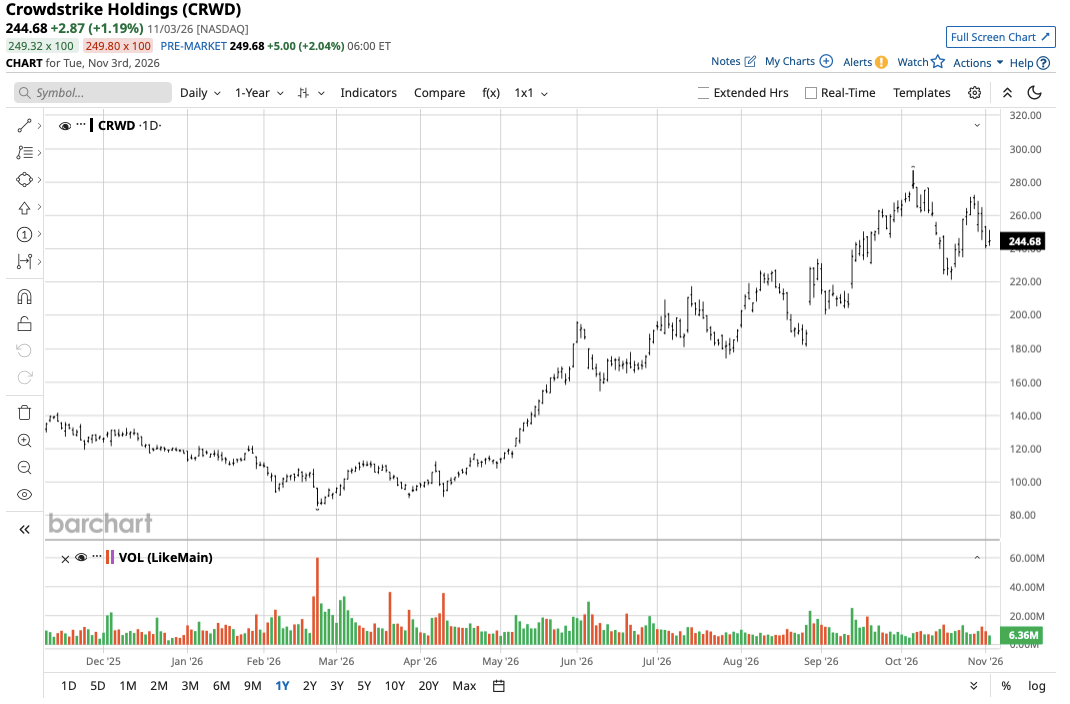
CrowdStrike stock has had a tremendous 2026, increasing about 86% year-to-date (YTD) and outperforming the S&P 500 Index ($SPX) over the same period. Shares closed at $241 on Nov. 4, closing down slightly for the day. CRWD stock has decreased by about 17% over the past five trading sessions due to increased volatility. The stock has a 52-week range of $85.68 to $286.99 per share.
The valuation has started to become a problem for CRWD stock. CrowdStrike has a price-to-sales (P/S) ratio of about 52 times, which is much higher than its cybersecurity peers. That includes Palo Alto Networks (PANW), which trades at around 24.9 times sales, and Fortinet (FTNT), which trades at about 13.8 times sales. Meanwhile, CrowdStrike's forward price-to-earnings (P/E) ratio is unusually high as well at 3,175 times, indicating that CrowdStrike's profitability is hardly in-line with its market value.
Even considering management's guidance for revenue of approximately $6 billion in fiscal 2027, CrowdStrike trades at more than 41 times expected annual sales. That means investors are already pricing in strong growth, leaving almost no margin for error.
CrowdStrike Surpasses on Profit
CrowdStrike announced solid second-quarter fiscal 2027 results on Aug. 26, earning revenue of $1.47 billion, up 26% increase from the previous year and exceeding Wall Street's expectation of approximately $1.44 billion. Adjusted EPS stood at $0.31, which was better than the consensus of $0.29, while net income reached $5.3 million against a loss of $70.2 million in the same period last year.
Perhaps more interesting, however, was the acceleration in annual recurring revenue (ARR). CrowdsStrike recorded $5.84 billion in ARR with 25% year-over-year (YOY) growth, while net new ARR came in at $333 million, up 51% YOY. This is important because recurring subscription revenue provides more visibility into future performance. CrowdStrike also reported operating cash flow of $530 million and free cash flow of $377 million.
In terms of CrowdStrike's outlook, management guided fiscal Q3 revenue between $1.523 billion and $1.529 billion, which is above the consensus estimate of $1.51 billion. Adjusted EPS is expected to be $0.31, broadly in line with consensus estimates. For full-year fiscal 2027, management raised its revenue guidance to between $5.991 billion and $6.011 billion and its adjusted EPS guidance to $1.25 to $1.26.
Meanwhile, the company's latest acquisition plans should attract investors' attention. CrowdStrike had approximately $5.01 billion in cash and cash equivalents at the end of July. The recently reported acquisition cost of $495 million is less than 10% of that number.
Fiddler's technology will reportedly become Falcon Observe, while Dreadnode will expand automated security testing. Combining those capabilities with its AI Kill Switch, CrowdStrike is moving beyond protecting IT infrastructure to securing AI agent activity itself.
The potential looks attractive, but how much additional ARR these acquisitions will generate for the company remains to be seen. The company hasn't disclosed the revenue contributions of either firm, while the integration of their technology with Falcon should be monitored as well.
What Do Analysts Expect for CrowdStrike Stock?
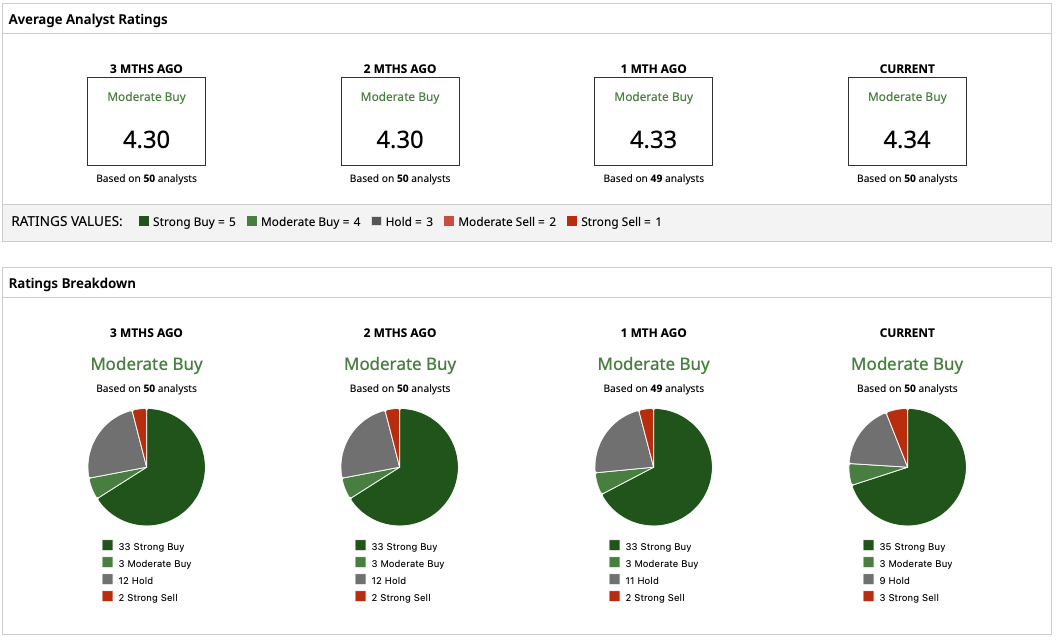
Wall Street still sees strong potential in CrowdStrike, assigning CRWD stock with a consensus "Moderate Buy" rating overall based on 50 analysts with coverage. Analysts give the stock an average recommendation score of 4.34 out of 5, while the average price target of $255.34 indicates potential upside of 15% from current levels.
On the date of publication, Yiannis Zourmpanos did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.