


Telix Pharmaceuticals (ASX:TLX) has become a talking point after joining the Thera4Care initiative in Europe, with its FAP-targeting therapy TLX400-Tx selected for a Phase 1 trial using terbium-161.
The Thera4Care announcement lands after a volatile spell for Telix Pharmaceuticals, with the 1-day share price return of 5.71% and 7-day share price return of 4.45% partly reversing a 30-day share price decline of 8.63% and a 90-day share price drop of 13.03%.
Scan for other late-stage oncology players with strong insider alignment by jumping into our hand-picked 14 high quality undiscovered gems alongside the radiopharmaceutical story of Telix Pharmaceuticals.
Telix Pharmaceuticals trades at a sizeable discount to both analyst targets and an intrinsic estimate, even after the recent bounce. Is that a pricing error, or a fair reflection of the risks around trials and capital needs?
Most Popular Narrative: 43% Undervalued
On the most followed view, Telix Pharmaceuticals is worth about A$24.51 a share compared with the last close at A$14.08. This puts the focus squarely on whether its pipeline and manufacturing build out can justify that gap.
Vertical integration in radiopharmaceutical manufacturing and last mile distribution through RLS, ARTMS, Iso Therapeutics and other TMS sites, including planned cyclotron deployment, which can reduce reliance on third parties and over time may support gross margins and supply reliability, both key inputs to sustainable earnings.
See why 31 investors see Telix Pharmaceuticals as 43% undervalued.
Result: Fair Value of A$24.51 (UNDERVALUED)
Still, the SEC subpoena over prostate cancer disclosures and pricing pressure in PSMA imaging could both chip away at the Telix Pharmaceuticals optimism story.
Find out about the key risks to this Telix Pharmaceuticals narrative.
Another View On Telix Pharmaceuticals' Valuation
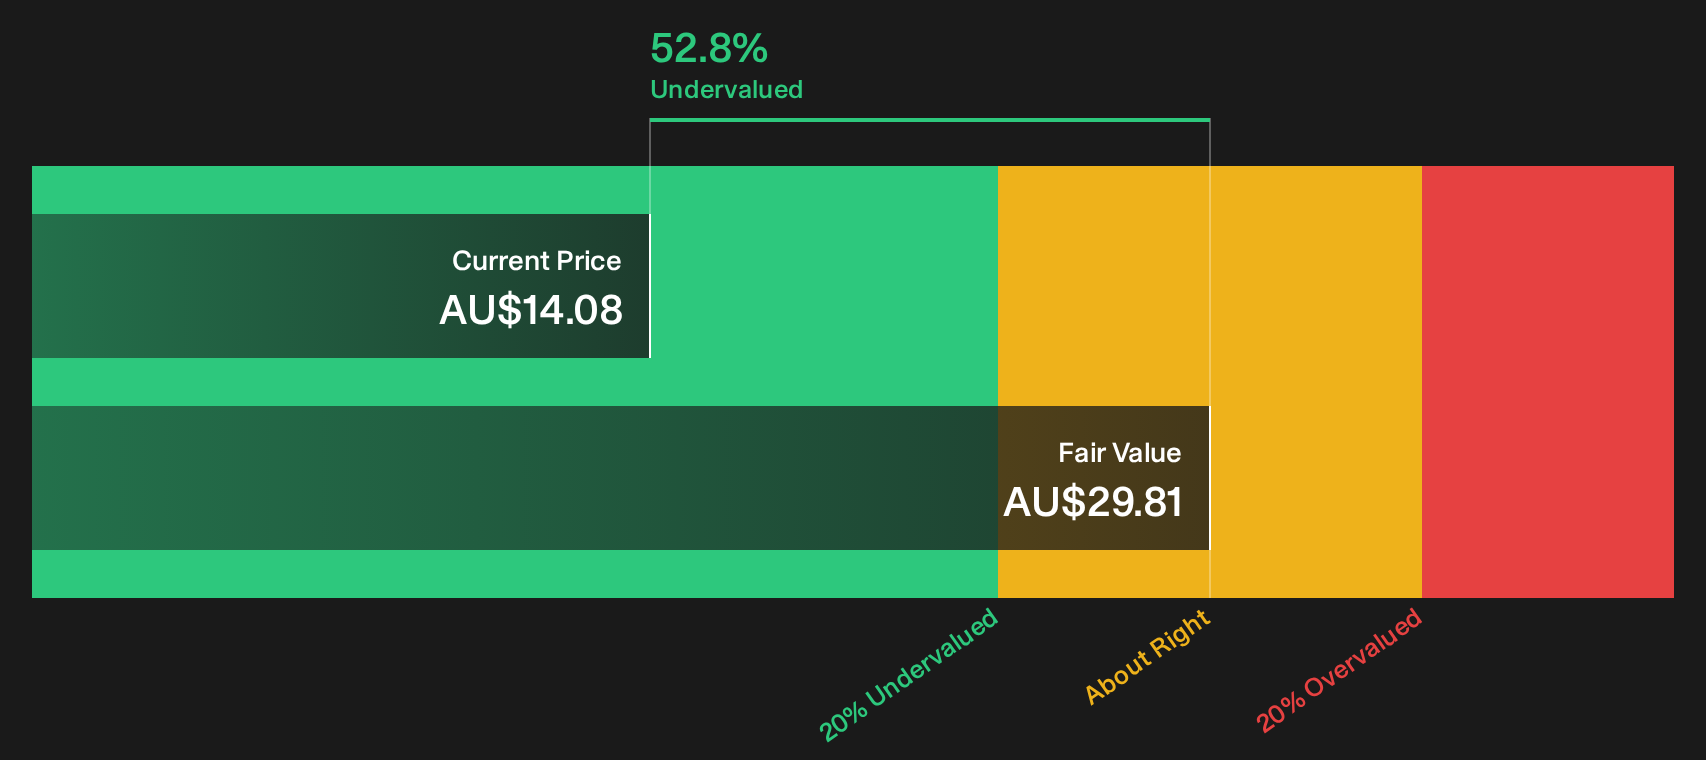
The discounted cash flow work presents Telix Pharmaceuticals in a different light. Our DCF model points to a fair value of about A$29.81 a share, which is above both the A$24.51 narrative fair value and the current A$14.08 price. If both models lean undervalued, where do you think the bigger error sits: in the forecasts or in the market price?
To unpack how this cash flow based view is built and to stress test the assumptions for yourself, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
Next Steps
If the mixed mood on Telix Pharmaceuticals has you on the fence, move quickly from headlines to hard numbers and test the thesis against your own risk tolerance and time horizon. Then pressure test both the red flags and upside potential through the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Telix Pharmaceuticals?
Do not stop at Telix Pharmaceuticals. Broader context can help sharpen every decision, and a few focused screens may quickly surface alternatives that better match your plan.
- Target resilient balance sheets and steadier fundamentals by reviewing companies in the list of solid balance sheet and fundamentals (12 results).
- Hunt for quality at a discount and pressure test your value thesis with the 5 high quality undervalued stocks.
- Prioritise defence over drama and concentrate on stability through the 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com