


IonQ (IONQ) shares are tumbling on Nov. 5 after senior Wedbush analyst Matt Bryson issued somewhat of a dovish note in favor of the quantum computing specialist. Bryson maintained his rating on IONQ this morning at “Outperform” but reduced his price target to $50 from $75. The new target nonetheless suggests potential upside of roughly 100% in the months ahead.
IonQ stock has been in a huge downtrend in 2026, currently trading more than 60% below its year-to-date high.
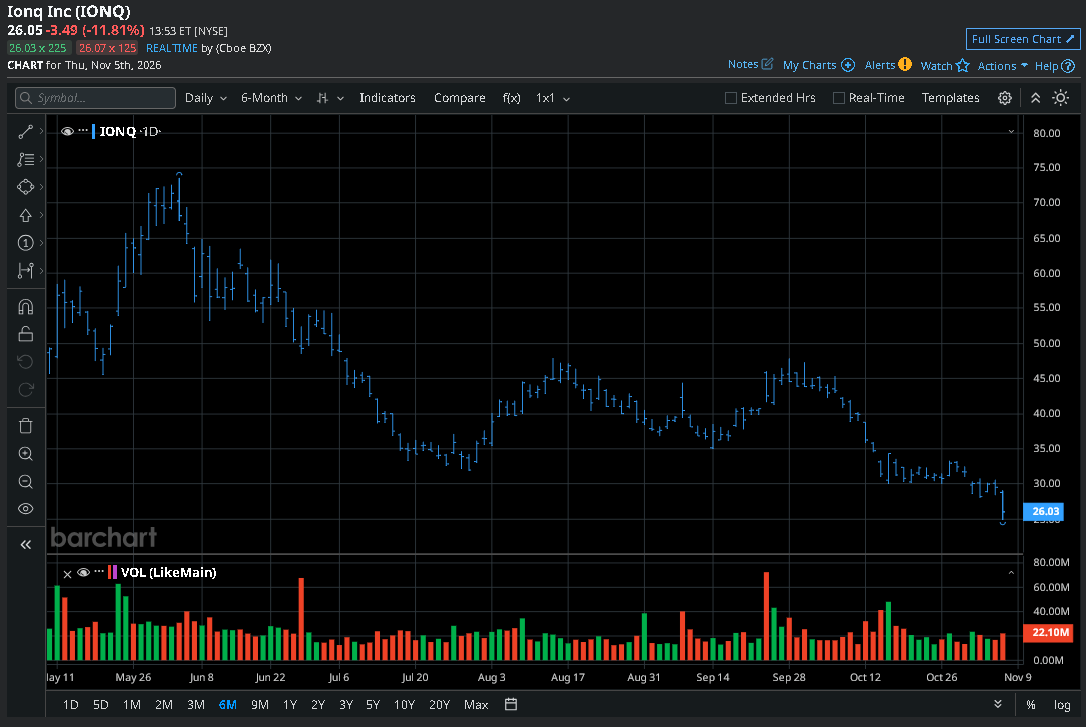
What Made Wedbush Cut Price Target on IonQ Stock
Bryson remains largely bullish on IONQ shares. In fact, he views the company as the “scale leader” within the quantum-tech space. The price adjustment only reflects lower growth assumptions sector-wide for the next two years, the analyst told clients in a research note today.
Moreover, IonQ priced a $2 billion equity offering in mid-October, triggering dilution concerns that he believes will continue to weigh on the quantum stock.
Investors should also note that the NYSE-listed firm has a history of losing more than 11% on average in December, a seasonal trend that makes it rather unattractive to own in the near term.
Why Is Wedbush Still Bullish on IONQ Shares?
On the plus side, Bryson said: “our QWC view that fault-tolerant timelines are pulling forward remains intact.” The Wedbush analyst also expects federal support to remain a major tailwind that could help IonQ stage a meaningful comeback in 2027. Meanwhile, the latest AI models are improving error detection and correction as well.
Bryson's research note arrives only hours before IONQ is set to report its fiscal Q3 earnings. Consensus is for the quantum-tech specialist to report a loss of $0.79 in earnings per share (EPS) for its third financial quarter, which would represent a 78% improvement on a year-over-year basis.
What Analysts Expect From IonQ Moving Forward
Interestingly, Wedbush is now among the more conservative Wall Street firms on IONQ shares.
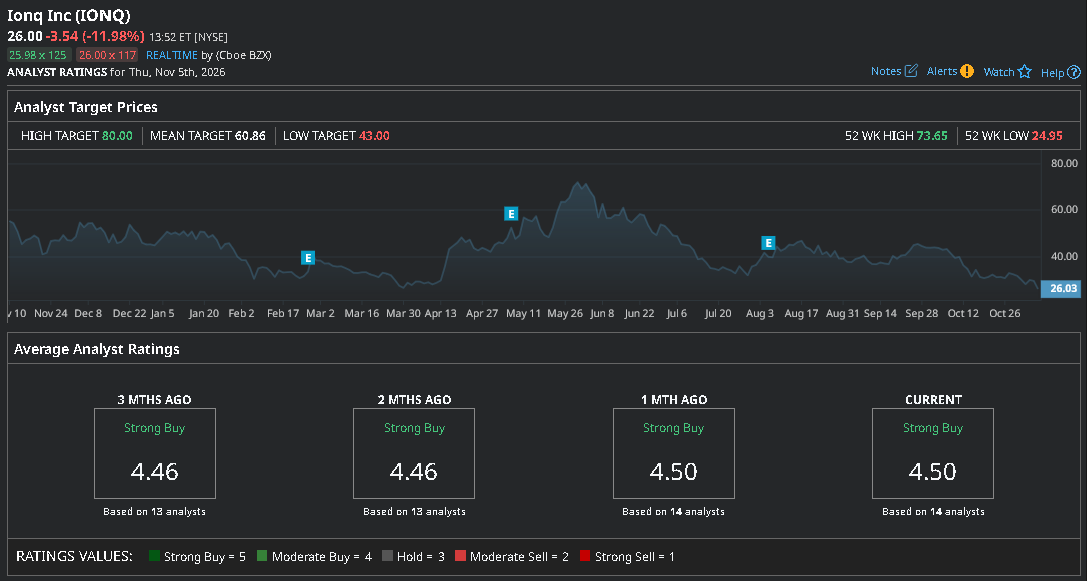
According to Barchart, the consensus rating on the quantum-computing firm remains at “Strong Buy,” with the mean price target of about $61 indicating IonQ could more than double from current levels over the next 12 months.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.