


EMCOR Group has seen its share price surge over the past few years, yet the past few months have been far more volatile. The key issue now is how well its current valuation lines up with the earnings behind the business. With the stock pulling back recently after a long run, the question for you is whether the market price still makes sense when viewed through its profit stream.
- Over the past 5 years the stock has climbed about 397.1%, which puts a lot of weight on whether the underlying earnings profile can support that kind of re-rating.
- Recent updates on revenue growth, profitability and remaining performance obligations suggest investors are factoring in meaningful earnings power, which can influence how much you are willing to pay for each dollar of profit.
- There is a second opinion on EMCOR Group worth weighing. See what analysts think EMCOR Group's shares could be worth.
The issue now is whether EMCOR Group's current share price is justified by the level and quality of its earnings today.
If you want other ideas with a similar earnings focus, a targeted screener built around 35 high quality undervalued stocks can be a useful second step in your research.
Does EMCOR Group Look Undervalued on Earnings?
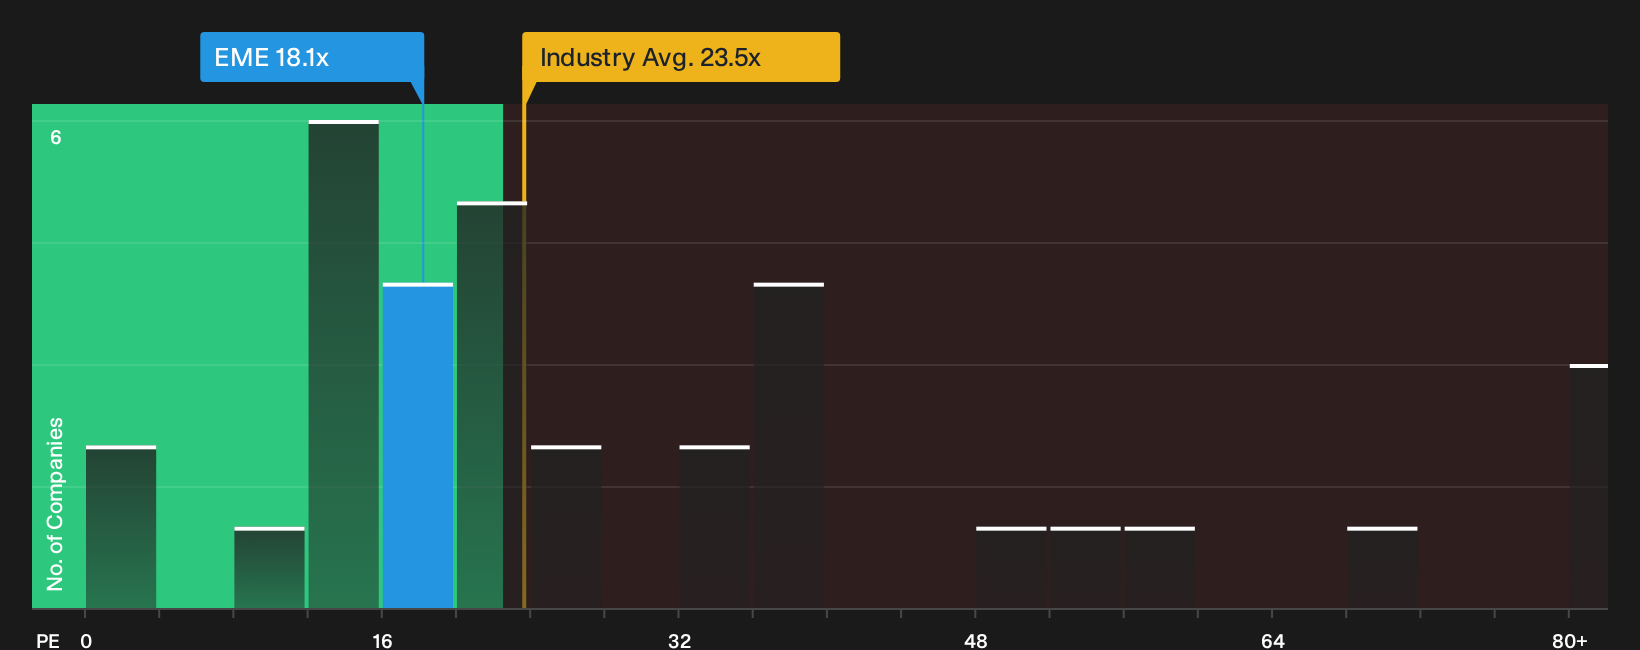
The P/E ratio suits EMCOR Group because investors are clearly focused on its earnings profile. Right now the stock trades on about 18.1x earnings, which is meaningfully lower than the Construction industry average of roughly 23.5x and well below the peer group near 29.6x. A tailored fair P/E based on EMCOR Group's own growth outlook, margins, scale and risk profile sits higher than where the shares trade, so the current multiple screens as undervalued relative to that benchmark.
Because management recently raised its 2026 earnings guidance after reported results, the gap between the P/E and both industry levels and the more customised fair multiple suggests the market is still applying a discount to EMCOR Group despite the updated outlook. For you as an investor, the key question is whether that discount fairly reflects execution risk and future project delivery or whether it points to an opportunity worth further work. Explore the numbers behind EMCOR Group's P/E valuation.
The EMCOR Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for EMCOR Group pick up where the P/E puzzle leaves off and describe what kind of future on growth, margins and earnings would need to occur for the stock to be worth significantly more or meaningfully less than it is today. All of this is housed on the platform's Community page. Rather than a single multiple or model output, each narrative lays out the set of assumptions behind its fair value view so you can track those expectations against EMCOR Group's actual results as they arrive.
One of the top community narratives on EMCOR Group: 35% undervalued
"The main thing that has to go right is that EMCOR Group converts its record backlog and growing mix of complex GMP and cost-plus projects…"
Discover why this Narrative puts EMCOR Group at 35% undervalued.
One more angle on EMCOR Group that could change the story
Valuation only tells you what the market is willing to pay, not who is steering EMCOR Group or how their incentives line up with your interests. See who runs EMCOR Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com