


First National of Nebraska (FINN) just paired a fresh earnings update with a confirmed cash return to shareholders, as third quarter results and a new quarterly dividend were reported on October 27, 2026.
Against that backdrop, First National of Nebraska’s share price has climbed 23.06% year to date to US$19,075, while the 1 year total shareholder return of 38.79% and 3 year total shareholder return of 66.11% point to momentum that has been building rather than fading.
Scan beyond First National of Nebraska and size up other banks with strong momentum and fundamentals using our hand picked list of solid balance sheet and fundamentals (24 results)
After a 23.06% climb this year and a US$40 per share dividend on the way, First National of Nebraska now forces a choice. Do you commit at this price, or wait and hope for a cheaper entry before the next move?
Preferred P/E of 9.7x: Is it justified for First National of Nebraska?
On recent figures, First National of Nebraska trades on a P/E of 9.7x, with the last close at $19,075, while many US banks and the broader market sit on higher earnings multiples.
The P/E ratio compares the current share price to earnings per share, so it gives you a quick way to see how much investors are paying for each dollar of profit. For a bank like First National of Nebraska, that lens matters because earnings quality, profitability and balance sheet strength tend to drive long term confidence more than headline revenue growth.
FINN is flagged as having high quality earnings, with net income of $530.353m from revenue of $2,055.96m and profit margins currently at 25.8% compared with 16.6% last year. With that backdrop, a 9.7x P/E that sits below both the US market on 18x and the peer average on 11.8x suggests the market is pricing these profits more cautiously than the sector. This is occurring even as earnings grew 86.2% over the past year and outpaced the wider US Banks industry figure of 22.7%.
Relative to the US Banks industry average P/E of 11.3x and the peer average of 11.8x, the 9.7x multiple represents a clear discount. That is a meaningful gap. It points to investors valuing First National of Nebraska’s earnings more conservatively than both direct peers and the overall market despite the recent profit expansion.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 9.7x (UNDERVALUED)
Still, the narrative around First National of Nebraska can shift quickly if earnings quality weakens or credit conditions in core lending markets tighten.
Find out about the key risks to this First National of Nebraska narrative.
Another View: DCF Paints a Very Different Picture for First National of Nebraska
The earnings multiple suggests First National of Nebraska looks inexpensive, yet the SWS DCF model tells a tougher story. On that framework, FINN at $19,075 screens as overvalued against an estimated future cash flow value of about $9,010.53, which implies a wide gap between price and cash generation.
That kind of disconnect raises a practical question for you as an investor. Do you trust the current P/E and recent profit strength, or do you give more weight to a cash flow model that points to a very different outcome?
Look into how the SWS DCF model arrives at its fair value.
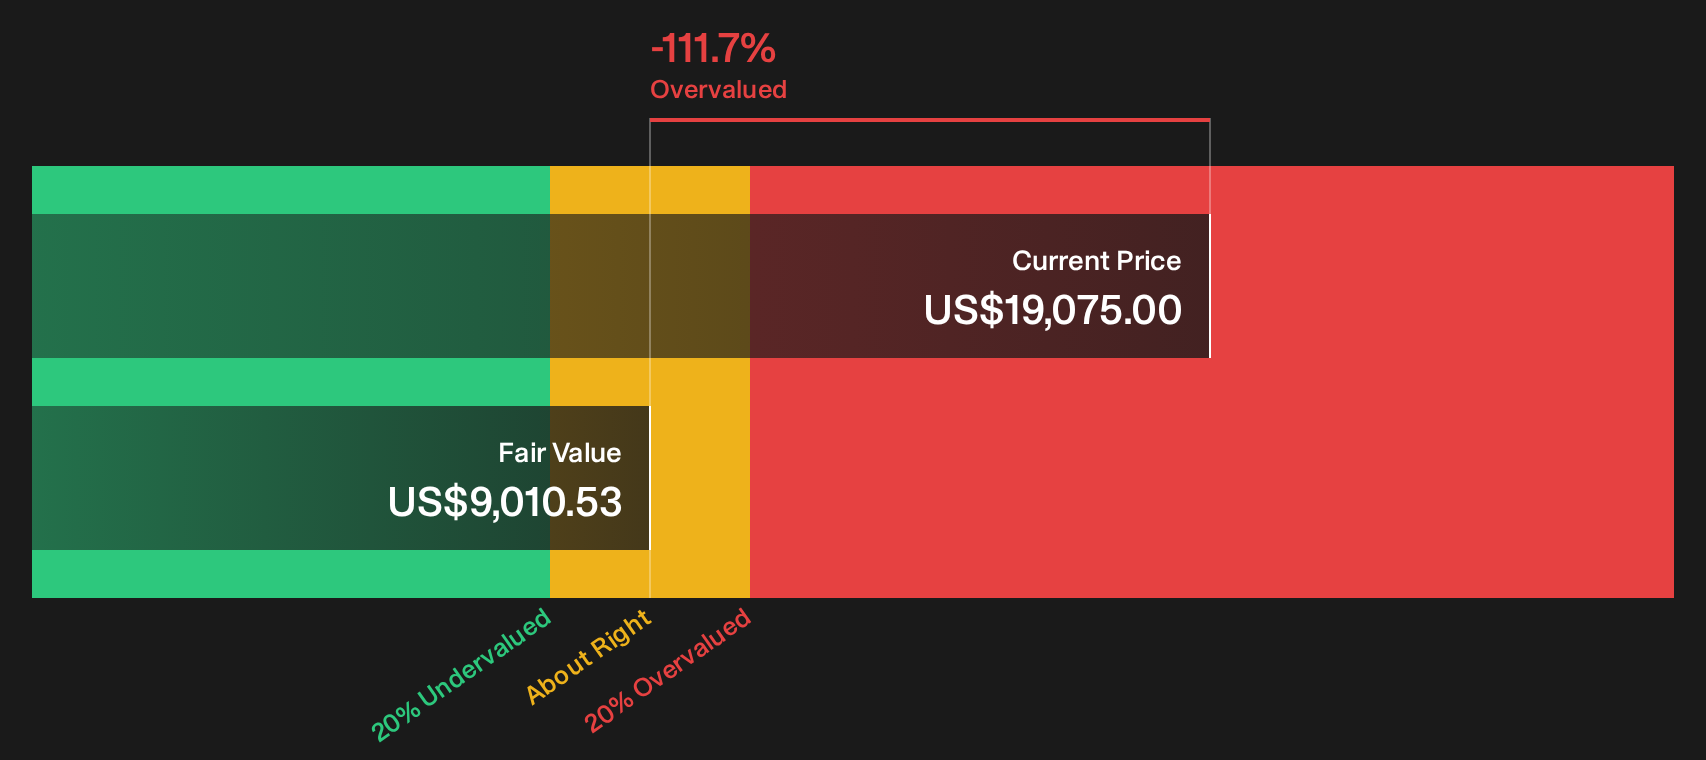
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First National of Nebraska for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on First National of Nebraska is clearly mixed, with strong profits on one side and valuation and risk questions on the other. Consider reviewing the underlying data for yourself and weighing both the upside and the concerns by starting with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond First National of Nebraska?
Do not stop with one bank. Give yourself a broader watchlist by lining up fresh ideas from the Simply Wall St screener before the next wave of results lands.
- Target potential upside in mispriced opportunities by scanning our hand picked 35 high quality undervalued stocks that combine solid fundamentals with compressed valuations.
- Build a steadier income stream by focusing on companies in the 5 dividend fortresses that pair higher yields with robust underlying businesses.
- Limit unpleasant surprises by concentrating on resilient businesses in the 31 resilient stocks with low risk scores that score well on financial strength and risk checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com