


Gartner (IT) sparked fresh debate after third quarter 2026 results topped expectations on earnings, cash flow, and contract value growth. Management lifted full year guidance but reported a modest year-on-year revenue decline.
Despite the upbeat third quarter guidance, Gartner’s latest share price of $198.07 comes after a sharp 1 day decline of 4.4% and a 7 day slide of 12%, even though the 30 day share price return is up 7.1% and the 90 day move is positive at 6.7%.
That short term pullback sits against a tougher backdrop, with the year to date share price return down 16.4% and the 1 year total shareholder return down 12.5%, while the 3 year and 5 year total shareholder returns, down 50.7% and 39.9% respectively, indicate that investors are still reassessing Gartner’s growth profile and risk after a long stretch of weaker performance.
Scan beyond Gartner and weigh it against a hand picked 39 profitable AI stocks that aren't just burning cash.
After a sharp reset in Gartner’s share price, despite stronger earnings and higher guidance, you are left weighing whether this volatility has finally tilted the risk reward balance back toward buyers or still signals caution on valuation.
Most Popular Narrative: 2% Overvalued
Gartner’s most followed narrative pins fair value at about $193.77 using a 10% discount rate, which sits just below the recent close around $198.07 and keeps the focus on how much of the AI and contract value story is already embedded in the current price.
The current valuation and management’s commitment to aggressive buybacks and free cash flow focus indicate that Gartner’s current share price already reflects expectations for resilient margins, high cash conversion and continued EPS growth.
Strong free cash flow, which is guided to at or above US$1.185b for 2026 with conversion of 136% of GAAP net income, together with ongoing share repurchases that reduced the share count by about 14% year on year, is expected to continue supporting EPS and return on capital.
See why 13 investors see Gartner as 2% overvalued.
Result: Fair Value of $193.77 (OVERVALUED)
Still, Gartner’s narrative could be knocked off course if tight client budgets keep contract value growth muted or if legal and governance investigations drive higher costs.
Find out about the key risks to this Gartner narrative.
Another View: How Gartner Looks On Earnings Multiples
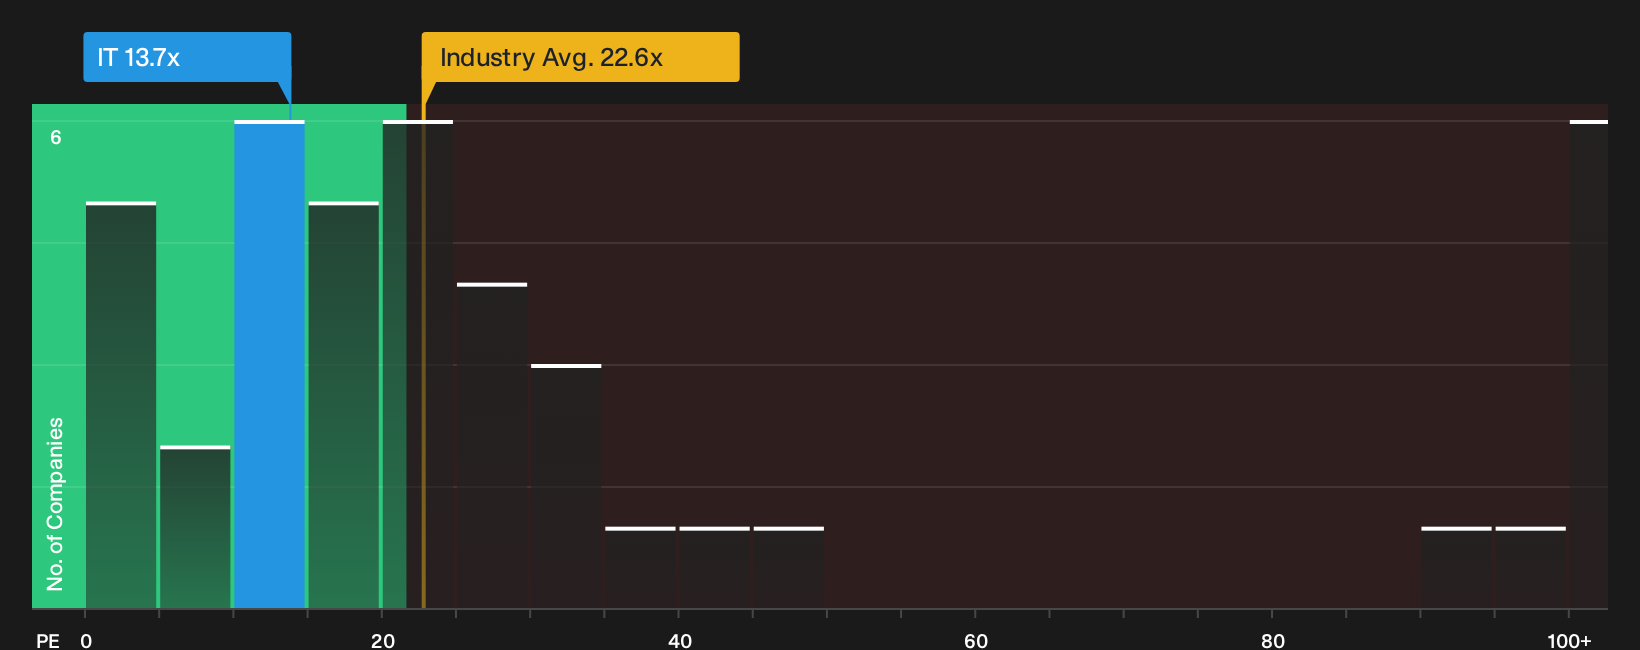
The fair value estimate of $193.77 says Gartner is about 2% overvalued, yet the current P/E of 13.7x tells a different story. The broader US IT industry sits on 22.6x, and a fair ratio of 27.9x suggests the market could move closer to that level over time. For investors, that gap points to either a margin of safety or a warning that expectations for Gartner’s growth and balance sheet risk still need more scrutiny. Which lens do you trust more right now: the narrative fair value or the earnings multiple?
To see how those earnings multiples stack up in detail and what they imply for risk, valuation and peers, take a closer look at our breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Gartner’s valuation and growth story can feel messy, so move quickly, stress test the numbers yourself, and weigh both the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Gartner?
Gartner’s story is only one piece of your portfolio puzzle, so broaden your opportunity set and pressure test where your next dollar really works hardest.
- Target resilient compounding potential by scanning companies that combine strong fundamentals with clean balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities where quality and valuation meet by running your own filter through the 35 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses with higher yields and robust histories through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com