


Vijaya Diagnostic Centre Limited (NSE:VIJAYA) just released its second-quarter report and things are looking bullish. It was overall a positive result, with revenues beating expectations by 4.2% to hit ₹2.6b. Vijaya Diagnostic Centre reported statutory earnings per share (EPS) ₹5.76, which was a notable 10% above what the analysts had forecast. The analysts typically update their forecasts at each earnings report, and we can judge from their estimates whether their view of the company has changed or if there are any new concerns to be aware of. So we collected the latest post-earnings statutory consensus estimates to see what could be in store for next year.
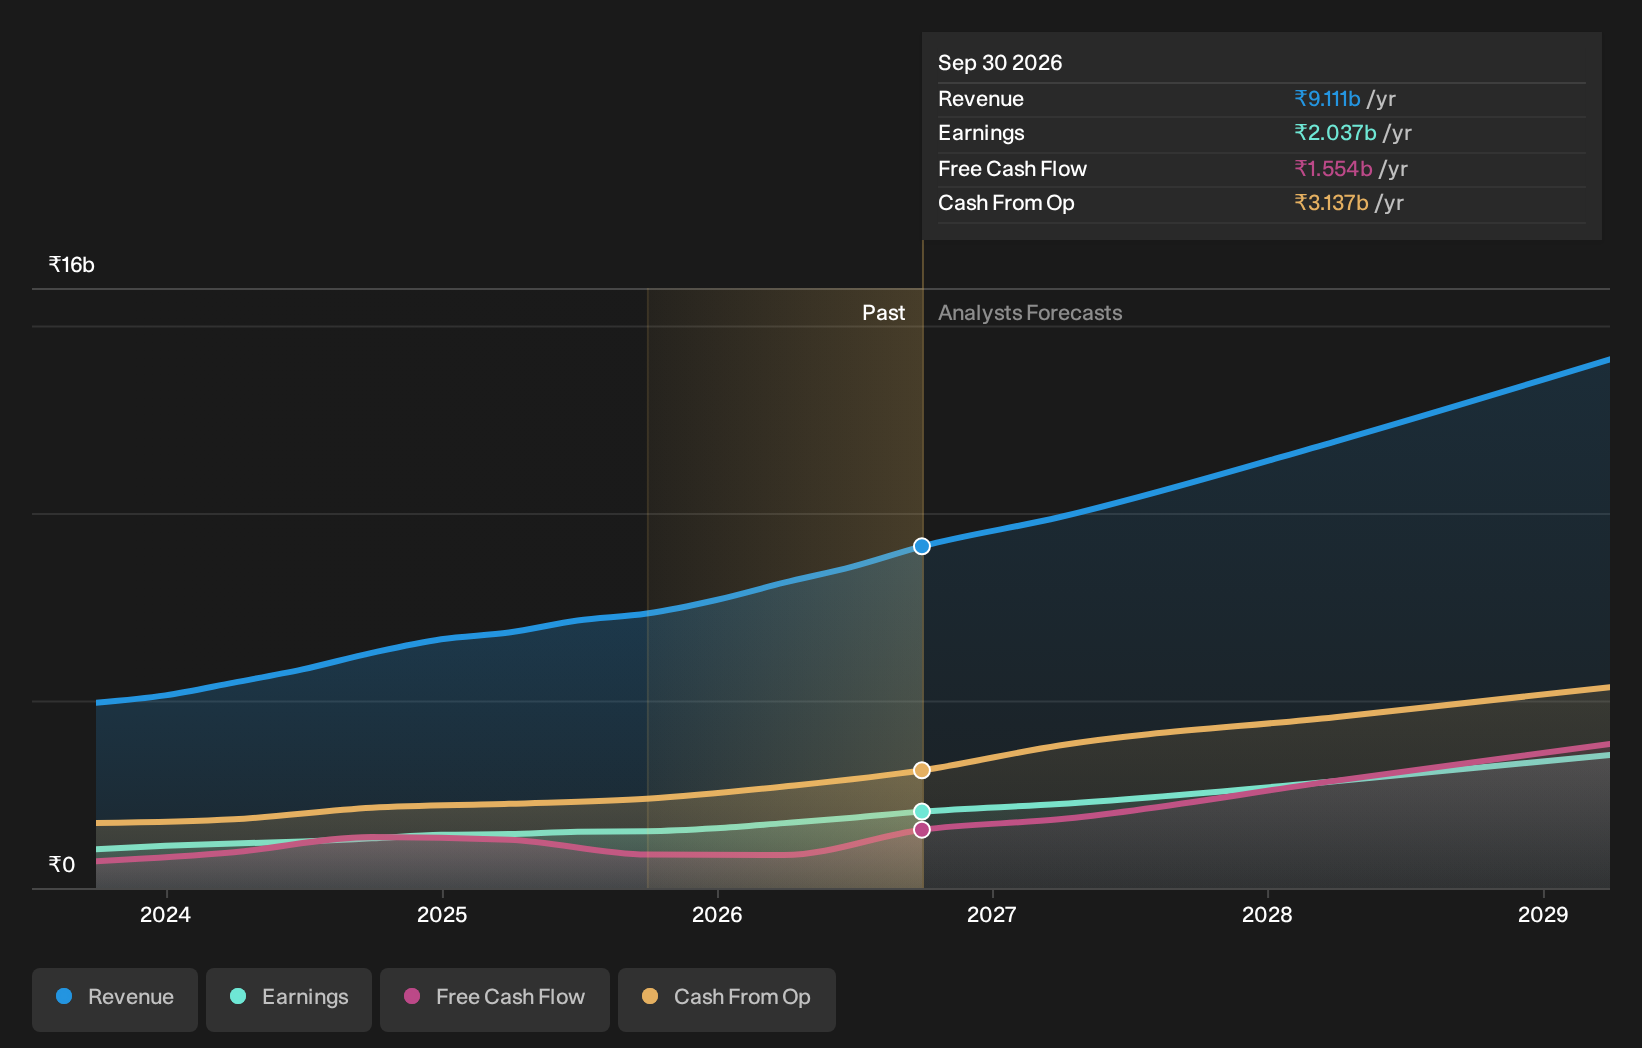
Taking into account the latest results, the most recent consensus for Vijaya Diagnostic Centre from nine analysts is for revenues of ₹9.89b in 2027. If met, it would imply a meaningful 8.5% increase on its revenue over the past 12 months. Per-share earnings are expected to rise 10.0% to ₹21.75. Yet prior to the latest earnings, the analysts had been anticipated revenues of ₹9.89b and earnings per share (EPS) of ₹21.75 in 2027. The consensus analysts don't seem to have seen anything in these results that would have changed their view on the business, given there's been no major change to their estimates.
View our latest analysis for Vijaya Diagnostic Centre
There were no changes to revenue or earnings estimates or the price target of ₹1,555, suggesting that the company has met expectations in its recent result. The consensus price target is just an average of individual analyst targets, so - it could be handy to see how wide the range of underlying estimates is. Currently, the most bullish analyst values Vijaya Diagnostic Centre at ₹1,700 per share, while the most bearish prices it at ₹1,400. Even so, with a relatively close grouping of estimates, it looks like the analysts are quite confident in their valuations, suggesting Vijaya Diagnostic Centre is an easy business to forecast or the the analysts are all using similar assumptions.
These estimates are interesting, but it can be useful to paint some more broad strokes when seeing how forecasts compare, both to the Vijaya Diagnostic Centre's past performance and to peers in the same industry. The period to the end of 2027 brings more of the same, according to the analysts, with revenue forecast to display 18% growth on an annualised basis. That is in line with its 16% annual growth over the past five years. Juxtapose this against our data, which suggests that other companies (with analyst coverage) in the industry are forecast to see their revenues grow 18% per year. It's clear that while Vijaya Diagnostic Centre's revenue growth is expected to continue on its current trajectory, it's only expected to grow in line with the industry itself.
The Bottom Line
The most important thing to take away is that there's been no major change in sentiment, with the analysts reconfirming that the business is performing in line with their previous earnings per share estimates. Happily, there were no real changes to revenue forecasts, with the business still expected to grow in line with the overall industry. The consensus price target held steady at ₹1,555, with the latest estimates not enough to have an impact on their price targets.
Following on from that line of thought, we think that the long-term prospects of the business are much more relevant than next year's earnings. At Simply Wall St, we have a full range of analyst estimates for Vijaya Diagnostic Centre going out to 2029, and you can see them free on our platform here..
You can also see our analysis of Vijaya Diagnostic Centre's Board and CEO remuneration and experience, and whether company insiders have been buying stock.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.