


Dividend announcement puts Target Healthcare REIT in focus
Target Healthcare REIT (LSE:THRL) has declared a first interim cash dividend of 1.553 pence per share for the quarter to 30 September 2026, catching the eye of income focused investors.
The latest dividend news lands on a stock that already has momentum. Target Healthcare REIT’s share price is at £1.208 with a year-to-date share price return of 23.39%, while the 1-year total shareholder return of 34.99% and 3-year total shareholder return of 80.40% point to a longer track record of investor gains that recent quarterly moves appear to be extending rather than reversing.
Look beyond Target Healthcare REIT and explore other income focused opportunities using our hand picked list of 6 dividend fortresses
After a 23.39% year-to-date jump and a 3-year total return above 80%, is most of Target Healthcare REIT’s upside already in the rear-view mirror, or does the current valuation still leave room ahead?
Most Popular Narrative: 0% Overvalued
Target Healthcare REIT’s most followed valuation story now anchors fair value at £1.20, almost level with the latest £1.208 close, which puts far more weight on the quality and durability of its care home income than on short term share price moves.
Recycling capital from disposals at premiums to book into a pipeline of higher yielding, prime care homes is expected to lift portfolio net initial yields, enhancing EPRA earnings and supporting further growth in fully covered, progressive dividends.
See why 8 investors see Target Healthcare REIT as 0% overvalued.
Result: Fair Value of £1.20 (ABOUT RIGHT)
Still, the Target Healthcare REIT story can change quickly if tenant finances weaken or if regulators curb inflation linked rent reviews, both of which could pressure rental income and dividend cover.
Find out about the key risks to this Target Healthcare REIT narrative.
Another view on Target Healthcare REIT’s valuation
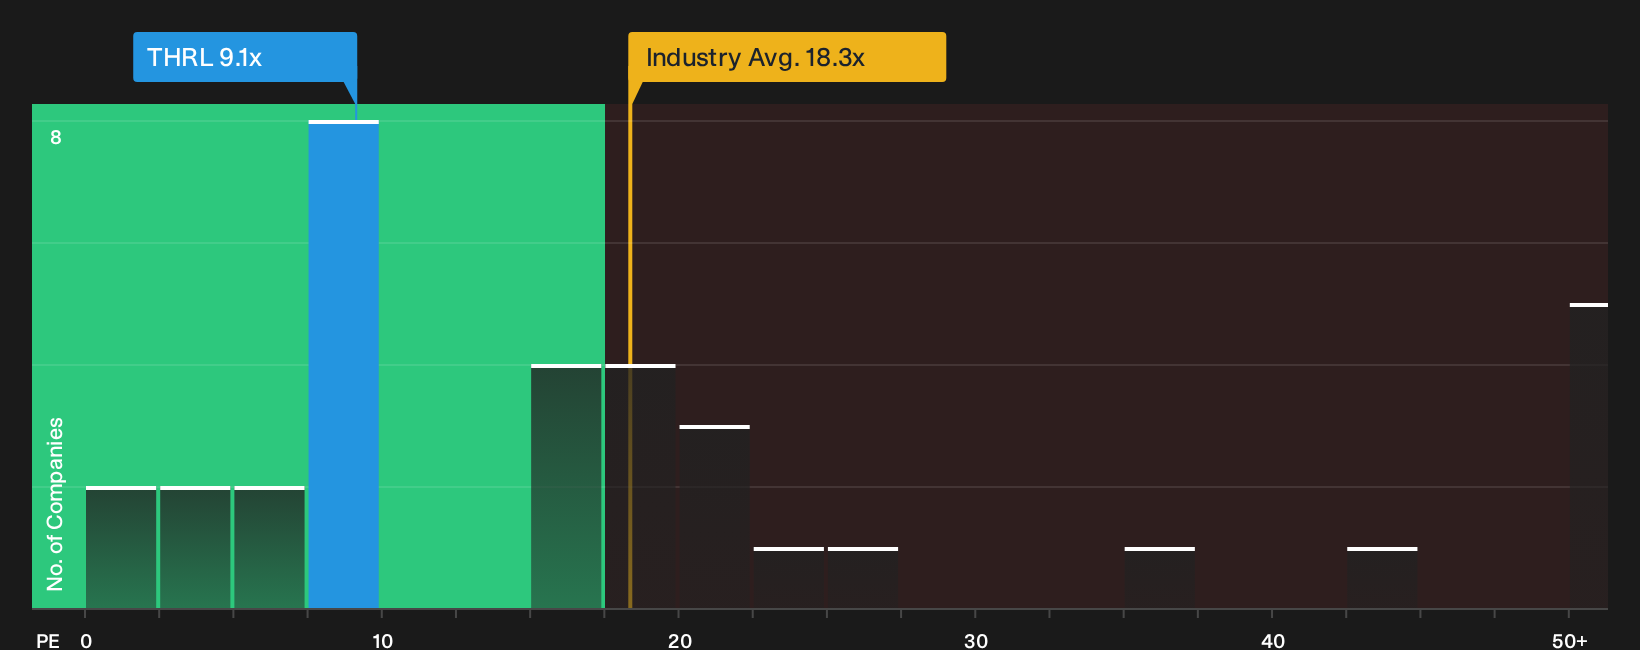
The analyst fair value of about £1.20 paints Target Healthcare REIT as roughly fully priced. The P/E ratio tells a different story. At 9.1x earnings against a fair ratio of 11.5x, and peer averages of 19.6x in the UK and 18.3x globally, the shares screen as cheaper than both fair value and rivals. The gap hints at either a margin of safety or risk that the market is pricing in, which you need to judge for yourself.
If you want to see how this earnings based view stacks up against the full valuation breakdown, including the fair ratio, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how Target Healthcare REIT’s valuation compares to the wider sector, review the
Next Steps
If this combination of upbeat returns and valuation debate leaves you unsure, move quickly from reading to checking the data for yourself. Balance the potential income story and the risks on your own terms by reviewing the 4 key rewards and 3 important warning signs
Looking for more Target Healthcare REIT sized ideas?
Do not stop with one promising opportunity. Use the data to broaden your watchlist so you keep finding fresh prospects before the crowd catches on.
- Spot potential bargains early by scanning companies that currently screen as 15 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (9 results) so you focus on businesses with financial strength behind their stories.
- Hunt for future leaders by checking a curated set of 5 high quality undiscovered gems before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com