


Matson (MATX) just reported a strong third quarter, with higher sales, revenue and earnings per share. The company then followed this performance with upgraded fourth quarter guidance and continued buybacks and dividends.
Matson’s strong third quarter has come after a powerful run in the shares, with the stock delivering a 72.88% year to date share price return and a 99.77% total shareholder return over the past 12 months, even though the 7 day share price return declined 5.78% and the 30 day share price return fell 4.85%. The 3 year total shareholder return of 146.13% hints that recent earnings strength is being viewed as part of a longer trend rather than a one quarter surprise.
Scan for other shipping and logistics stocks showing similar earnings momentum and capital return stories using our curated 42 high quality undervalued stocks.
The business looks powerful, especially after Matson’s recent surge and richer guidance. The real tension now is simple: Are you paying a fair price for that strength or stretching for it at today’s valuation?
Most Popular Narrative: 23% Undervalued
On the most followed view of Matson, the $276.75 fair value estimate sits well above the last close of $213.87. This frames recent quarterly strength as only part of the story rather than its peak.
The current narrative that Matson is undervalued holds that the share price does not fully reflect the raised 2026 earnings outlook, the growth in Southeast Asia volumes, and the scale of ongoing dividends and buybacks.
See why 12 investors see Matson as 23% undervalued.
Result: Fair Value of $276.75 (UNDERVALUED)
Still, the Matson story depends heavily on China and Southeast Asia volumes holding up, and on that roughly US$1b vessel program not squeezing future cash flexibility.
Find out about the key risks to this Matson narrative.
Another View: Matson Through The P/E Lens
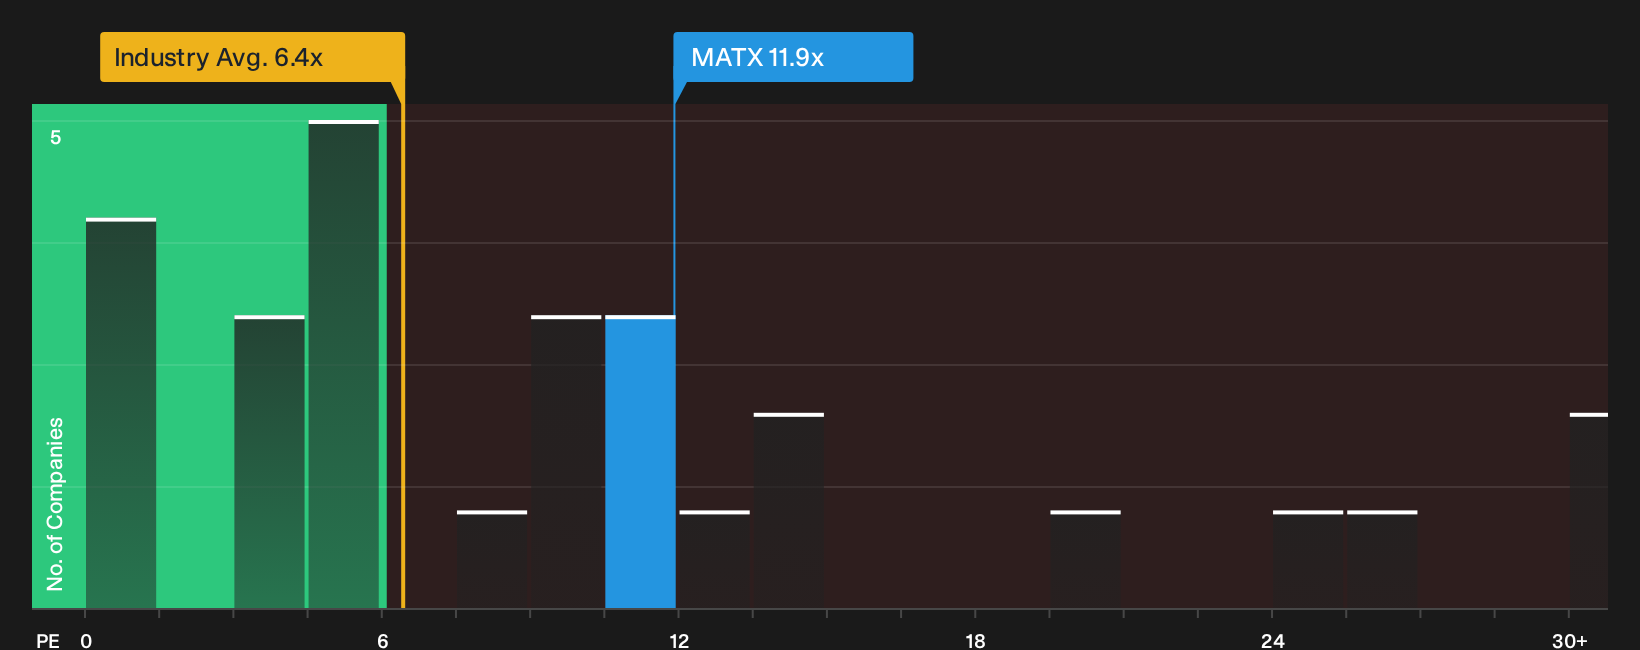
That $276.75 fair value implies Matson has room above the current $213.87 price, yet the earnings multiple paints a more cautious picture. The stock trades on a P/E of 11.9x, which is richer than the US Shipping industry at 6.4x, but cheaper than peer averages at 14.1x and below a fair ratio of 13.1x that the market could eventually lean toward. This mix of premium to the sector, discount to peers, and gap to the fair ratio raises a simple question: How much valuation risk are you really comfortable carrying for a business whose future earnings path is not spotless?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions on Matson are mixed so far. If this earnings story has you interested, consider reviewing the data yourself promptly and carefully weighing 3 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Matson?
If Matson has sharpened your focus on quality opportunities, do not stop here. Use these filters to pressure test fresh ideas before the crowd catches on.
- Target resilient balance sheets and steady fundamentals by running companies through our curated list of solid balance sheet and fundamentals (25 results).
- Spot potential mispricings early by scanning for quality businesses trading below their implied worth with the 42 high quality undervalued stocks.
- Lock onto under-the-radar opportunities before they attract wider attention using the focused 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com