


- Pfizer (NYSE:PFE) CEO used a recent investor appearance to set out a plan for a renewed push into obesity treatments.
- Management highlighted the historic commercial success of Viagra as a template for how Pfizer could bring future obesity drugs to market.
- The CEO said the firm intends to lean on its existing drug development playbook when deciding future R&D priorities in obesity care.
- Pfizer's effort to reuse its Viagra-era commercialization playbook for obesity drugs is only one part of the broader story here. We have also flagged 4 warning signs for Pfizer.
For readers interested in more ways to play the broader healthcare and data-heavy drug research trend, consider exploring 53 AI infrastructure stocks.
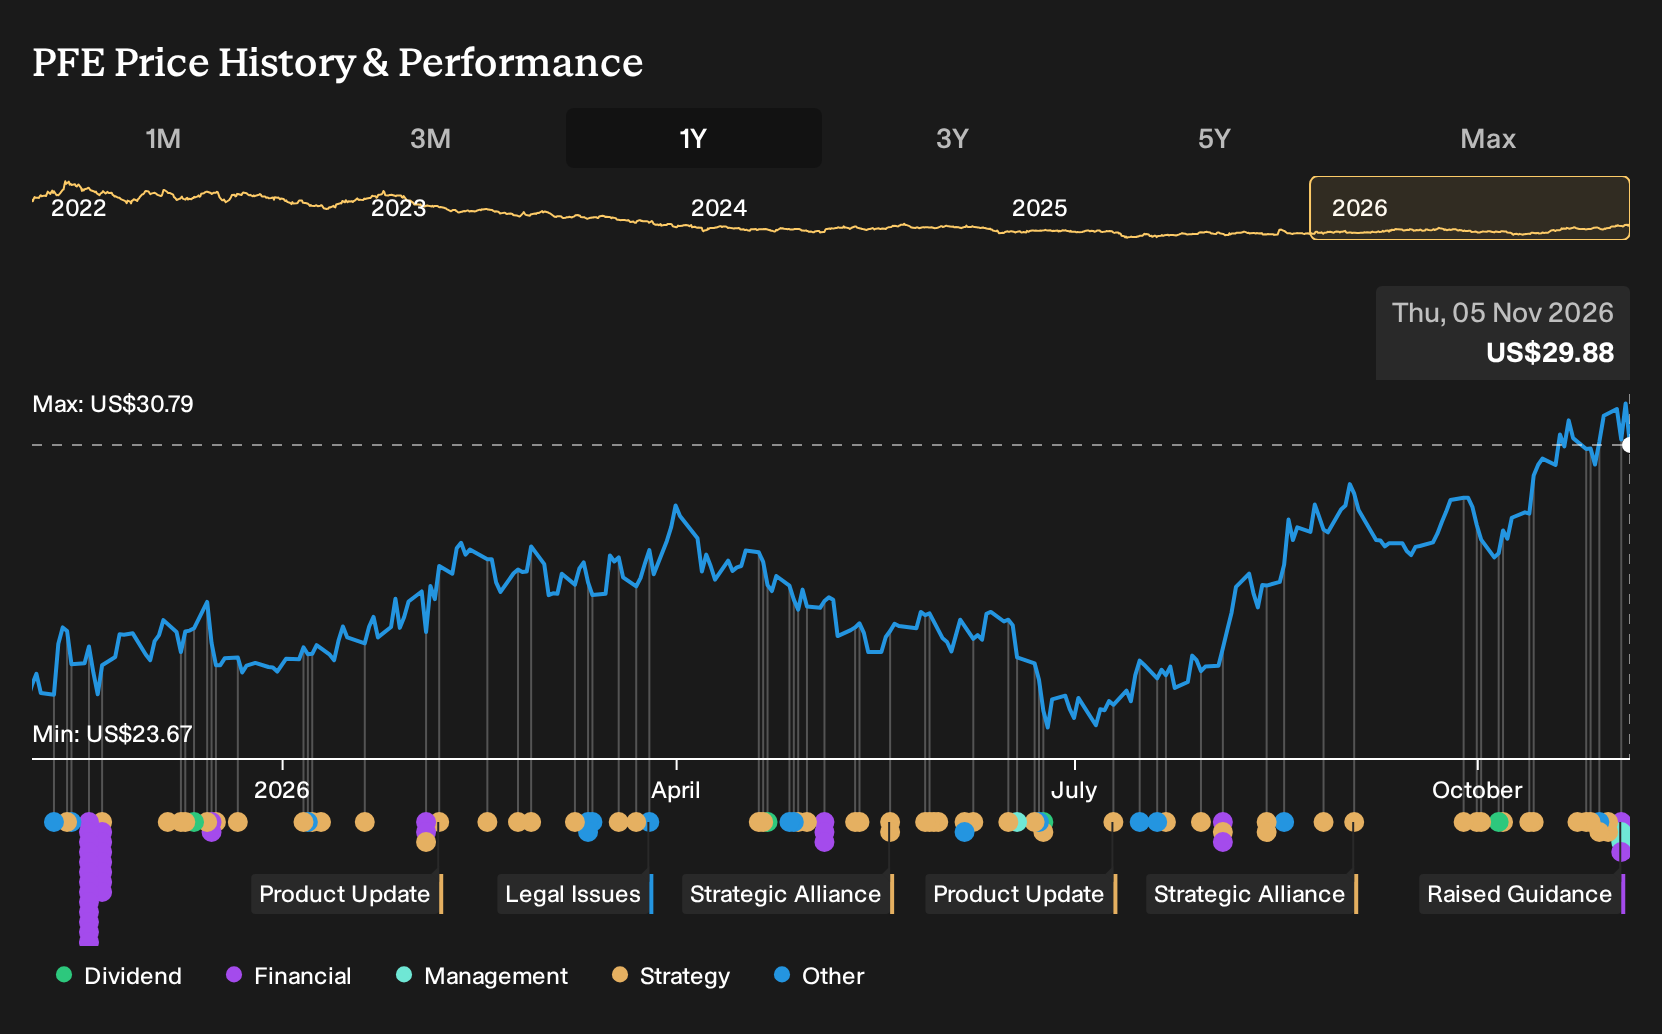
Pfizer is a large US-based pharmaceuticals group with a US$175.5b market cap that discovers, develops, manufactures, and sells biopharmaceutical products across the United States and international markets. This provides it with an existing global footprint it can apply to any future obesity therapies.
Pfizer’s obesity push leans on the “Viagra playbook” while putting its cost saving story to work
For Pfizer investors, the CEO tying the obesity push to the old Viagra commercialization model speaks directly to two pillars of the existing Narrative. It supports the catalyst that calls for obesity drugs like berobenatide to become a meaningful non COVID revenue pillar, and it leans on the same large scale productivity and cost saving program that is meant to free up cash for this R&D focus. The raised 2026 revenue guidance, together with Cecile Guegan now confirmed as permanent CFO, also speaks to leadership continuity around that US$9.7b savings plan and how aggressively the group funds obesity alongside oncology.
See how these catalysts shape Pfizer's path to a $28.88 fair value.
From here, one practical checkpoint is whether management starts giving more precise timelines and spending splits for obesity in its guidance, especially around the targeted 2028 first approval date for berobenatide and how much of the US$9.7b efficiency plan is being redeployed into that franchise versus other pipelines.
Add Pfizer to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com