


Asian markets have just been hit by a sharp tech selloff, as worries about slower AI data centre spending reset expectations for growth stocks. That kind of shakeout often leaves high quality Canadian growth stories trading alongside weaker businesses. Insiders with big personal stakes tend to stay focused through these swings. This article highlights three fast growing Canadian companies where management has kept meaningful skin in the game.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily aligned with outside shareholders. However, if you want the pick of this theme, these 9 high growth high conviction stocks are the best of the best.
Bombardier (TSX:BBD.B)
Overview: Bombardier is a Canadian aerospace business that designs and builds Learjet, Challenger, and Global business jets, plus related services.
Market Cap: CA$33.97 billion
Bombardier fits this screener because its business jet franchise and growing service network sit behind management’s growth and cash flow outlook.
"Bombardier’s shift toward a more cash generative model, including guidance for more than US$1b of free cash flow in 2026 and a net leverage ratio of 1.6x with no debt maturities before November 2030, gives the company room to keep retiring debt and redirecting excess cash into earnings accretive capital allocation that can support net income."
What happens to that picture if a single pressure point on future margins and demand does not develop in Bombardier’s favour?
If that risk path interests you, read the full narrative for Bombardier to see how Bombardier’s cash engine, leverage targets and insider alignment could reshape the story.
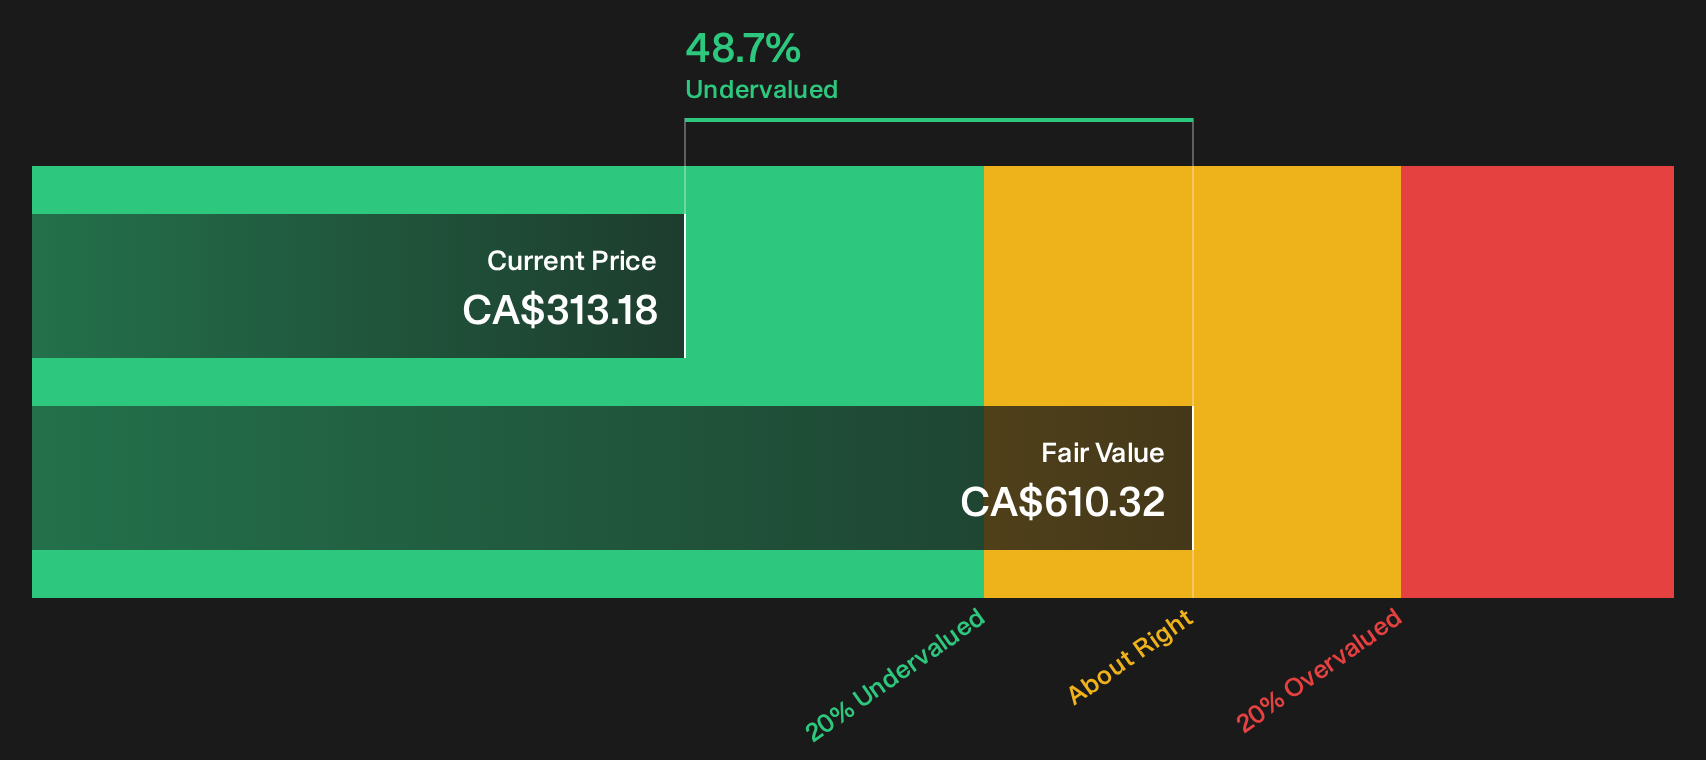
Ivanhoe Mines (TSX:IVN)
Overview: Ivanhoe Mines is a Canadian miner developing and operating high grade copper, zinc, and PGM projects across Africa, with Kamoa-Kakula driving its fast growth profile.
Operations: Ivanhoe Mines currently reports around $700 million from Kipushi Properties, with additional segment adjustments and sales routed through hubs in Hong Kong, Singapore, and Switzerland.
Market Cap: CA$12.05 billion
Ivanhoe Mines appeals to this fast growth, high insider ownership theme because Kamoa-Kakula anchors a large scale copper story that management continues to back with their own capital and time.
"Kamoa-Kakula: 388,838 to 388,841 t copper in concentrate (100% basis; Ivanhoe attributable ~154 kt) despite Q2 seismic/flooding hiccup at Kakula East (temporary 6-month disruption in 30+ year LOM). Political risk (DRC/SA) noted but manageable."
What matters now is how one pressure on future ramp pace and project economics ultimately shapes that promising long term growth path.
That single pressure point could be the accelerator or the brake, and the full narrative for Ivanhoe Mines maps out how Ivanhoe Mines balances ramp risks with long term copper upside.

Colliers International Group (TSX:CIGI)
Overview: Colliers International Group helps institutional and corporate clients buy, sell, finance, manage, and engineer commercial real estate and infrastructure worldwide.
Market Cap: CA$7.0 billion
Colliers International Group fits the fast growing, high insider ownership theme through its capital markets and investment management arm, where fee income rises as more clients entrust assets and long term mandates to the platform.
"The growing interest from institutional and private wealth channels in alternative asset classes such as data centers, student housing, infrastructure, and credit solutions is driving segment diversification and AUM growth in the investment management business, supporting future recurring fee revenue and higher net margins."
What could really move the needle now is how one unresolved pressure on funding conditions ultimately feeds through to those future fee margins.
That funding question is exactly why the full narrative for Colliers International Group examines how Colliers International Group could keep fee growth accelerating even if capital markets stay uneven.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move from quiet to flying quickly. Spot potential breakouts and momentum shifts while they are still under the radar for now. Act now.
- Target reliable cash generators with strong balance sheets and resilient earnings profiles using the curated list of solid balance sheet and fundamentals (5 results). This may help before today’s uncertainty is fully reflected in these businesses.
- Consider the structural rerating in electricity demand by scanning carefully selected infrastructure players through the focused 40 power grid technology and infrastructure stocks as grids upgrade and capacity pressure builds.
- Review hand picked copper producers via the curated 16 top copper producer stocks to position ahead of potential changes in resource demand cycles, before institutional money crowds the trade.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com