


Parker-Hannifin earnings event: what changed this quarter
Parker-Hannifin (PH) just released first quarter figures that put fresh numbers around the stock. Revenue, profit and earnings per share all came in higher than a year earlier, giving investors new data to weigh.
The share price tells a cooler story than the fresh earnings. Parker-Hannifin trades at US$892.29 after declining 9.4% on a 1 month share price return and 16.9% on a 3 month share price return, even though the 1 year total shareholder return sits at 7.9% and the 5 year total shareholder return is close to 2x. This suggests that recent momentum has faded while the longer record still reflects substantial value creation for patient holders.
Scan beyond Parker-Hannifin and identify other industrials with similar earnings momentum and recent price pullbacks through our curated list of list of solid balance sheet and fundamentals (24 results)
Parker-Hannifin has just posted higher quarterly earnings while the share price has pulled back sharply. Does it make more sense to step in at US$892 now, or wait for an even cheaper entry before valuing the stock?
Most Popular Narrative: 23% Undervalued
The most followed narrative values Parker-Hannifin at about $1,163 per share, which is well above the last close at $892.29. That gap rests heavily on how investors view the higher margin, longer-cycle parts of the portfolio.
The enlarged portfolio of longer-cycle, higher-margin businesses, including Aerospace, Engineered Materials and Filtration, now represents about 65% of pro forma sales and includes recently added filtration assets. This can increase the share of recurring and aftermarket revenue and support more stable earnings and cash generation across economic cycles.
See why 50 investors see Parker-Hannifin as 23% undervalued.
Result: Fair Value of $1,163 (UNDERVALUED)
Still, the Parker-Hannifin story can change quickly if muted industrial demand persists or if the premium P/E multiple compresses from today’s elevated level.
Find out about the key risks to this Parker-Hannifin narrative.
Another view on Parker-Hannifin’s valuation
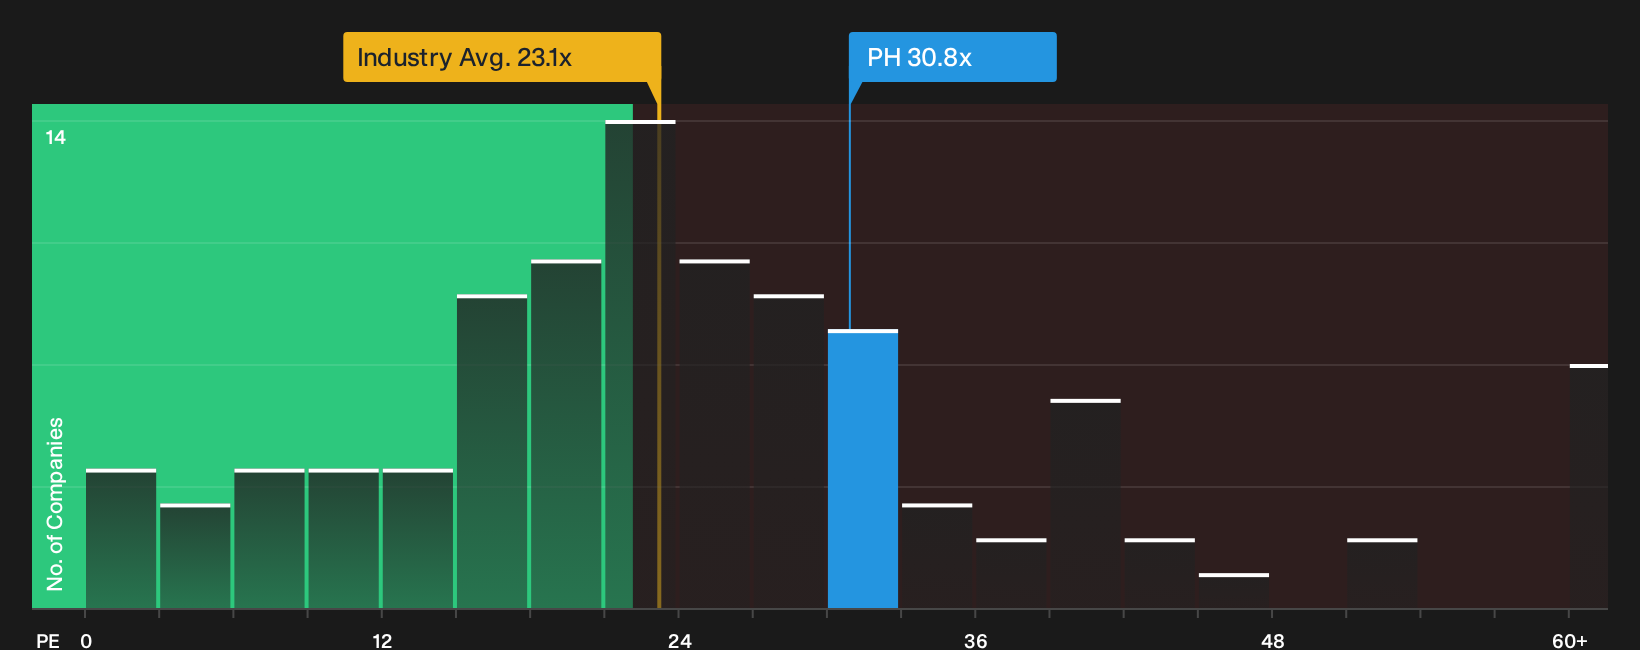
The story so far leans on cash flow and long-cycle earnings to argue Parker-Hannifin looks undervalued. The pricing signal from the market tells a tougher story. The stock trades on a P/E of 30.8x, compared with 23.1x for the US Machinery industry and 22.6x for its peer group.
Even against a fair ratio of 29.6x, the current multiple is higher. That kind of gap can point to investors already paying up for quality and execution. This raises the risk that any earnings wobble hits the share price faster than the underlying business. Which signal do you trust more when you size your position?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Parker-Hannifin so far. If you want to move quickly and judge the trade off for yourself, start with the full rundown of 4 key rewards and 2 important warning signs
Looking for more Parker-Hannifin style investment ideas?
Do not stop at Parker-Hannifin. Use the Simply Wall Street screener to quickly spot fresh opportunities that match your risk tolerance, time horizon and return goals.
- Target resilience first by focusing on balance sheets and fundamentals through our curated list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricings by scanning a focused list of 42 high quality undervalued stocks before the wider market catches on.
- Prioritise consistency and capital protection by zeroing in on 32 resilient stocks with low risk scores that keep overall portfolio swings in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com