


Kurita Water Industries guidance cut puts U.S. project risks in focus
Kurita Water Industries (TSE:6370) reduced its profit outlook for the first half and full year after a detailed cost review of a large U.S. electronics water treatment project significantly raised expected construction expenses.
The guidance cut has quickly fed into sentiment around Kurita Water Industries, with the 7-day share price return down 25.03% and the 30-day move down 33.27% as investors reassess U.S. project risk and earnings quality. Despite this sharp short term reset, the 1-year total shareholder return is down a milder 4.89% and the 3-year total shareholder return is up 17.45%, which suggests long run holders have seen gains even as recent momentum has clearly faded.
Spot fresh water treatment opportunities by comparing Kurita Water Industries with our hand picked list of solid balance sheet and fundamentals (23 results).After a drop of more than 30% over 30 days, Kurita Water Industries now trades on very different expectations. Are you looking at a genuine reset, or at a stock that already reflected most of its rebound story?
Preferred P/E of 12.8x: Is it justified?
On current numbers, Kurita Water Industries trades on a P/E of 12.8x, which places the share price slightly above the broader JP Machinery industry on this measure but below closer peers and the level suggested by some fair value gauges.
The P/E ratio compares the share price to earnings per share. For an equipment and services group like Kurita Water Industries that already reports established profits, it gives a quick sense of how much investors are paying for each unit of earnings. A lower multiple can point to lower expectations, while a higher one can signal that the market is willing to pay more for anticipated profit strength or perceived quality.
Here the 12.8x P/E is described as expensive relative to the JP Machinery industry average of 12.3x, which means the stock carries a small premium to the broader sector. At the same time, that same 12.8x level is framed as good value versus a peer average of 18.1x, and also sits below an estimated fair P/E of 16.6x that the SWS model points to as a level the valuation could move toward if sentiment improves.
Explore the SWS fair ratio for Kurita Water Industries.
Result: Price-to-earnings of 12.8x (UNDERVALUED)
Still, the U.S. electronics project cost overrun and Kurita Water Industries’ exposure to cyclical end markets could challenge any case for a quick sentiment recovery.
Find out about the key risks to this Kurita Water Industries narrative.
Another view on Kurita Water Industries’ value
That 12.8x P/E tag presents Kurita Water Industries as modestly priced against peers, yet the SWS DCF model offers a different perspective. On that approach, the shares at ¥5,358 sit well below an estimated future cash flow value of ¥10,434.96. This frames the current reset as a much steeper discount than earnings alone suggest.
Look into how the SWS DCF model arrives at its fair value.
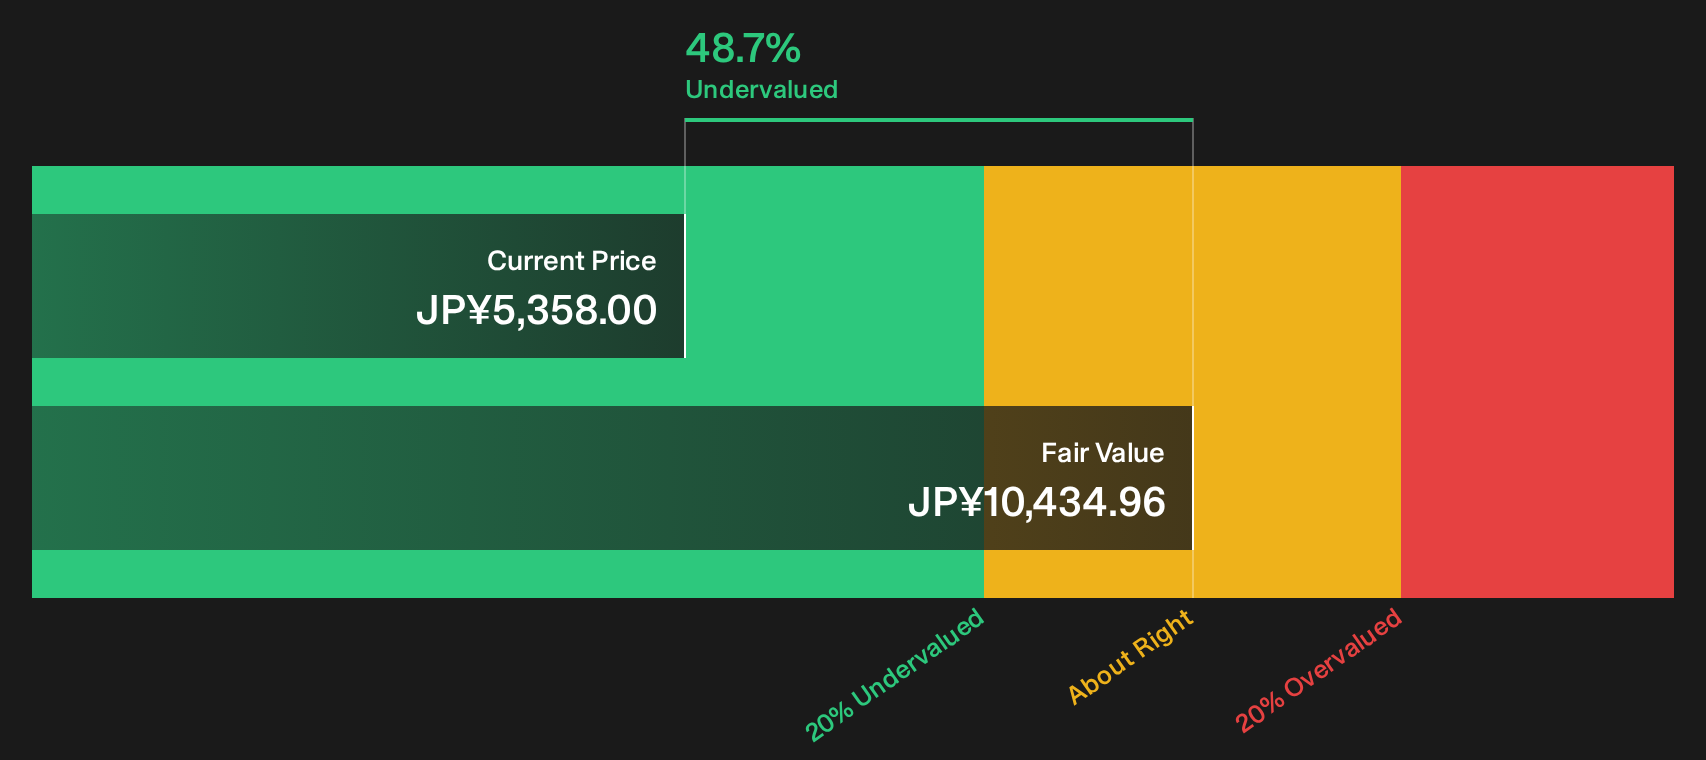
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kurita Water Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Kurita Water Industries can leave you stuck on the fence, so move quickly, review the full data set, and weigh the 5 key rewards and 1 important warning sign.
Looking for more Kurita Water Industries sized opportunities?
Do not stop with Kurita Water Industries. Fresh ideas often come from comparing it with other companies that have different risk, income, and valuation profiles.
- Target steadier rides by checking companies with low historical risk scores through the 22 resilient stocks with low risk scores.
- Hunt for potential mispricing by scanning quality businesses trading below estimated worth using the 19 high quality undervalued stocks.
- Build a watchlist of lesser known prospects with solid fundamentals by reviewing the 74 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com