


SiTime (SITM) just delivered a Q3 2026 earnings update that sharply reshaped the story, with higher revenue, a swing to profit, and a planned three for one stock split catching investor attention.
Despite the upbeat Q3 headlines and the planned stock split, SiTime’s recent share price has been volatile. The stock fell 11.97% on the day, 27.27% over the past week, and 50.07% across 30 days. At the same time, the 1-year total shareholder return of 4.47% and the very large 3-year total shareholder return suggest that longer-term momentum has previously been much stronger than the latest pullback implies.
Capitalize on the volatility around SiTime by comparing it with 53 AI infrastructure stocks, which could also be sensitive to the same AI data center and semiconductor spending trends.After a swing back to profit, a very sharp pullback, and a stock split on the way, SiTime now sits at a crossroads. Do you lean into the reset or wait for the valuation to cool further?
Most Popular Narrative: 57% Undervalued
SiTime’s most followed narrative pegs fair value at $832.27 versus a last close of $355, which frames the recent share slump against a much higher long term earnings and cash flow profile.
The numbers imply that the current valuation prices SiTime as if its timing TAM nearly doubles by 2030, its run-rate moves toward around US$1.2b of annual revenue, and elevated profitability levels are maintained. This narrative views those conditions as supportive of a bullish stance on the shares.
See why 15 investors see SiTime as 57% undervalued.
Result: Fair Value of $832.27 (UNDERVALUED)
Still, SiTime’s heavy tilt toward communications, enterprise and data center demand, along with execution risk around the Renesas timing acquisition, could quickly challenge that bullish narrative.
Find out about the key risks to this SiTime narrative.
Another View: SiTime Through The P/S Lens
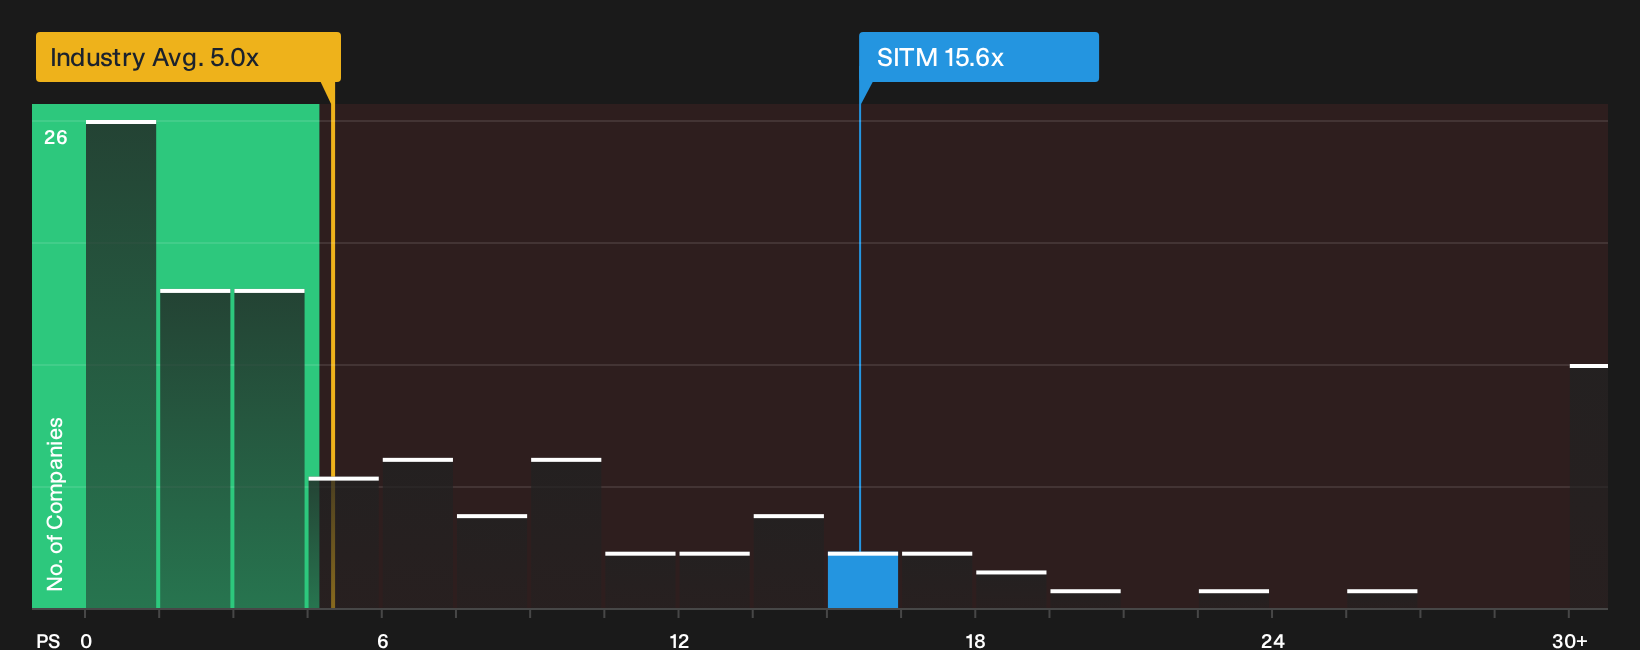
The first narrative paints SiTime as 57% undervalued on long term earnings and cash flow. A simple P/S check tells a tougher story. The stock trades at 15.6x sales versus a fair ratio of 13.2x, the US Semiconductor sector at 5x, and peers at 8.3x, which points to meaningful valuation risk if expectations reset.
That gap between today’s rich P/S and the lower fair ratio is what you are really betting on. It may narrow if sentiment cools, or persist if the growth case holds. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of investors are excited while others are cautious, which is exactly why it pays to move quickly through the full picture and form your own call. To weigh those cross currents in one place, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond SiTime?
If SiTime is already on your radar, do not stop here. A few minutes with targeted stock lists can surface opportunities you might wish you had seen earlier.
- Hunt for quality at a discount by checking companies that pass the 42 high quality undervalued stocks and see which ones align with your return and risk expectations.
- Strengthen your defensive side by scanning the list of solid balance sheet and fundamentals (24 results) and focus on businesses with balance sheets that can better handle shocks.
- Get ahead of the crowd by reviewing the 21 high quality undiscovered gems and spot strong fundamentals before they gain wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com