


- CBL & Associates Properties reported third quarter 2026 revenue of US$148.7 million and net income of US$11.79 million, along with a 23% increase in adjusted FFO per share and stronger portfolio occupancy and leasing activity.
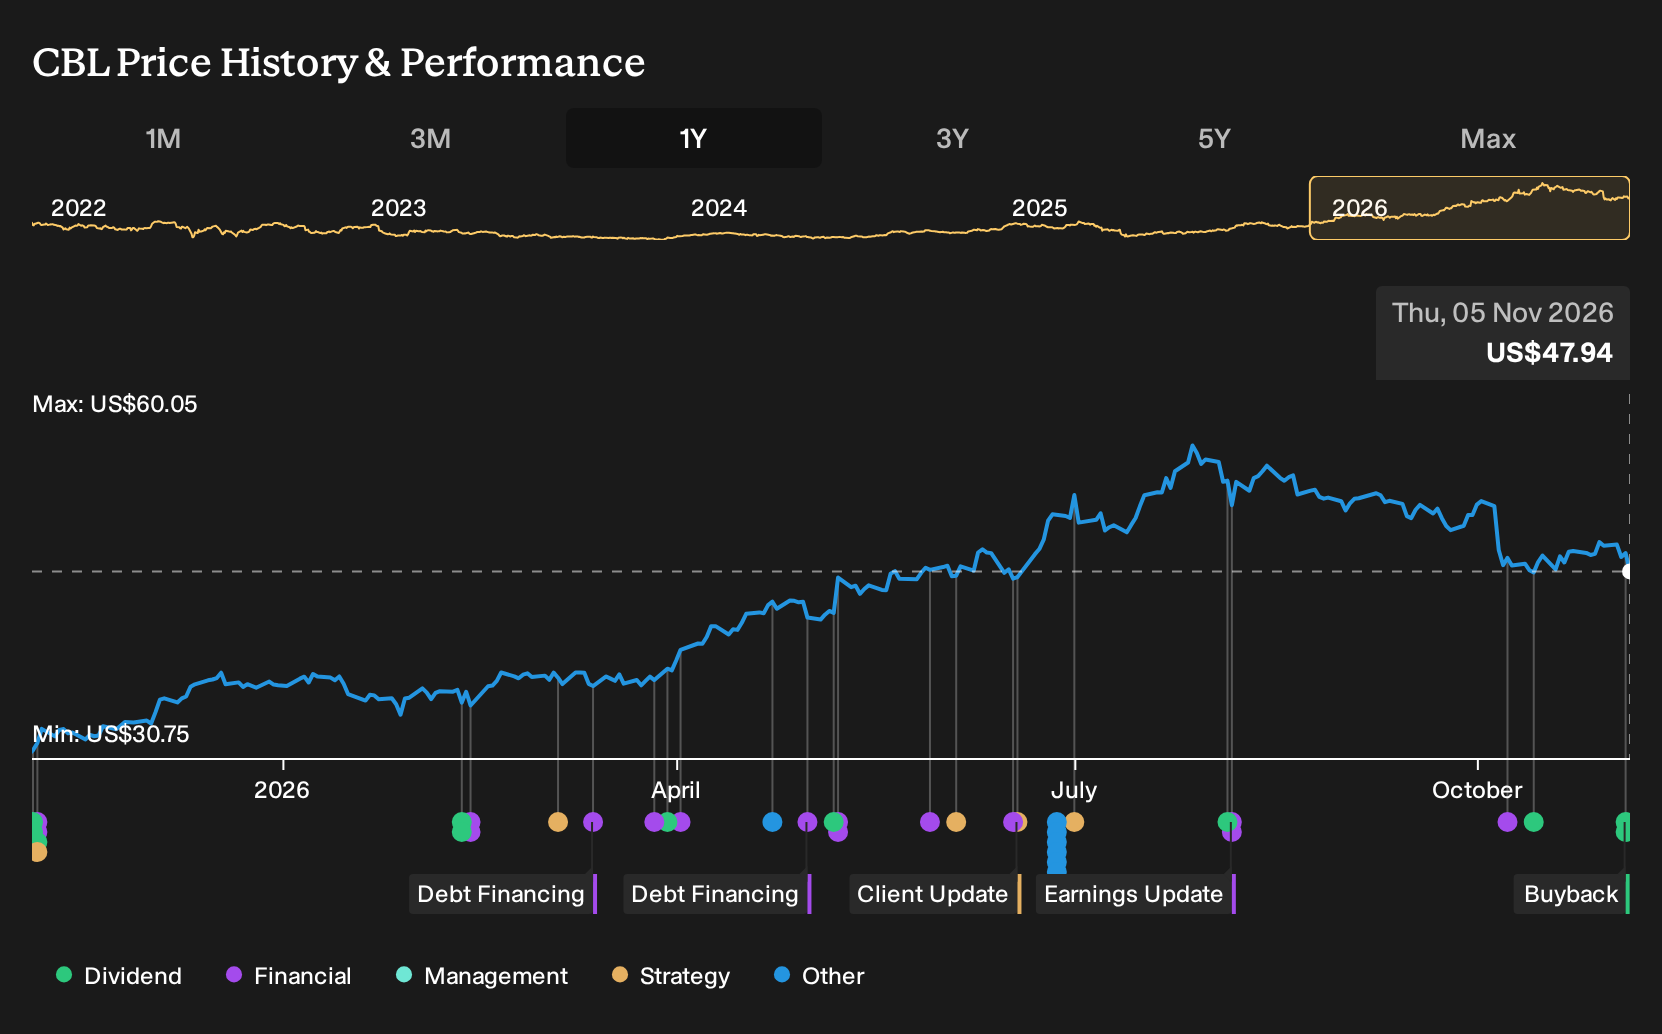
- The board authorized a new US$25 million share repurchase program running through December 31, 2027, which indicates management’s conviction in CBL & Associates Properties’ cash generation and its view that the stock trades below the quality of its assets.
- This article will discuss how CBL & Associates Properties’ investment narrative is influenced by higher adjusted FFO and the new share repurchase authorization.
Compare CBL & Associates Properties’ buyback and FFO story with a hand picked group of real estate peers, screened for value, balance sheet strength, and income potential in the 42 high quality undervalued stocks.
What Is CBL & Associates Properties' Investment Narrative?
To own CBL & Associates Properties, you need to buy into a straightforward real estate story. The portfolio is mall heavy and capital intensive, so everything starts with occupancy, rent levels, and keeping properties leased at reasonable cost. The latest quarter showed higher revenue of US$148.7 million and adjusted FFO per share rising 23%, which supports that operational angle more than the headline net income drop. The new US$25 million buyback ties into this as it signals management is comfortable using cash to reduce share count rather than hoard liquidity.
In the short term, the key swing factors remain leasing momentum, tenant sales, and the ability to reinvest in centers without stressing the balance sheet. CBL & Associates Properties reported no major debt maturities until 2028 and a cash balance above US$366 million. This provides some flexibility, but interest costs still matter given prior commentary that coverage is tight. The buyback and higher FFO guidance slightly improve the story around capital allocation and earnings power. At the same time, the recent share price pullback over the past 90 days suggests the market is still wrestling with the durability of those earnings once one-off items fade.
Yet there is a lingering issue around the quality of those earnings that could change how you read all of this...
There's only one way to know the right time to buy, sell or hold CBL & Associates Properties. Head to Simply Wall St's company report for the latest analysis of CBL & Associates Properties's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$44.54 and US$63, which already shows a broad spread for CBL & Associates Properties. Those views were formed before the latest buyback and earnings news, so treat them as one snapshot, and compare them with fresh information on cash generation, balance sheet resilience, and tenant trends.
Explore another CBL & Associates Properties fair value estimate, including one that suggests as much as 7% downside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CBL & Associates Properties research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for CBL & Associates Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CBL & Associates Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond CBL & Associates Properties?
If you want to stress test what you think about CBL & Associates Properties against a wider opportunity set, it helps to scan other real estate and income ideas side by side. The Simply Wall St Screener can narrow the field to stocks that better match your risk tolerance, return goals, and balance sheet preferences.
- If you care most about long term resilience and capital preservation, start with a curated group of companies that screen well on downside risk and balance sheet quality through the 32 resilient stocks with low risk scores.
- Income focused investors can concentrate on businesses that pair higher yields with more robust fundamentals by reviewing the 6 dividend fortresses.
- Those hunting for mispriced opportunities can broaden their watchlist with a value oriented set of financially stronger stocks through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com