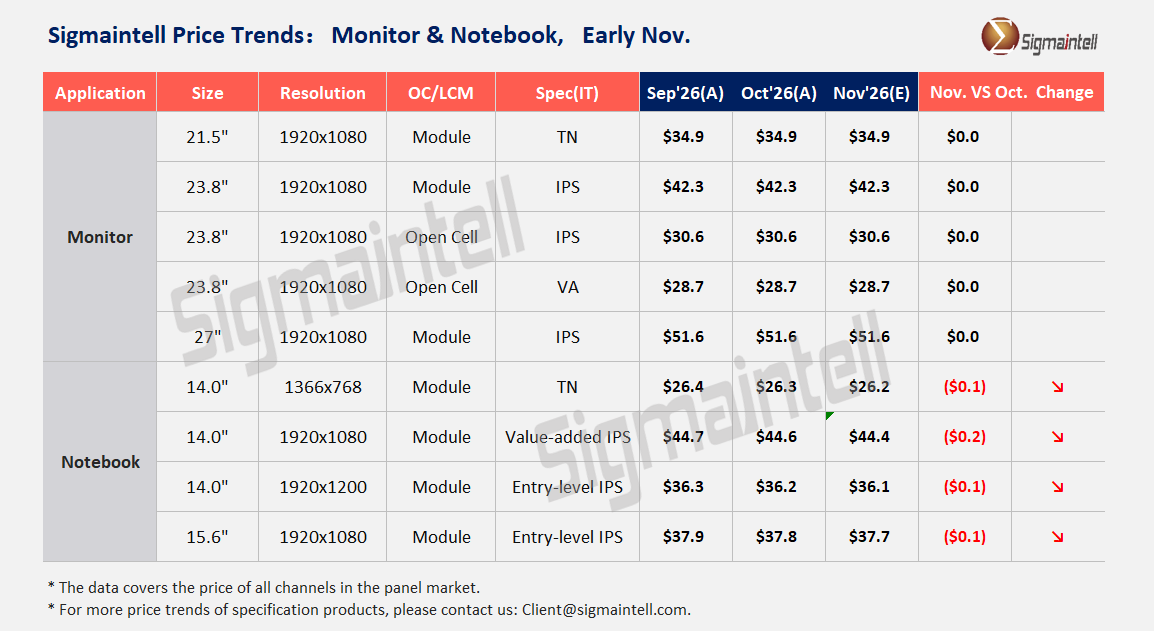
The Zhitong Finance App learned that Qunzhi Consulting published an article stating that in November, the price of mainstream panel sizes of global displays continued to trend steadily, and the market continued the price stability game under a weak balance. On the demand side, pre-holiday preparations for the fourth quarter of sales at home and abroad have basically ended, and the peak sales performance of terminals falls short of expectations, and brand inventory is still high, and there is insufficient momentum to replenish stocks; on the supply side, panel manufacturers continue to have a dynamic production control strategy, and the decline in supply and demand generally matches the decline in demand, and the display panel market maintains a dynamic balance and a slightly relaxed pattern; due to the cost pressure brought about by rising material prices, the operating pressure on panel manufacturers continues to increase, and the price increase attitude is further heating up; however, terminal demand continues to weaken, and the cost of the whole machine continues to rise. The price war between the two sides continues to be in turmoil. Prices for specific customer groups are expected to loosen this month, but judging from current price trends, there is still not enough momentum to drive the average price increase.
According to Qunzhi Consulting, prices of mainstream specifications continued to be stable in November:
21.5"FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in November;
23.8"FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in November;
27"FHD, Open Cell & LCM mainstream panel prices remained flat month-on-month in November;
Notebook panel
In November, the loosening of global laptop panel prices will expand further. Prices for mainstream and entry-level specifications will generally decline, and mid-range and high-end specifications will continue to differentiate. On the demand side, poor inventory removal in the notebook brand channel was further transmitted to the panel side, increasing the inventory removal of brand panels to a certain extent, and the momentum of panel pulling continues to weaken; on the supply side, the cost of many panel components is rising, which will continue to drive up panel BOM costs in the fourth quarter of 2026. Looking at both the supply and demand sides, panel manufacturers are still forced to actively ship in order to achieve their annual business goals even though cost pressure is still there. Qunzhi Consulting predicts that the typical price of notebook panels will continue to decline in November, and the performance of various specifications will diverge. The panel price performance is as follows:
Low-end HD TN: November price reduced by $0.1 month-on-month;
IPS FHD&FHD+ products: On November 16:9, mainstream specifications were reduced by $0.1 month-on-month; at 16:10, the price of entry-level specifications was reduced by $0.1 to 0.2; the price of mid-range and high-end panels continued to diverge.