


Amkor Technology (AMKR) just posted third quarter 2026 results, reporting sales of about US$2.0b and net income of US$190.6m, along with fresh guidance and a recently completed share repurchase tranche.
Despite the solid third quarter headline numbers and fresh buyback activity, Amkor Technology’s share price has swung sharply lower. It has fallen 14.5% on the day, 26.0% over the past week and 42.9% across 30 days, as investors digest new guidance, a trimmed fair value estimate of US$66.00 and mixed sentiment around capital spending and Communications exposure. This comes even though total shareholder return over three and five years remains positive at 39.4% and 41.2% respectively.
Spot opportunities that echo Amkor Technology’s mix of earnings power and volatility by scanning our hand picked 42 high quality undervalued stocks with solid cash generation and balance sheets.Amkor Technology is producing healthy profits and investing heavily in advanced packaging, yet the share price has almost halved in a month. Are investors now underestimating the business, or correctly marking down the valuation?
Most Popular Narrative: 54% Undervalued
The most followed narrative pegs Amkor Technology’s fair value at $66.00, well above the last close at $30.49. As a result, the recent selloff sits against a valuation gap built on AI packaging and long term capacity plans.
Acceleration in AI data center and high performance computing programs, including HDFO CPU ramps and multiple 2.5D and high density fan out engagements, is increasing demand for advanced packaging. This can support higher revenue and a richer mix that benefits gross margin and earnings.
See why 24 investors see Amkor Technology as 54% undervalued.
The narrative relies on a 12.54% discount rate and assumes Amkor Technology can support $10.2b in future annual revenue with an 8.25% profit margin. These inputs feed into the $66.00 fair value estimate. That view also leans on a future P/E of 27.78x, compared with a much lower multiple implied by the current share price after the recent decline.
Result: Fair Value of $66.00 (UNDERVALUED)
Still, heavy capital commitments in Arizona and other regions, along with ongoing Communications softness, could erode margins and challenge the bullish Amkor Technology narrative.
Find out about the key risks to this Amkor Technology narrative.
Another View: Cash Flows Paint A Harsher Picture
While the popular Amkor Technology narrative leans on earnings and a $66.00 fair value, the SWS DCF model points in the opposite direction. On that cash flow view, AMKR at $30.49 trades well above an estimated value of $4.32, which suggests far less potential upside and significantly more valuation risk. Which version of reality do you trust when the numbers clash this sharply?
Look into how the SWS DCF model arrives at its fair value.
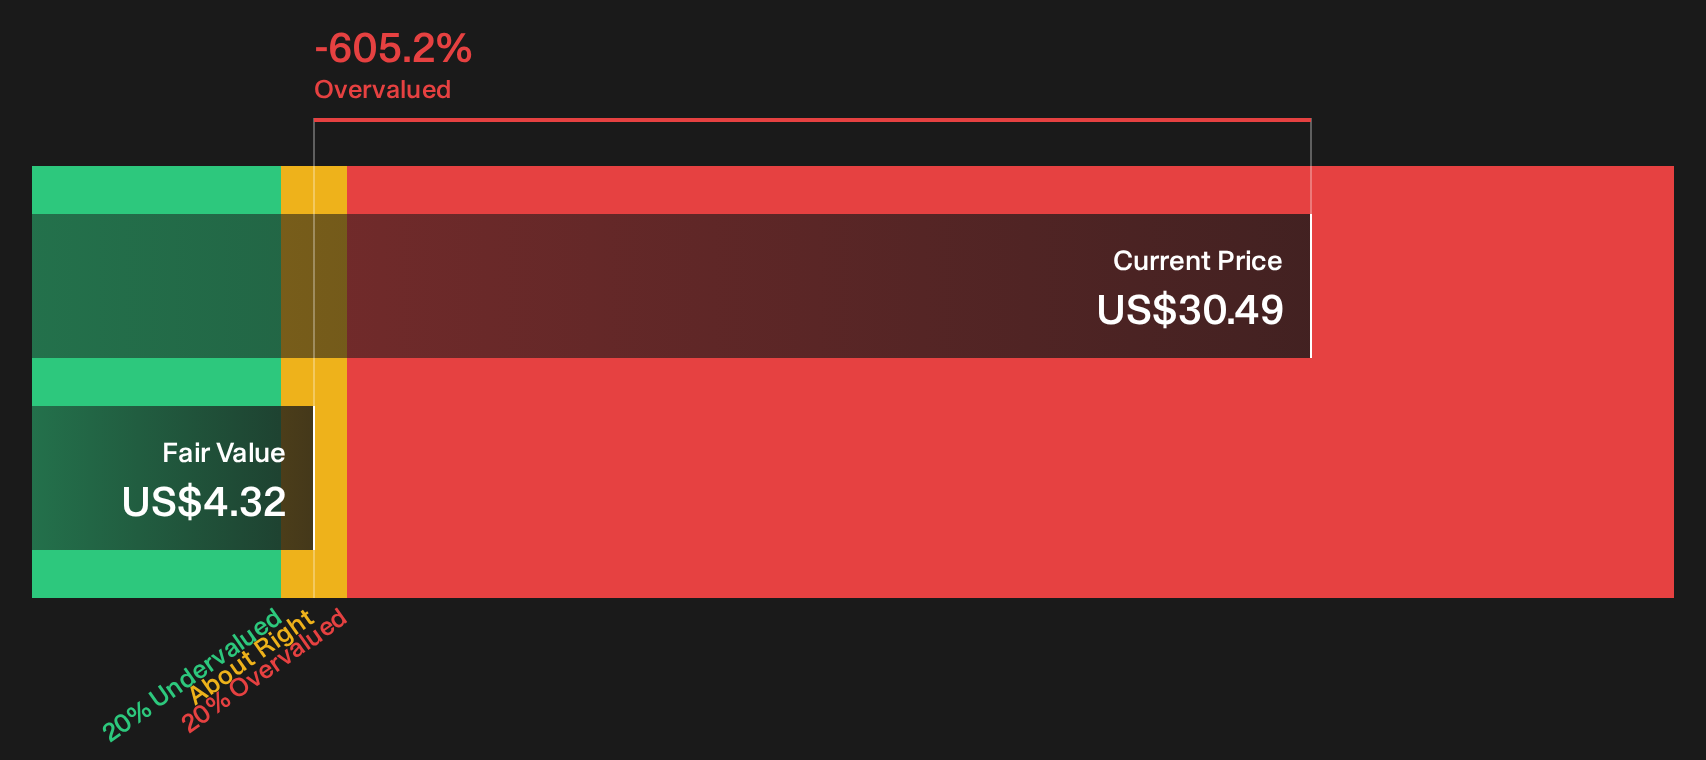
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amkor Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big reactions like this often spark strong opinions, yet the real edge comes from acting quickly and testing the facts yourself against both the upside and the downside case. Start with the 4 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Amkor Technology?
Do not stop with one volatile chart. Use the Simply Wall St Screener to quickly surface fresh ideas that fit the kind of portfolio you actually want to build.
- Target resilient compounding by scanning a 32 resilient stocks with low risk scores that prioritises balance sheet strength and lower risk profiles.
- Chase value opportunities by reviewing a 21 high quality undiscovered gems built around strong fundamentals that fewer investors are watching closely.
- Reinforce income potential through a 6 dividend fortresses focused on companies offering higher yields with supporting financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com