


Why Wendy's stock is back in focus
Wendy's (WEN) is in the spotlight after rejecting a roughly US$1.4b takeover proposal linked to Nelson Peltz, scrapping that bid and adopting a poison pill while reporting detailed third quarter 2026 earnings.
The rejected US$1.4b offer and new poison pill follow a sharp rebound in Wendy's share price, with a 1-month share price return of 28.9% and a 7-day gain of 10.8%, although the 5-year total shareholder return remains down 53.4%.
Capitalize on the renewed spotlight around Wendy's by reviewing hand-picked restaurant and consumer stocks showing stronger fundamentals in the 21 high quality undiscovered gems.Wendy's has surged on a rejected buyout and a poison pill, even as recent earnings show pressure on traffic and profits. Is this upswing pointing to a reset in fundamentals, or just a swing in sentiment that valuation now needs to test?
Most Popular Narrative: 5% Overvalued
Wendy's last closed at $7.94, a touch above the most followed fair value estimate of $7.57 that uses a 12.54% discount rate. The gap is small in dollar terms, but the narrative leans on very specific assumptions about digital adoption, international expansion, and franchise health.
The company's increased investment in digital platforms, including mobile ordering, AI driven recommendation engines, digital menu boards, and self order kiosks, is still building on U.S. digital sales growth in 2025 and early 2026 and could gradually support higher revenue per customer and improved labor efficiency, which would feed into net margins and earnings.
See why 28 investors see Wendy's as 5% overvalued.
Result: Fair Value of $7.57 (OVERVALUED)
Still, the Wendy's story involves weak U.S. franchise economics and rising beef costs that could offset digital gains and keep the turnaround thesis under pressure.
Find out about the key risks to this Wendy's narrative.
Another View: What Wendy's P/E Ratio Is Signaling
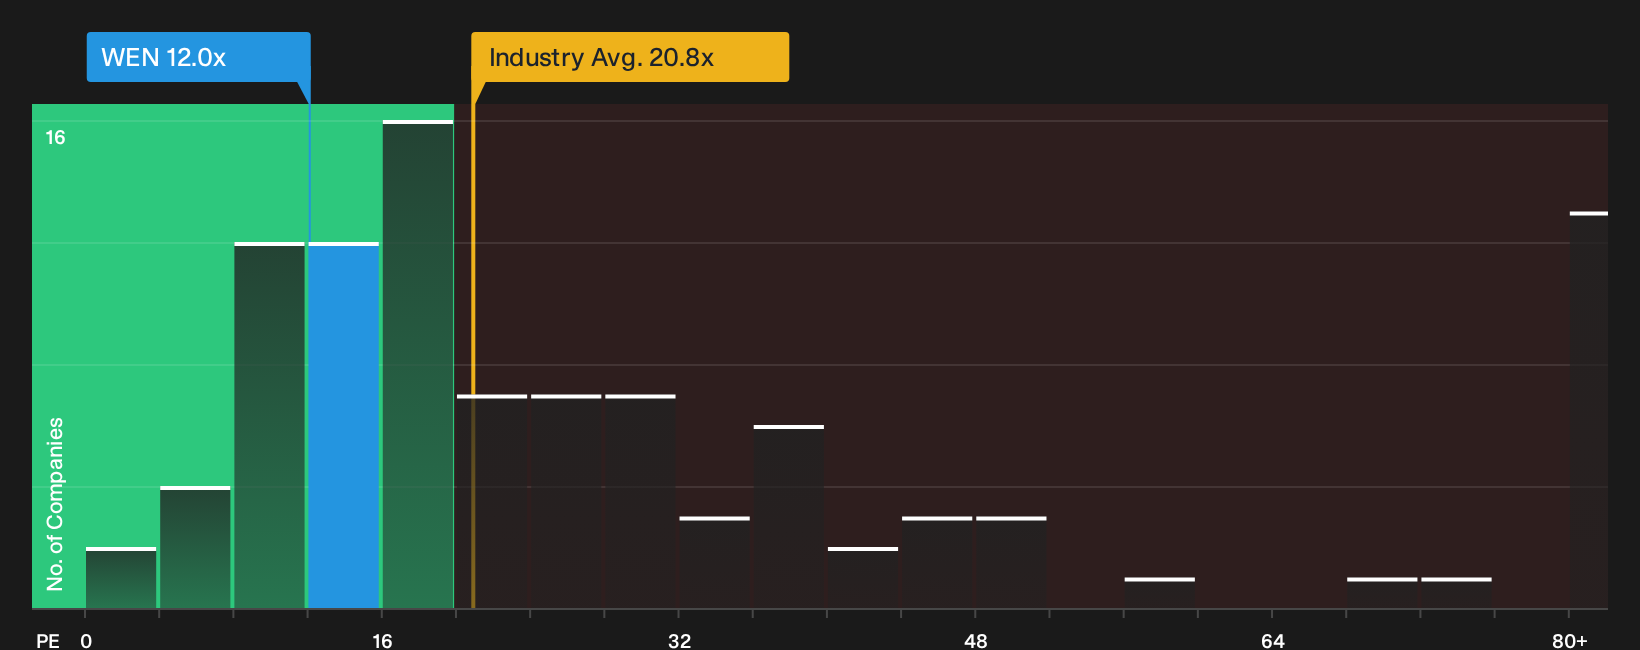
While the most followed fair value narrative pegs Wendy's as 5% overvalued at $7.57, the market’s simple P/E yardstick paints a different picture. At roughly 12x earnings, the stock trades far below both peers at 46.1x and the US Hospitality group at 20.8x, and also below its own fair ratio of 16.2x. That gap suggests the market is pricing in heavier risk than these earnings and forecasts imply, so the real question is whether that discount reflects caution or an overreaction you think could close over time.
Our valuation work examines that P/E gap in more detail, unpacking how the current price compares to peers today and where the fair ratio suggests the multiple could move if sentiment changes, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Wendy's can easily pull you in both directions, so move quickly, stress test the numbers yourself, then weigh the 3 key rewards and 3 important warning signs
Looking for more Wendy's style investment ideas?
Do not stop with Wendy's. Broader context matters, and the right mix of quality, resilience, and upside ideas could be sitting just beyond your current watchlist.
- Target stronger balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) so you are not guessing who can handle the next shock.
- Zero in on potential mispricings by reviewing a focused 42 high quality undervalued stocks that points you toward companies the market may be treating too cautiously.
- Prioritise peace of mind by checking a pre filtered 32 resilient stocks with low risk scores so your capital is working without taking on more volatility than you want.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com