


Flowers Foods (FLO) has drawn fresh attention after announcing the election of veteran finance executives Shaun P. Mara and Ken Plunk as independent directors. Both will join the board’s audit and finance committees.
Flowers Foods shares have bounced in the short term, with a 7 day share price return of 14.9% and a 30 day gain of 23.7%. However, longer term momentum has faded, given the 1 year total shareholder return is down 33.5% and the 5 year outcome has fallen 64.2%.
Compare Flowers Foods' board refresh with other consumer-focused businesses that screen well on governance and financial quality by scanning our 32 resilient stocks with low risk scores next.
After a sharp rebound yet weak multi year returns, the real issue for Flowers Foods now is whether the current share price still leaves enough upside to justify the business risk.
Most Popular Narrative: 4% Undervalued
On the latest numbers, the most followed narrative pegs Flowers Foods at a fair value of $7.40 versus a last close of $7.10. This frames a modest valuation gap built on detailed cash flow and earnings assumptions.
Analysts expect Flowers Foods to keep facing pressure in traditional loaf bread while leaning on Better For You bread and snacks, brand renovation and cost control to support the business over time.
The main thing that has to go right is Flowers Foods successfully shifting its portfolio and marketing toward Better For You and snacking platforms while managing promotions, costs and leverage so that earnings pressure does not outweigh mix and efficiency gains.
See why 32 investors see Flowers Foods as 4% undervalued.
Result: Fair Value of $7.40 (UNDERVALUED)
Still, the narrative can break if softness in core loaf bread deepens, or if higher oil-linked costs eat into the margin recovery analysts are banking on.
Find out about the key risks to this Flowers Foods narrative.
Another View On Flowers Foods Valuation
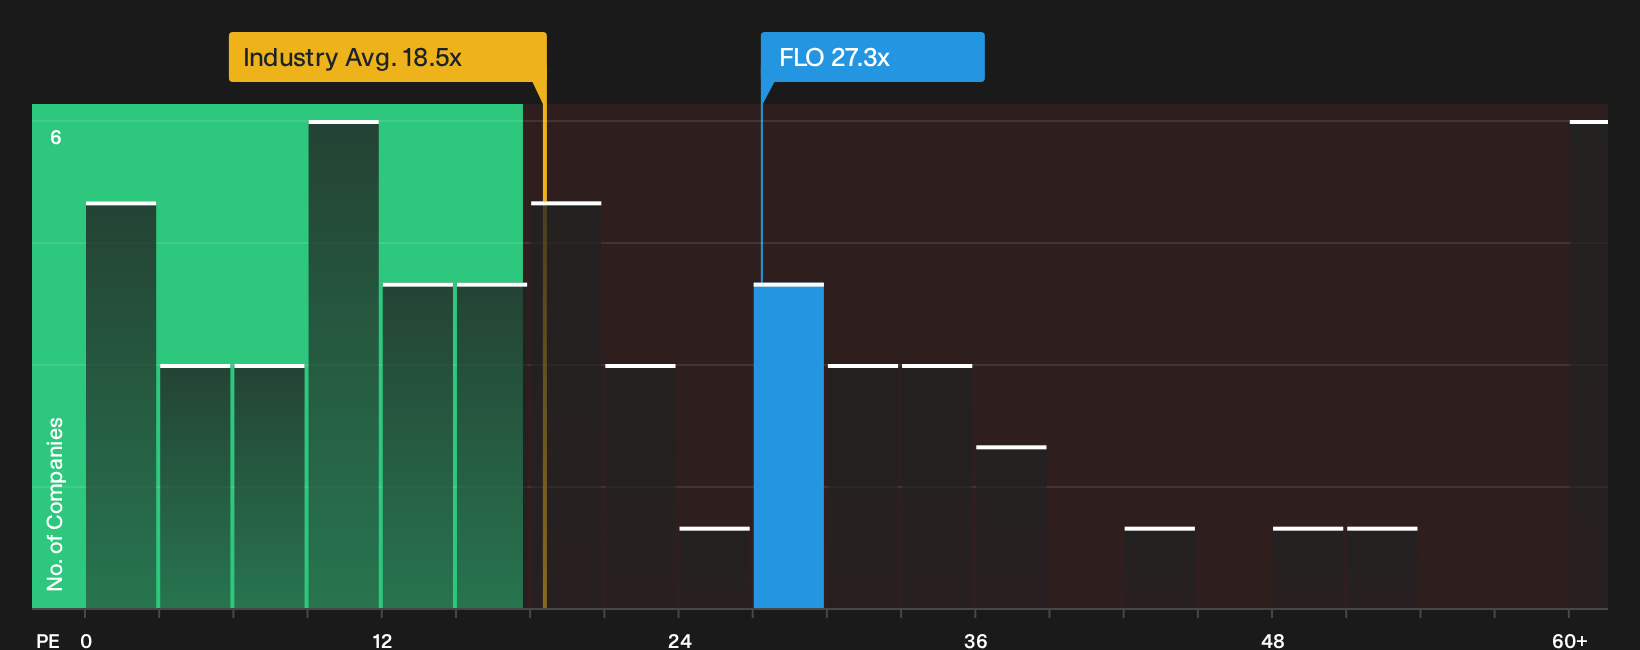
The cash flow story paints one picture for Flowers Foods, but the earnings multiple tells a very different one. Shares trade on a P/E of 27.3x, compared with 18.5x for the US Food industry, 22.7x for peers, and a fair ratio of 17.6x that our work points to.
That gap suggests investors are already paying up for the future profit recovery analysts model, even while revenue is expected to edge lower and margins only gradually rebuild. The question is whether that premium multiple will hold if the Better For You and snacking push takes longer to show through.
Before leaning too heavily on any single approach, it helps to see how the earnings-based view stacks up against other ways of looking at value. This is where our detailed valuation breakdown comes in, See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how Flowers Foods’ current earnings valuation compares with its sector and where the fair ratio sits, refer to
Next Steps
Does this mix of pressure and potential around Flowers Foods leave you optimistic or cautious? Act while the data and sentiment are fresh, and weigh both sides using our 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Flowers Foods?
If Flowers Foods has you rethinking where risk and reward really line up, broaden your playbook now and line up a few fresh contenders.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) before capital flows to the next quality pocket.
- Hunt for pricing that still looks appealing with the help of the 42 high quality undervalued stocks so you are not late to the next re-rating story.
- Build a cash flow stream that works harder for you by reviewing the 6 dividend fortresses while yields and coverage profiles remain attractive.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com