


The Democratic Party took back both houses of Congress in the US midterm elections and achieved election breakthroughs in key data center construction states, pushing the market to re-evaluate the speed and cost of AI infrastructure expansion. As far as the Asian financial market is concerned, this policy reassessment seems to have two sides — that is, if investment in US data centers slows down, it may weaken demand for chips, servers, and ancillary equipment, and impact North Asian exports and corporate profits; at the same time, the market is betting on falling oil prices due to the cooling of the Iran war, which is also expected to ease inflation, trade deficits, and fiscal pressure on energy importers. The core change facing Asian assets can be described as a rebalance between AI export earnings and energy import costs.
The market first experienced fragmentation and then turned to widespread sell-off. On Wednesday, Microsoft, Amazon, Alphabet, and Meta rose 6.7%, 6.1%, 3.2%, and 1.4%, respectively. The slowing pace of global capital betting expansion could reduce pressure on capital expenditure and increase the value of existing computing power; the Philadelphia Semiconductor Index fell 3.13%.
The Zhitong Finance App observed, however, that on Thursday, when the Democratic Party swept through both houses of Congress and the midterm elections in important Republican states such as Texas, combined factors such as major uncertainty at the regulatory level, and weak Qualcomm's mobile phone chip business, and the sell-off spread to technology platforms: the Nasdaq 100 Index, which has the title of a “global technology stock weather vane,” plummeted 6.36% — the biggest one-day percentage drop since March 2020. The Philadelphia Semiconductor Index plummeted 12.25%, and tech giants whose stock prices had previously risen also generally declined. The market is beginning to simultaneously reduce the growth expectations of AI computing power hardware vendors, as well as the valuation affordability of the entire AI sector, including Amazon, Google, and tech giants such as Microsoft and Meta.
In the Asian market on Friday, the sharp impact of AI data centers triggered by this policy expectation was further transmitted to Asia. South Korea's KOSPI benchmark index fell about 8.8% during the intraday period, falling below the target mark of 5,000 points proposed by South Korean President Lee Jae-myung during the election campaign, and triggered a 20 minute meltdown; the decline then narrowed and finally closed at 5059.69 points, falling 6.02%, not closing below 5,000 points. Japan's Nikkei 225 index closed down 5.96%, while Taiwan's weighted index closed down 4.51%. These markets are highly dependent on AI hardware exports, rapidly transforming changes in the pace of US construction into profit expectations and stock price pressure.
From chip orders to crude oil bills, is the growth resilience of the Asian market being reordered?
The transmission chain of the slowdown in AI investment is that delays in data center delivery affect equipment procurement, which in turn reduces orders for chips, storage, networks, and power support, and may weaken supply chain prices and profit margins.
The South Korean and Chinese markets can be described as being directly exposed to this chain; similar to the South Korean economy, where exports of memory chips account for an important share of GDP, the latter also faces the risk of high-tech exports cooling down — net exports contributed nearly 40% of economic growth in the third quarter, and computers and chips contributed 40% to the increase in exports so far this year. Furthermore, although hardware products related to AI infrastructure are expected to be the first to circulate within the Asian supply chain, this does not mean that their final demand is independent of US data center investment.
According to global investors, South Korea and China are at the forefront of the transmission of potential US trillion-dollar AI data center construction and investment to Asian exports. Although quite a few of the key components of AI infrastructure such as chips and storage high-performance products and PCBs\ MLCCs\ packaging substrates\ electronics that China and South Korea focus on exports first circulate within the Asian supply chain or in the construction of AI data centers in the Asia-Pacific region, US data centers are still the largest source of terminal demand. Therefore, the slowdown in the pace of US construction may significantly affect exports and corporate profits between the two regions through purchase orders and product prices.
The fall in oil prices was buffered by lowering import bills, energy subsidies, and corporate investment costs. India is close to 90% dependent on crude oil imports, and is more likely to benefit from lower energy and equipment costs compared to Northeast Asia.
Indonesia and the Philippines are also expected to see improvements in fiscal or inflation. However, Indian IT services are still dependent on global corporate technology budgets. Fan Limin, chief economist at HSBC Asia, pointed out that other regions in Asia may handle some US data center requirements.
Therefore, technology investment judgments in the Asian region may require further differentiation: as the Democratic Party takes control of the US Senate and House of Representatives, the US AI data center construction process may slow down significantly, which will undoubtedly impact the supply chain associated with AI infrastructure in Asia; however, as tech giants such as Google, Amazon, and Microsoft actively shift AI data center projects to Asia, and Tencent and Alibaba may also speed up the construction of AI data centers, it may strengthen a significant portion of the demand for semiconductors and power equipment, and increase the value of local power supply and data center resources.
This is why, according to some Wall Street analysts, investment in technology and electricity in Asia needs to further differentiate between slowing global demand and adjustments in construction layout. Policy uncertainty after the US midterm elections may extend the data center approval, power supply access, and construction cycle; if the project extension further slows down global equipment procurement, exports and profit expectations related to South Korea, Taiwan, and mainland China will be under pressure. However, restrictions on US expansion may also push hyperscale cloud vendors such as Google, Amazon, and Microsoft to speed up their deployment in Asia.
. Morgan Stanley believes that the potential spillover demand of about 15 GW, which was expected to be absorbed by Asia by 2030, may be realized ahead of schedule as the utilization rate of local data centers increases. Together with the AI construction needs of Asian cloud vendors such as Alibaba and Tencent, this is expected to support some orders for semiconductors, power equipment, and energy storage, and increase the value of reliable power supplies, deliverable grid-connected capacity, and data center resources. In particular, Damo emphasized that the tightening of electricity supply and demand may shift the bargaining advantage to power generators and power grid operators, so the increase in equipment demand and the improvement in power asset profits need to be judged separately.
At the same time, falling oil prices have provided another layer of buffer for Asian growth by reducing energy import expenses, corporate investment costs, and the burden of financial subsidies. Economies such as India, Indonesia, and the Philippines are relatively less dependent on AI hardware exports, and the benefits of falling energy costs are more prominent; Northeast Asian economies need to find a balance between pressure on export orders and improved import costs. The diversification of Asian assets will increasingly depend on US terminal demand exposure, actual ability to handle new computing power, and how much lower energy costs can translate into improved profits and purchasing power.
The Asian market ushered in a post-election AI supertest, but falling oil prices brought a glimmer of light
If the US election finally cools down the AI boom, Asian export powerhouses may be hit hard. However, for this region, which is driving global economic growth, the news isn't all bad.
On Friday, the market sell-off that spread from the US to Asia triggered the collapse of the Seoul stock market and caused the Tokyo and Taipei stock markets to fall into a bear market, reflecting market fears that Washington will put the brakes on data center construction. This will cool down demand for chips and other electronic products, which previously drove trade surpluses to record levels. China faces the risk of losing some of its high-tech exports, which have always supported the operation of the economy. Other economies, such as South Korea, are more exposed to risk.
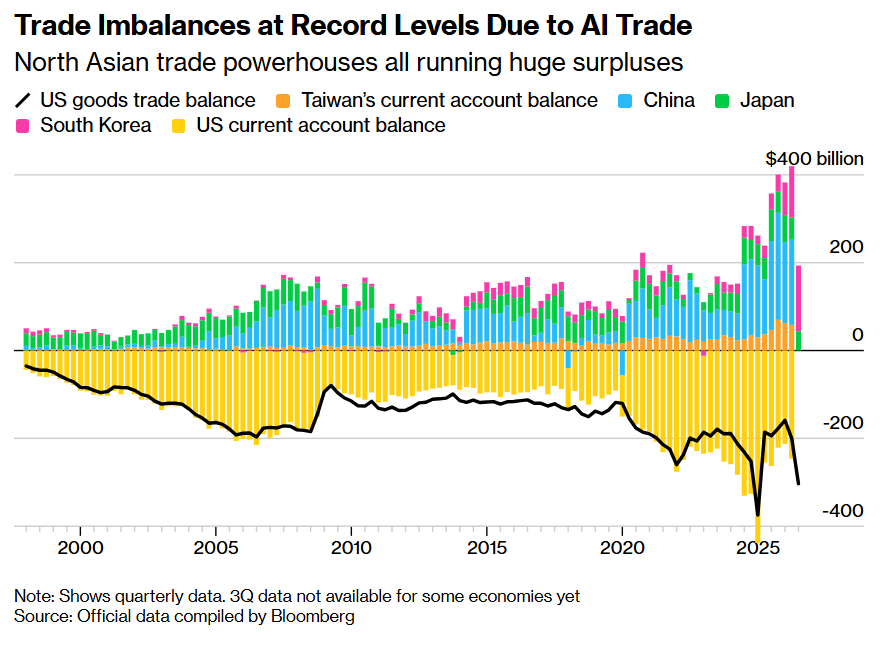
As shown in the chart above, AI trade has driven trade imbalances to record levels — in particular, economies with strong trade in Northeast Asia have recorded huge surpluses.
However, the disastrous defeat of President Trump's Republican Party in this week's midterm elections may have brought more than that to the world economy.
Trump's war on Iran was unpopular with American voters, and triggered another powerful force that has shaped economies this year: soaring energy costs. Major Asian economies are energy importers, so they have been directly impacted. Countries such as India and Indonesia are under pressure on their external balance of payments and local currency exchange rates. Brent crude oil fell 15% this week, bringing relief as markets expected the conflict to cool down.
Fan Limin, Asia's chief economist at HSBC Holdings, said that the decline in the AI trading boom “will have a ripple effect on Asian economies.” “Demand for all kinds of products, from chips and cables to cooling systems and power conversion equipment, is slowing down, which will inevitably slow down export growth.” On the other hand, “falling energy prices will largely cushion the pressure on Asian economic growth.”
Of course, American voters want the war to end, and there is no guarantee that the US-Iran war will end. There is currently no clear answer as to how the Democrat-led Congress and state governments will regulate AI. Trump still has trade policy tools such as tariffs; during his second term, these tools have been another important factor disrupting the Asian economy.
Here's a rundown of some of the key issues the US election posed to Asia and the Pacific's most important economies.
China
Net exports contributed nearly 40% to China's economic growth in the third quarter, the highest level since the beginning of 2025. Among them, high-tech products played a leading role. A recent study published by Bloomberg Intelligence indicates that if the development of AI in the US slows down, China will face “relatively severe economic headwinds,” and falling computer hardware prices may squeeze the profit margins of the entire supply chain.
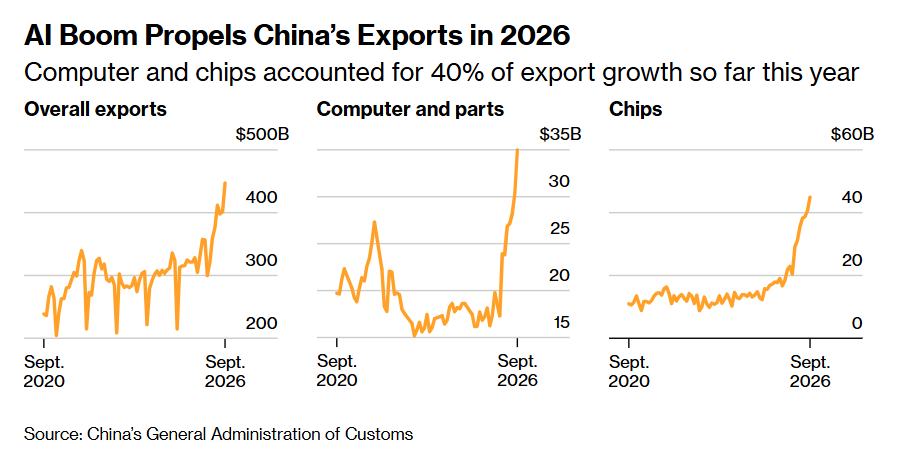
As shown in the chart above, the AI boom is driving China's export growth in 2026 — computers and chips contributed 40% of the export increase so far this year.
China is also highly dependent on imported energy. China has used huge reserves to cushion this year's price shock, but the profits of industries that use petroleum products as production inputs, such as textiles, are still being hit.
Two summits are scheduled to be held in the next few weeks. Chinese leaders will use this to observe Trump earlier after the midterm elections. Since China has rare earths chips, the current trade truce arrangement may not be easily impacted by political changes in Washington. What is more worrisome is the domestic situation: consumer consumption is insufficient, making economic growth dependent on AI and other trade. A study by Bloomberg Intelligence wrote: “Risks continue to rise, making it even more urgent for Beijing to rebalance economic growth by strengthening support for domestic consumption.”
Japan
A large number of Japanese companies have interests in the US AI industry, and their stock market was hit hard on Friday. However, the war with Iran and repeated changes in tariff policies will also be key factors affecting the Japanese economy.
Automobile companies contribute a quarter of Japan's exports to the US. According to the agreement reached with Trump, Japanese cars were subject to 15% tariffs, and Tokyo also promised to invest billions of dollars in the US. This economy, which is scarce in resources and usually buys large quantities of Middle Eastern oil, is also being forced to turn to other regions to find oil sources. Japan's oil imports from the US increased by more than 800%, according to the latest monthly data.
Nobuhide Kiuchi, executive economist at the Nomura Research Institute in Tokyo, said, “If the tariff policy and tough policy against Iran are restrained to a certain extent, the deterioration of Japan's export environment will stop.” However, he believes there is a short-term risk: before the new Congress is held on January 3, the US may instead escalate its actions in these two areas.
India
Asia's third-largest economy is also the world's third-largest oil importer, and almost 90% of its crude oil demand depends on overseas procurement. Higher oil prices are putting pressure on government finances, driving up import spending and widening trade deficits, all of which are putting pressure on the rupee. The rupee is one of the major currencies that underperformed this year.
Furthermore, unlike many Asian economies, India is on the import side of AI trade, which is one reason why its stock market has become a kind of safe haven during this week's decline. Costs for IT service providers in India are likely to drop. Even so, economists warn that this critical sector is still vulnerable to a slowdown in global corporate technology spending, and India will eventually need to catch up with the AI sector.
OCBC economist Lavanya Venkateswaran said falling oil prices would “ease one of India's major macroeconomic vulnerabilities” and increase household purchasing power. However, “if corporate technology spending actually slows down, IT budgets that can be adjusted as appropriate may be reduced, which in turn will drag down India's service exports.”
Korea and Taiwan
Two economies, South Korea and Taiwan, are at the cutting edge, supplying the highest capacity chips and storage products, and have achieved extraordinary export growth. A large portion of these products will first reach other destinations and circulate through complex supply chain networks, but the biggest end user is the US data center industry.
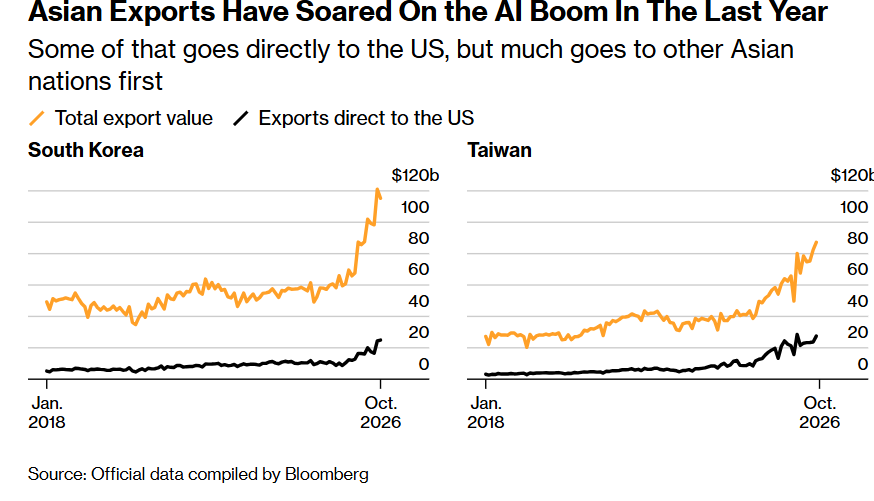
As shown in the chart above, the AI boom has driven a sharp rise in Asian exports over the past year — some products related to AI infrastructure in Asia are sold directly to the US, but many products are generally exported to other Asian economies first.
A major analysis report by Bloomberg Intelligence found that if the AI bubble bursts, the growth of these two Asian economies will be impacted rapidly and drastically, far more than in other regions. HSBC's Fan Limin said that if the US decides to slow down data center construction, other Asian countries may take on part of the demand, thus creating a potential buffer.
ASEAN
Southeast Asia's largest economy, Indonesia, has not benefited much from the AI export boom, and the Philippines has benefited even less. Falling oil prices will free up much-needed fiscal space for Indonesia. The country's energy subsidies have been increased by more than 50%; at the same time, it will also ease some of the inflationary pressure in the Philippines, where the country's inflation rate has soared to close to 8%.
However, for chip-producing countries like Singapore and Malaysia, falling AI investment will weaken their growth momentum. Hardware exports and data center construction are key factors in offsetting the impact of oil prices and boosting economic growth this year. Both central banks withstood calls to tighten monetary policy at recent interest rate meetings, and these decisions may prove to be forward-looking in the future.
Australia
Australia itself is also an important data center construction market. As companies such as Anthropic seek participation, the industry has boosted investment growth and may also trigger a political backlash similar to that of the United States.
However, increased imports of chips and servers, combined with rising energy prices, have reduced Australia's trade surplus this year to its lowest level in ten years. Falling energy prices will help reverse this situation while easing pressure on food prices; these pressures previously pushed the Bank of Australia to become one of the most aggressive central banks in the world to raise interest rates this year.