


- Adobe announced a partnership with Universal Music Group and Warner Music Group to bring licensed clips from their catalogs into Premiere mobile, while Warner Music Group also acquired German digital distributor Zebralution.
- The Adobe deal widens how Warner Music Group’s catalog can be used in personal video creation, and the Zebralution purchase extends its reach in independent digital distribution, both influencing how the business earns from licensing and access to artists.
- We will examine how Warner Music Group's investment narrative is shaped by the Adobe licensing access and the Zebralution acquisition.
Scan how Warner Music Group is leaning into licensing, then widen your watchlist with hand picked peers in the same space using the 21 high quality undiscovered gems.
Warner Music Group Investment Narrative Recap
To own Warner Music Group, you need to believe its catalogs, tech investments and global reach can keep turning streaming adoption and new licensing formats into steadier earnings and cash flow. The Adobe Premiere mobile partnership and Zebralution deal both sit in that licensing story but look incremental to near term numbers rather than a clear swing factor.
The sharper near term focus still sits on execution of cost savings, catalog returns and AI tools while managing debt that is not well covered by operating cash flow. The biggest operational risk is that capital deployed into catalogs, AI and distribution fails to consistently lift margins and free cash generation.
The Adobe Premiere mobile agreement is the most directly linked announcement here because it tests how effectively Warner Music Group can monetize its catalog in new, high usage consumer channels. Clips are licensed for personal, non commercial use, and Adobe funnels commercial users toward paid licenses. That structure keeps the door open for higher value deals if creator demand scales.
For your watchlist, this type of integration matters less for the immediate P&L and more as a signal. It shows how the group is trying to position its catalog for emerging monetization where superfan products, micropayments and AI tools could intersect. The operational question is whether these partnerships translate into measurable uplift alongside cost programs and catalog joint ventures already in motion.
What The Current Forecasts Assume For Warner Music Group
Analysts sketch a medium term picture for Warner Music Group that leans heavily on steady top line expansion and higher margins. The current consensus assumes revenue grows at about 5.4% a year over the next three years, supported by catalog deals, AI centric tools and distribution moves like Zebralution. Earnings today are put at roughly US$665.0 million, with forecasts pointing to about US$1.3 billion by 2029, helped by profit margins rising from 9.1% to 14.9% over the same period. That path implies earnings would almost double, roughly a 2x increase from current levels, if the plan plays out.
Warner Music Group's narrative projects US$8.6 billion revenue and US$1.3 billion earnings by 2029. This requires 5.4% yearly revenue growth and roughly a 2x earnings increase from US$665.0 million.
Those headline assumptions then feed into how analysts think about valuation. To line up with the consensus price target, the stock would need to trade on a P/E of 20.7x in 2029, slightly below the 21.1x multiple referenced today but a touch above the 20.5x mark cited for the wider US entertainment peer group. Analysts cluster around a US$37.81 target, with a wide spread between US$30.00 and US$46.00 that reflects different views on how much of the forecast revenue and earnings path Warner Music Group can deliver from its catalog pipeline, cost programs and licensing partnerships.
Uncover why Warner Music Group's fair value indicates an 18% potential upside to its current price before the market closes that gap.
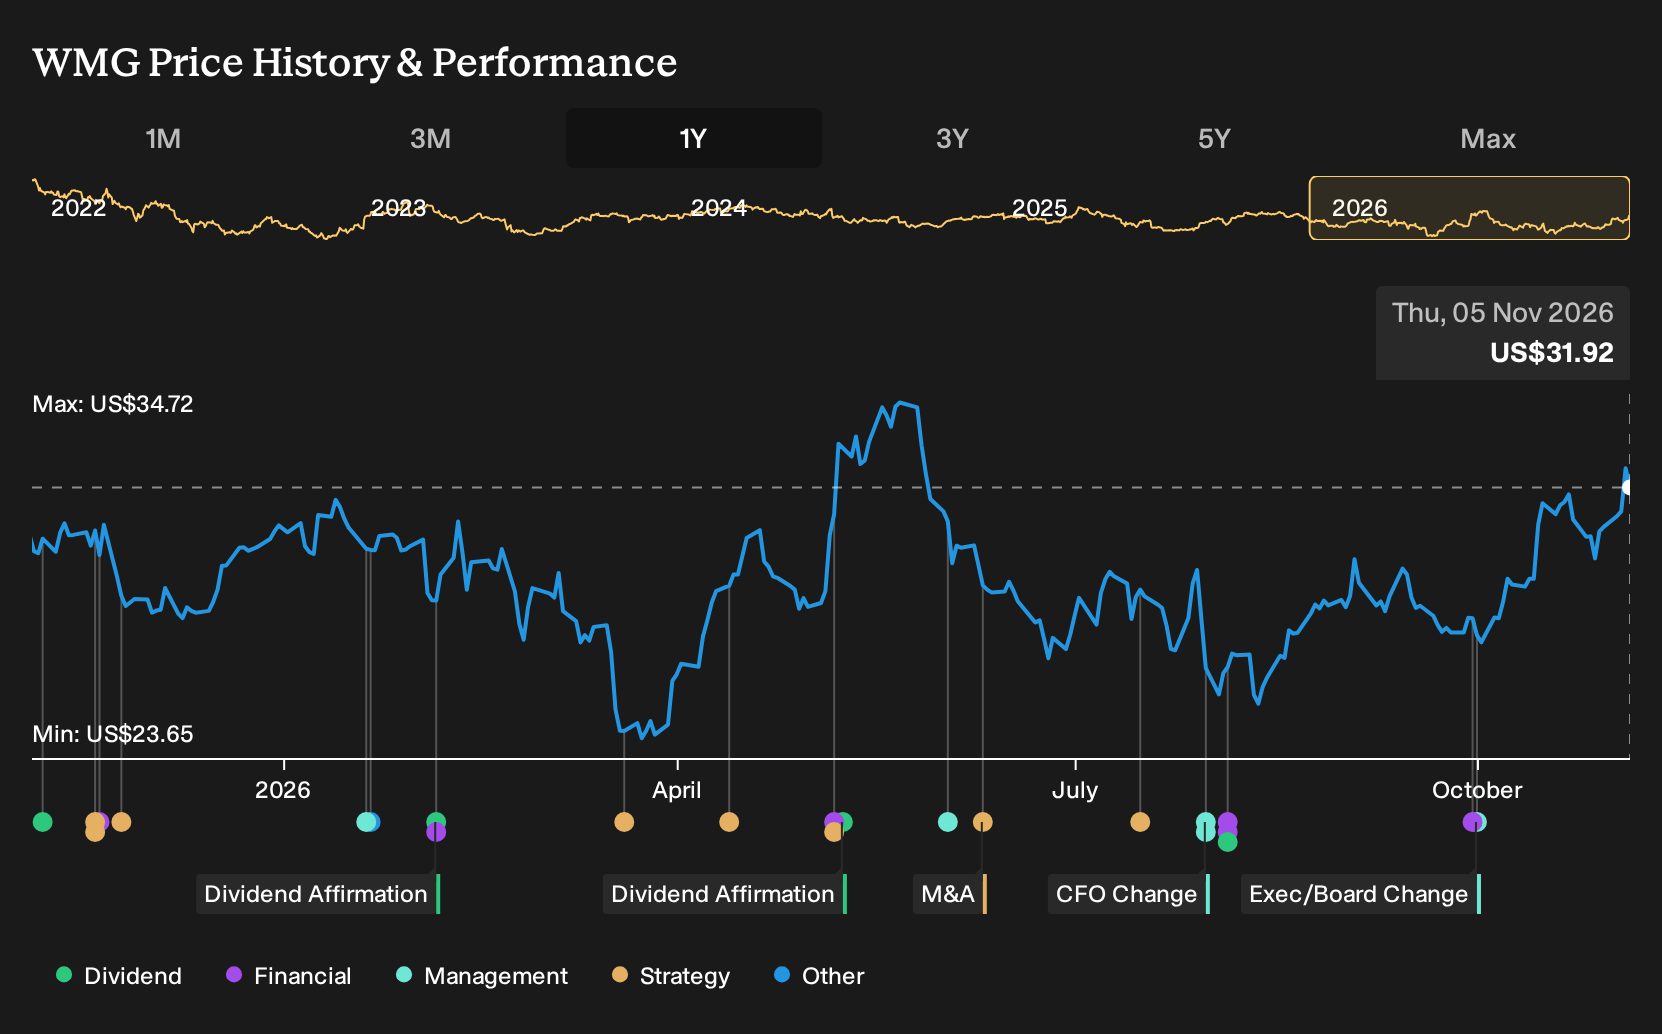
Exploring Other Perspectives
One alternate angle on Warner Music Group leans hard into AI licensing as a potential upside catalyst. The most optimistic analysts were already sketching revenue at about US$9.2b and earnings near US$1.1b by 2029 before this Adobe and Zebralution news landed. You can treat those higher estimates as a ceiling and then ask how fresh licensing deals or distributor acquisitions might shift the story, either upward or downward from here.
Explore 3 other Warner Music Group fair value estimates, including one that suggests up to 40% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Warner Music Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Warner Music Group. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easier to evaluate Warner Music Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Warner Music Group?
If Warner Music Group has you thinking about where else steady cash generation, balance sheet strength or income potential might show up, the Simply Wall St Screener can help you spot other candidates that fit those themes in a structured way.
- For investors who care most about resilience and lower volatility, you could focus on companies flagged as having more robust financial risk profiles through the 32 resilient stocks with low risk scores.
- If quality combined with attractive pricing is your priority, you can filter for businesses that pair solid fundamentals with what our models view as appealing valuations using the 42 high quality undervalued stocks.
- Anyone building an income focused portfolio can zero in on companies with higher yields and consistent distributions by scanning the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com